區間
Research view我們的看法:股價大致合理,不追(未來半年預期漲跌在 -10% 到 +15% 之間) ◆ initial coverage, not investment advice第一次評估,不是投資建議
Default path: Summary, Numbers, What to watch, Playbook (about 8 minutes). The full case is collapsed below — open it for the complete argument.預設動線:摘要、數字、觀察時間點、操作框架,約 8 分鐘;完整論證已收合,點開展開
蘋果不再用高通的上網晶片,但仍在付專利費。高通也剛簽下亞馬遜的 AI 晶片合約。我們的看法:股價大致合理,現在不追,一年目標價 187 美元。 Apple no longer uses Qualcomm's phone-network chip, but it still pays Qualcomm patent fees. Qualcomm also just signed an AI-chip deal with Amazon. Our view: the price is about fair, so we would not chase it; 12-month target price $187.
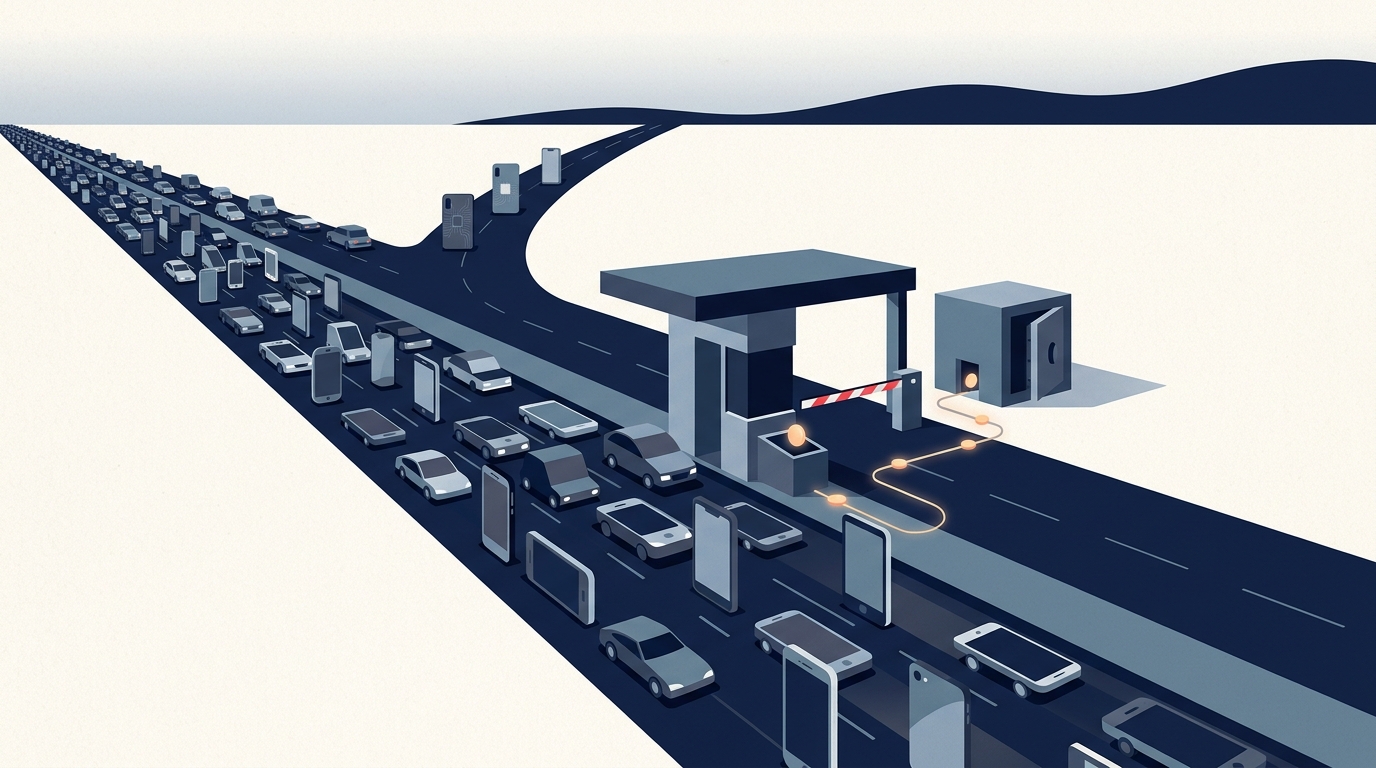
(1) Qualcomm runs two businesses: selling chips, and collecting a patent fee on every phone shipped, no matter whose chip is inside. The chip business is shrinking — Apple switched to its own chip, and pricier memory means Android brands build fewer phones. The fee business keeps going — Apple just renewed its license in September.
1. 高通有兩門生意:賣晶片,以及每支手機出貨就收一筆專利費,不管裡面裝的是誰的晶片。晶片這門正在縮小(蘋果改用自己的、記憶體變貴讓安卓少做手機)。收費這門還在,蘋果 9 月剛續約。
(2) It is looking for its next engine. Automotive is already growing. Data center has a signed Amazon contract, but the money doesn't start arriving until the December 2026 quarter.
2. 它正在找下一台引擎:車用已經在長大;資料中心有亞馬遜合約,但錢要到 2026 年 12 月那一季才開始進帳。
(3) Today's price already reflects most of this, so this analysis is not chasing it here. The one thing that can change the call is whether that December quarter actually shows data-center revenue.
3. 現在股價差不多把這件事反映完了,所以不追。真正能翻案的是那一季有沒有資料中心營收。
Research view: range-bound (expected 6-month return between -10% and +15%, not investment advice).
Target price: $187 (12 months).
Current price: $187.48 (09-28 close).
Implied upside: about 0%.
How the target was built: this analysis projects FY2027 (October 2026 to September 2027) non-GAAP earnings per share (profit per share, excluding one-off items) of $10.40, times an 18x multiple.
Why 18x: against this year's depressed earnings, 18x is above history. Adding back the memory-cost hit, that is at most about 15.7x normal profit — the top of the 13-16x range from the past three completed fiscal years. That extra sliver is already baked into the base case (this analysis's most likely scenario) of $3.0 billion in data-center revenue. This analysis does not grant a higher multiple because nobody knows when memory prices normalize, and the data-center business has no revenue yet.
研究觀點:區間(6 個月內預期報酬介於 -10% 到 +15%,非投資建議)。
目標價:187 美元(12 個月)。
現價:187.48 美元(09-28 收盤)。
潛在漲幅:約 0%。
目標價算法:本研究預估 2027 財年(2026 年 10 月到 2027 年 9 月)每股盈餘 10.4 美元,乘以 18 倍本益比。
為什麼是 18 倍:用今年被壓低的獲利算,18 倍比歷史高。加回記憶體衝擊後,最多等於正常獲利的 15.7 倍,落在過去三年 13 到 16 倍區間的頂端。這一點溢價,已經算進基準情境(我們認為最可能發生的情況)裡 30 億美元的資料中心營收。不給更高的倍數,是因為記憶體何時恢復正常沒人知道,資料中心也還沒出現營收。
Risk factors: data-center revenue arriving late, memory prices staying high longer, or Samsung's flagship phone switching to its own chip.
風險因子:資料中心營收延後、記憶體漲價拖更久、三星旗艦手機改用自家晶片。
Sources for this section: revenue and guidance figures come from Qualcomm's SEC earnings press releases; earnings-call detail comes from the 2026-07-29 transcript; the share price comes from IBKR; analyst consensus comes from Yahoo Finance. Every individual claim is sourced in the ledger at the bottom of this page.
本節出處:財報數字與財測(公司自己給的下一季預估)來自高通向美國證管會申報的財報新聞稿;電話會內容來自 2026-07-29 逐字稿;股價來自 IBKR;分析師共識來自 Yahoo Finance。逐項來源見文末查證表。
Our profit estimates land almost exactly on Wall Street analysts' average. The disagreement is how many times profit the stock deserves.
我們估的獲利和券商分析師幾乎一樣。差別在於:股價該是獲利的幾倍。
| $B, fiscal year ends Sept; EPS non-GAAP十億美元,財年結束於 9 月底;每股盈餘為調整後數字,排除一次性項目 | FY25A2025 財年(實際) | FY26E2026 財年(估) | FY27E2027 財年(估) |
|---|---|---|---|
| Revenue營收 | 44.28 | 42.9 ◆ | 44.3 ◆ |
| — chip sales— 賣晶片 | 38.37 | 36.9 ◆ | 38.6 ◆ |
| — patent fees— 收專利費 | 5.58 | 5.55 ◆ | 5.4 ◆ |
| — data center— 資料中心 | about 0 (not yet broken out)約 0(尚未單獨揭露) | a few hundred million; custom chips not booked yet數億、客製晶片還沒進帳 | 3.0 ◆ |
| EPS ($)每股盈餘(美元) | 12.03 | 10.51 ◆ | 10.4 ◆ |
FY26E = the first three quarters' actual results plus the midpoint of the company's own FQ4 guidance.2026 財年估計=前三季實績加第四季公司財測中值。
Compared with sell-side analysts: this analysis projects FY2027 EPS of $10.40 against a consensus of $10.18 (Yahoo Finance, 09-28, 37 analysts) — almost identical. Revenue is where the gap sits: this analysis's $44.3B runs 1.2% below the $44.9B consensus, because this analysis counts the data-center business at only 60% of management's own target.
和賣方分析師比較:2027 財年每股盈餘本研究 10.4 美元,賣方共識 10.18 美元(Yahoo Finance,09-28,37 位分析師);營收本研究 443 億,共識 449 億,本研究偏低 1.2%,因為資料中心只算管理層目標的六成。
This analysis projects FY2026 and FY2027 EPS (earnings per share, on a non-GAAP basis that excludes one-off items) of $10.51 and $10.40, and sets a target price of $187, based on the FY2027 figure times an 18x price-to-earnings ratio (P/E — how many years of today's profit it takes to earn back the share price). Over the past three completed fiscal years Qualcomm's average P/E ran about 13 to 16 times. This analysis grants 18x because, after adding back the finance chief's stated memory-cost hit of more than $1.50 per share, that is at most about 15.7 times normal profit — the top of the range.
本研究預估 2026、2027 財年每股盈餘為 10.51、10.4 美元,目標價 187 美元,基於 2027 財年每股盈餘乘以 18 倍本益比。過去三個完整財年,高通的年平均本益比約 13 到 16 倍。給 18 倍,是因為加回財務長所說超過 1.5 美元的記憶體衝擊後,它最多等於正常獲利的 15.7 倍,落在區間頂端。
How the P/E range is measured: this analysis divides the yearly average of IBKR month-end prices by that year's adjusted (non-GAAP) earnings per share, using completed fiscal years only. Finance websites often show a P/E in the low 20s; that figure uses standard accounting (GAAP) earnings over the past four quarters, so the two numbers do not compare directly. ◆
本益比區間怎麼算:本研究用 IBKR 每月收盤價的年平均,除以當年的調整後每股盈餘,只用已結束的財年。財經網站常見的 20 幾倍,是用一般會計盈餘算的過去四季本益比,算法不同,不能直接比。
Probabilities are this analysis's judgment, not a measured figure.機率為本研究判斷,非量測數字。
Where today sits: current price $187.48 vs. target price $187 — practically the same.現在的位置:現價 187.48 美元對目標價 187 美元,幾乎一樣。
How the three prices reconcile: $187 IS the base-case scenario, and it is this analysis's formal number. The three scenarios weighted by probability come to about $189 — only about 1% higher, because the upside and downside tails are roughly symmetric.
目標價 187 就是基準情境,是本研究的正式數字。把三種情況依可能性加權平均,約 189 美元,只高約 1%,因為往上和往下的幅度差不多。
Three checkpoints over the next six months, each with a "see this, do this" rule written in advance.
接下來半年有三個時間點,每一個都事先寫好了「看到什麼,就做什麼」。
If it hits:達標: Reaffirms the FY27 $5B data-center target, and next-quarter guidance includes data-center revenue: hold the base case.重申 2027 財年資料中心目標 50 億美元,且下一季財測包含資料中心營收:維持基準情境。
If it misses:落空: Cut below $3B (below this analysis's own assumption): cut the EPS estimate and the target price to about $169 (EPS of about $9.4 times 18x). Cut to somewhere between $3-4B: this analysis's estimate is unchanged, but the entry zone stays where it is — no adding early.下修到 30 億以下(低於本研究的假設):下修每股盈餘,目標價降到約 169 美元(每股盈餘約 9.4 美元乘 18 倍)。下修到 30 到 40 億之間:本研究的估計不變,但進場區維持不動、不提前加碼。
If it hits:達標: $2.15 (guidance midpoint) or above: no action.達到 2.15 美元(財測中值)以上:不動作。
If it misses:落空: Below $2.05 (guidance floor): cut the handset assumption.低於 2.05 美元(財測下緣):下修手機假設。
If it hits:達標: Data-center revenue reaches $500M or more: raise the bull-scenario probability to 35%.資料中心營收達 5 億美元以上:樂觀情境機率調高到 35%。
If it misses:落空: Zero or undisclosed: raise the bear-scenario probability to 35% and review the target price.為零或不揭露:悲觀情境機率調高到 35%,並重審目標價。
If it hits:達標: Qualcomm chip share holds at 70% or above: no action.高通晶片占比維持七成以上:不動作。
If it misses:落空: The top-end Ultra model switches globally to Samsung's own chip: cut the FY2028 handset revenue assumption.頂級款 Ultra 全球改用三星自家晶片:下修 2028 財年手機營收。
If it misses:落空: Any ruling that threatens Qualcomm's right to use Arm's chip-design architecture: re-check whether this whole view still holds.任何威脅高通使用 Arm 架構權利的判決:重新檢查這份判斷還成不成立。
If it hits:達標: Vested share count grows: Amazon is really buying.解鎖股數增加:代表亞馬遜真的在買。
If it misses:落空: Flat for four straight quarters: discount the data-center assumption.連續四季沒有增加:資料中心假設打折。
If it misses:落空: Licensing-segment revenue falls 10% or more year over year: cut the licensing-revenue assumption.授權部門營收因此年減 10% 以上:下修授權收入假設。
Right now: don't chase the price, and if already holding, keep holding. Entry needs two things at the same time: the price back in the $140-155 range, and the November earnings report reaffirming the data-center target with next-quarter guidance that includes data-center revenue. Having only one of the two means keep waiting.
現在不追,已持有續抱。進場需要同時符合兩個條件:價格回到 140 到 155 美元,而且 11 月財報重申資料中心目標、下一季財測包含資料中心營收。只符合其中一個,就繼續等。
Open this card if the price falls 30%, and check each row. No row turning red (green and pending both still pass) means the drop is sentiment — follow the add-on plan above. Any row turning red means stop and re-examine the thesis.
股價跌三成時打開這張卡,逐題檢查。沒有任何紅燈(綠燈和待定都算過關),代表跌的是情緒,照加碼條件執行。任何一題轉紅,先停手,重新審視論點。
Are Apple, Samsung and other big brands still paying licensing fees?
蘋果、三星等大品牌還在付專利授權費嗎?
Where to check: licensing-segment quarterly revenue at least $1.2B; the licensing note in each 10-Q filing. Now: FQ3 $1.28B; Apple renewed in September.
去哪裡查:授權部門每季營收是否至少 12 億美元;季報裡的授權說明。現況:第三季 12.8 億;蘋果 9 月續約。
Does the patent-fee business still keep $65 or more of every $100 in revenue, before tax?
收專利費這門生意,每 100 元營收還能賺 65 元以上(稅前)嗎?
Where to check: the segment income table in each quarterly filing. Now: FQ3 69%.
去哪裡查:季報的部門損益表。現況:第三季 69%。
Does Samsung's flagship phone still use Qualcomm chips in more than half its units?
三星旗艦手機還有一半以上用高通晶片嗎?
Where to check: specs at each February Galaxy launch. Now: S26 over 70%; could turn within 3 years.
去哪裡查:每年 2 月 Galaxy 發表時的規格。現況:S26 超過七成。三年內可能轉紅。
Has the data center started producing real revenue?
資料中心開始有真營收了嗎?
Where to check: the data-center revenue line in each quarterly filing; Amazon's warrant-vesting count. Now: first revenue expected in the December quarter; could turn within 3 years.
去哪裡查:季報的資料中心營收;亞馬遜認股權證解鎖股數。現況:第一筆預計在 12 月那一季。三年內可能轉紅。
Is automotive revenue still growing above 20% a year?
車用營收還在年增兩成以上嗎?
Where to check: the automotive revenue line in each quarterly filing. Now: FQ3 up 61% year over year.
去哪裡查:季報的車用營收。現況:第三季年增 61%。
Is Qualcomm's right to use Arm's chip architecture still secure?
高通使用 Arm 架構的權利安全嗎?
Where to check: rulings in the Arm appeal and the Qualcomm-vs-Arm case. Now: won at trial, Arm has appealed; could turn within 3 years.
去哪裡查:Arm 上訴案與高通告 Arm 案的判決。現況:一審全勝,上訴中。三年內可能轉紅。
Is Qualcomm's share of phone processors still above 20%?
手機處理器市占還有兩成以上嗎?
Where to check: Counterpoint's quarterly market-share report. Now: 23% in Q2 2026. Q1 was also 23%, below 27% a year earlier — slipping.
去哪裡查:Counterpoint 每季市占報告。現況:2026 年第二季 23%。第一季也是 23%,比一年前的 27% 低,正在下滑。
This is the first research piece on Qualcomm, rated range-bound with a $187 target price.
這是第一份高通研究,觀點為區間,目標價 187 美元。
What happened: the stock closed around $124 in early April (an intraday low of $121.99), then closed at $251.02 on May 29 — this year's high close. It fell to a $147.61 close on July 31, with an intraday low of $142.89 in early August, before closing at $201.97 on September 25 and $187.48 on September 28 — down 7.17% that day in a broad chip-stock selloff with no company news. The rise came from the ByteDance (May) and Amazon (September) AI-chip contracts; the fall came from July's cut to the Apple-share assumption and the memory price hikes. ✓ IBKR daily bars日K
現象:股價在 4 月上旬收盤跌到約 124 美元(盤中最低 121.99),5 月 29 日收盤 251.02 美元,是今年收盤最高;7 月 31 日收盤 147.61 美元,8 月上旬盤中最低 142.89 美元;9 月 25 日收盤 201.97 美元,9 月 28 日收盤 187.48 美元,單日跌 7.17%,當天半導體類股普跌,沒有公司消息。上漲來自字節跳動(5 月)與亞馬遜(9 月)的 AI 晶片合約;下跌來自 7 月財報下修蘋果份額與記憶體漲價。✓ IBKR 日K
What we did: built the first model and watch list. There is no prior number to compare against, so this entry carries no before/after table.
我們的動作:建立第一版模型與觀察點。沒有前次數字可比,所以不列調整前後的對照表。
| Date日期 | View觀點 | Target price目標價 | Close收盤價 |
|---|---|---|---|
| 2026-09-29 | Range-bound區間 | 187 | $187.48 |
Append-only ledger.附加式(append-only)紀錄。
Qualcomm in one sentence: it used to make its money selling phone chips. That business is shrinking now, but as long as anyone in the world sells a phone that gets online, Qualcomm still collects a patent fee on it. At the same time it is trying to sell chips into cars and cloud data centers. The stock price sits stuck in the middle: the old engine hasn't finished winding down, and the new engine's revenue hasn't shown up yet.
用一句話說高通:它以前靠賣手機晶片賺錢。現在手機這門生意在縮,但只要世界上還有人賣能上網的手機,高通幾乎都能抽一筆專利費。同時它在試著把晶片賣進汽車和雲端機房。股價現在卡在中間:舊引擎還沒掉完,新引擎的營收還沒出現。
Many people think of Qualcomm as simply "the phone-chip company." That is only half true.
很多人以為高通「就是做手機晶片的」。這個說法其實只對一半。
Most of Qualcomm's revenue, about 87%, comes from selling chips (a unit called QCT). The other 13% or so comes from patent fees (a unit called QTL, which works like a toll booth). The fee business is smaller but far more profitable: out of every $100 of revenue, chips keep about $30 before tax, while patent fees keep about $70.
高通的營收主要來自賣晶片,約占八成七(這個部門叫 QCT)。剩下約一成三來自收專利費(這個部門叫 QTL,等於一座收費站)。專利費的錢雖然少,賺得卻比較多:每 100 元營收,晶片約賺 30 元,專利費約賺 70 元。
For the past year the market has worried about two things. The first is Apple: after six years of work, Apple built its own modem chip, and most new iPhones in 2026 use it instead of Qualcomm's. The second is memory: memory chip prices spiked, and phone brands cut specs and shipments to control cost.
過去一年,市場一直在為兩件事擔心。第一件是蘋果:蘋果花了六年自己做出數據機,2026 年新 iPhone 大多改用自家晶片。第二件是記憶體:記憶體價格大漲,手機品牌為了控制成本,砍了規格和出貨量。
Both are real, and both already show up in the earnings reports and guidance. In the third quarter of fiscal 2026, handset-chip revenue fell 20% year over year.
這兩件事都是真的,也都已經寫在財報和財測裡。2026 財年第三季,手機晶片營收年減 20%。
But two things get talked about less. First, even when Apple doesn't use Qualcomm's chip, it still has to pay Qualcomm's patent fee — and it just renewed that license in September. Second, Qualcomm landed its first large cloud customer in data centers, Amazon, and the contract is written into a filing with the SEC.
但有兩件事比較少人講。第一,蘋果不用高通的晶片,還是要付高通專利費,而且 9 月剛續約。第二,高通在資料中心拿到了第一張大型雲端客戶的合約,對象是亞馬遜,合約寫進了向證管會申報的文件。
So this report's judgment is: Qualcomm is not a sinking phone-chip company, and it is not yet an AI-chip company either. It is a company whose profit is near a trough while it swaps engines. Today's price roughly reflects that state, which is why the view here is range-bound. The real answer arrives with the December-quarter earnings report.
所以這份報告的判斷是:高通不是一家正在沉沒的手機晶片公司,也還不是一家 AI 晶片公司。它是一家獲利處在谷底、正在換引擎的公司。現在的股價大致反映了這個狀態,所以觀點是區間。答案要等 12 月那一季的財報揭曉。
Qualcomm makes money two ways: selling chips, and collecting patent fees — and the fee business runs more than twice the margin of the chip business.
高通靠兩門生意賺錢:賣晶片,和收專利費,後者利潤率是前者的兩倍多。
Qualcomm designs its chips but owns no chip factories. It hands production to outside contract chipmakers, a setup called fabless. ✓ 10-K · FY25
高通只設計晶片,自己不蓋工廠。晶片交給外面的晶圓代工廠(專門替別人生產晶片的工廠)生產,這種模式叫無晶圓廠(fabless)。 ✓ 10-K · FY25
The two new flagship chips launched in September 2026 are made by TSMC on its 2-nanometer process, TSMC's most advanced. ✓ ETtoday · TechTimes · 09-23
2026 年 9 月發表的兩顆新旗艦晶片,由台積電用最先進的 2 奈米製程生產。 ✓ ETtoday · TechTimes · 09-23
Why it matters: the most advanced wafers cost the most. In July the finance chief said costs were rising across wafers, packaging, testing and memory, and that Qualcomm is raising its own chip prices to pass them on. So the handset-chip profit margin now depends on those price increases sticking. ✓ call transcript · 07-29
這跟高通的利潤有關:製程愈先進,晶圓愈貴。財務長在 7 月說,晶圓、封裝(把晶片包成可以焊上主機板的樣子)、測試和記憶體的成本全面上漲,高通正在把這些成本反映到自己的晶片售價上。所以手機晶片的利潤率,要看漲價能不能守住。 ✓ 逐字稿 · 07-29
The handset-chip weakness has two causes. First, Apple switched to its own chip. Second, memory prices: the memory cost inside a phone jumped, so brands either cut corners on the processor or simply built fewer phones. The finance chief said the 2026 handset market would run about ten-some percent below 2025.
手機晶片變差的原因有兩個。第一是蘋果改用自家晶片。第二是記憶體漲價:一支手機的記憶體成本大漲,品牌只好在處理器上省錢,或乾脆少做幾支。財務長說 2026 年手機市場會比 2025 年少十幾個百分點。
This point moves opposite to memory stocks generally: the more expensive memory gets, the more memory makers earn, and the harder Qualcomm's handset chips are to sell.
這一點和記憶體股是反向連動的:記憶體越貴,記憶體廠越賺,高通的手機晶片越難賣。
Qualcomm's core technology has three layers: one integrated phone chip, one modem that is genuinely hard to build, and one library of communications patents.
高通的核心技術有三層:一顆整合的手機晶片、一套很難做的數據機、一整座通訊專利庫。
One phone chip does four jobs at once: it thinks, it draws the screen, it runs AI, and it makes the call. Engineers call this a "system on a chip" (SoC — several once-separate chips squeezed onto one piece of silicon, like fitting a whole small computer onto a postage stamp). Qualcomm's Snapdragon packs in: a CPU for general computing (Qualcomm's own Oryon core), a GPU for graphics (Adreno), an NPU for AI computing (Hexagon), and the modem and radio system that connects to the cellular network. The newest generation, launched in September 2026, comes in two versions: the 8 Elite Gen 6 and a higher-performance 8 Elite Extreme Gen 6. Both are made by TSMC on its 2-nanometer process, and their main cores reach 5GHz for the first time. So the flagship chips keep improving on schedule. The handset revenue problem is Apple leaving and memory costs squeezing Android phones, not a weak product. ✓ Qualcomm · 09-22
一顆手機晶片同時做四件事:想事情、畫畫面、跑 AI、打電話。工程師把這種晶片叫「系統單晶片」(把好幾個本來各自獨立的晶片,縮在同一片矽上,像把一整台小電腦塞進一張郵票)。高通的 Snapdragon 裡面有:負責一般運算的 CPU(高通自己設計的 Oryon 核心),負責畫面的 GPU(Adreno),負責 AI 運算的 NPU(Hexagon),以及負責連上行動網路的數據機和射頻系統(收發無線電訊號的零件)。最新一代在 2026 年 9 月發表,分成兩顆:8 Elite Gen 6,以及效能更高的 8 Elite Extreme Gen 6。兩顆都由台積電用 2 奈米製程生產,主核心時脈首次達到 5GHz。旗艦晶片仍按時更新。手機營收下滑,原因是蘋果退出和記憶體漲價壓縮安卓,不是產品跟不上。 ✓ Qualcomm · 09-22
Think of a phone as a company. The CPU is the general manager. The GPU is the art department. The NPU is the newly formed AI team. The modem is the switchboard connecting to the outside world. Qualcomm packs the entire company into a chip the size of a fingernail.
比喻:如果手機是一間公司,CPU 是總經理,GPU 是美術部,NPU 是新成立的 AI 部門,數據機是對外的電話總機。高通把整間公司塞進一顆指甲大小的晶片。
Without the picture: the chip has four areas. They handle general computing, graphics, AI, and the phone network. The phone-network area is the modem.
不看圖也能懂:這顆晶片分成四區,分別負責一般運算、畫面、AI 和連上電信網路。連網那一區就是數據機。
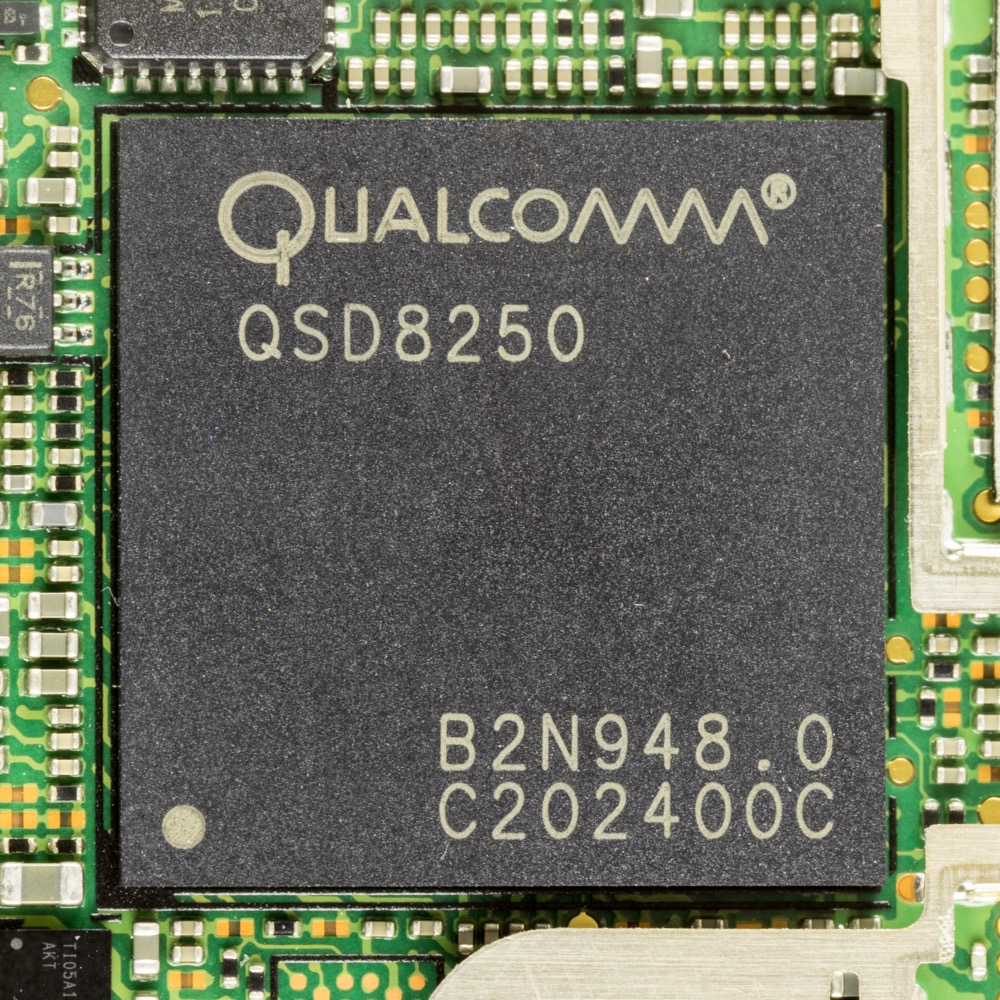
Early Snapdragon (QSD8250), HTC Desire phone board早期 Snapdragon(QSD8250),HTC Desire 手機主機板
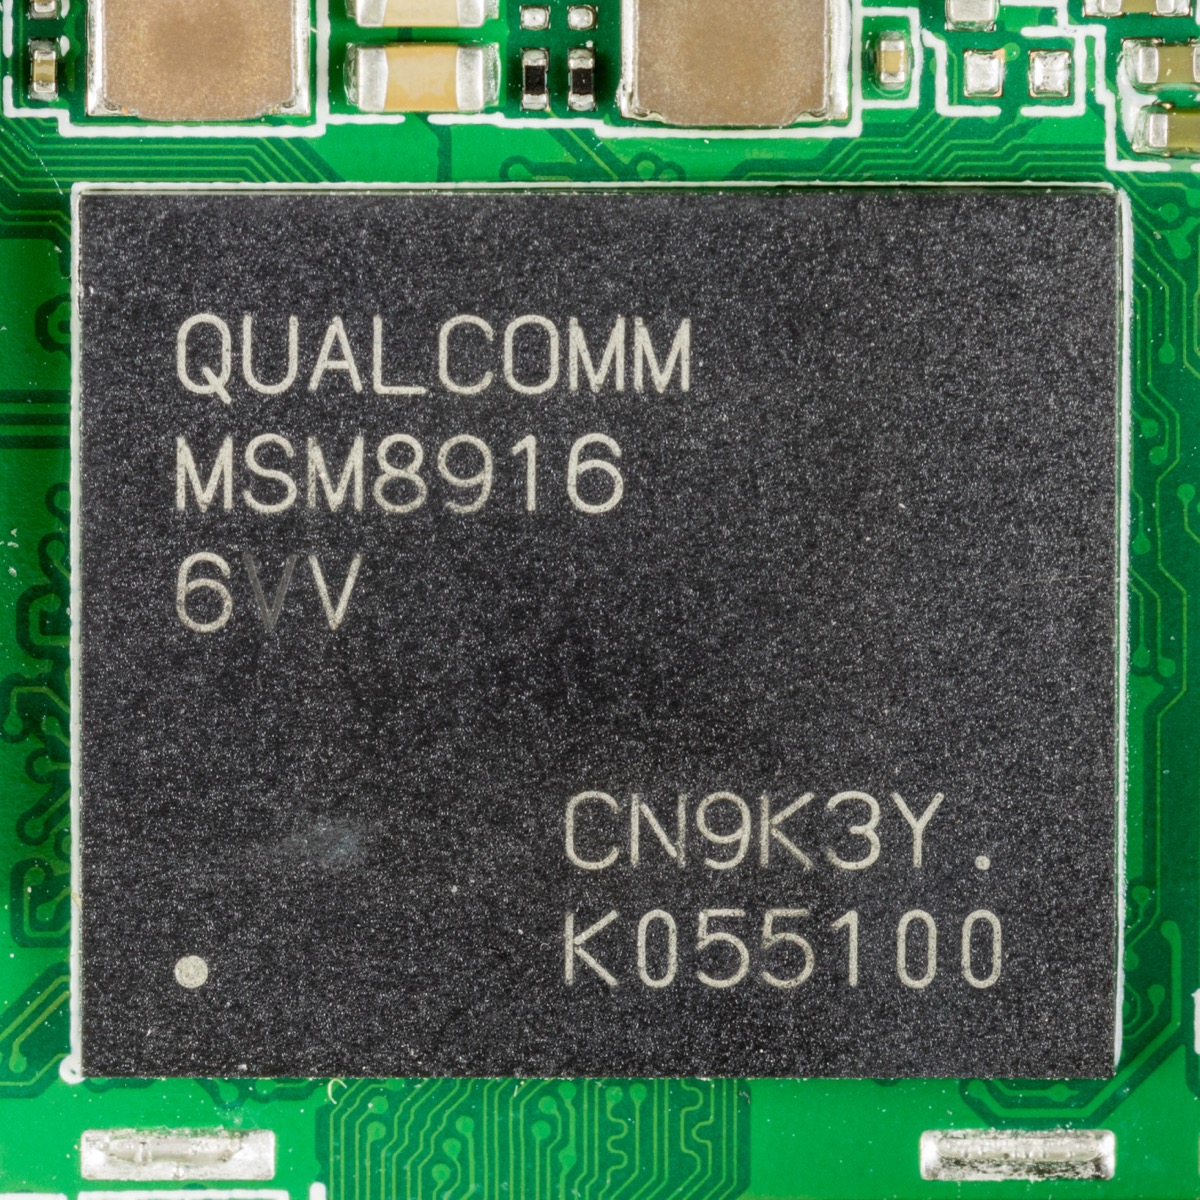
Snapdragon 410 (MSM8916), a processor with a built-in modemSnapdragon 410(MSM8916),處理器和數據機做在同一顆
2026: Snapdragon 8 Elite Gen 6 and Extreme Gen 6 (official badge; both share it)2026:Snapdragon 8 Elite Gen 6 與 Extreme 版(兩顆共用這個官方標誌)
The hard part about a modem (the part of the chip that connects a phone to the cell network) isn't calculating fast — it's connecting to every phone carrier's network on earth. Apple took six years to build its first one, and it still lacks one fast frequency band. Underneath that: the modem turns a phone's data into radio signals and sends them to a cell tower, and it has to work across 2G through 5G and hundreds of frequency-band combinations worldwide, passing certification with every carrier, one at a time.
數據機(讓手機連上電信網路的那一塊)真正難的地方不是算得快,而是全世界每一家電信公司的網路都要連得上。蘋果花了六年才做出第一顆,而且還缺一種高速頻段。底層的技術是:數據機負責把手機的資料轉成無線電訊號,送到基地台,它要能連上 2G 到 5G 幾代網路、全世界上百種頻段組合,還要一家一家通過電信商的認證。
Apple is the clearest example. In 2019, Apple paid $1 billion for Intel's phone-modem business, taking on about 2,200 engineers. It then took almost six years before its first in-house modem, the C1, shipped in 2025. The C1 and C1X still don't support 5G mmWave (millimeter wave, a very fast but short-range high-frequency band) even today.
蘋果是最好的例子。蘋果在 2019 年花 10 億美元買下 Intel 的手機數據機部門,接收約 2,200 名工程師。之後又花了將近六年,2025 年第一顆自家數據機 C1 才上市。C1 和 C1X 至今仍不支援 5G 毫米波(mmWave,一種速度很快、但傳不遠的高頻段)。
In other words, a modem is a technology you can only build up slowly, through time and certification. Apple managed it, but at a large cost; most phone brands cannot.
換言之,數據機是一個要靠時間和認證慢慢堆出來的技術。蘋果做得到,但付了很大的代價;大部分手機品牌做不到。
Think of Qualcomm as a highway toll booth: it used to both sell the car and collect the toll. Apple now builds its own car, but it still drives on this road, so the toll still gets paid — up to about $13 per phone, no matter whose chip is inside.
高通像一條高速公路的收費站:以前它同時賣車又收過路費。蘋果現在自己造車,但還是要走這條路,過路費照付,一支手機最多約 13 美元,不管裡面裝的是誰的晶片。
Here's the mechanism behind that toll. Any phone that makes calls or connects to the internet has to comply with international standards like 3G, 4G and 5G. Those standards are built on patented technology called a Standard Essential Patent (SEP — a patent you cannot avoid using if you want a standard-compliant phone).
收費的機制是這樣的:手機只要能打電話、上網,就必須遵守 3G、4G、5G 這些國際通訊標準。這些標準裡寫進了很多專利技術,叫做「標準必要專利」(SEP,要做得出能打電話的手機就躲不掉的專利)。
Whoever holds these patents must license them to every phone brand under the FRAND principle (Fair, Reasonable and Non-Discriminatory — the patent has to be licensed at a fair price to every phone brand, not just sold to insiders). Qualcomm's published 5G rate: for a license covering standard-essential patents only, 2.275% of wholesale price for a single-mode phone, 3.25% for a multi-mode phone, capped at a $400 wholesale price for the calculation.
持有這些專利的公司,依照 FRAND 原則(專利必須用公平價格授權給每家手機品牌,不能只賣給自己人)授權給所有手機品牌。高通公開的 5G 費率是:只授權標準必要專利,單模手機收批發價的 2.275%,多模手機收 3.25%;計費的批發價最高只算到 400 美元。
Without the picture: every phone pays Qualcomm a patent fee, whoever made its chip. Only phones with a Qualcomm chip also pay Qualcomm for the chip itself.
不看圖也能懂:不管手機用誰的晶片,都要付高通專利費。只有用高通晶片的手機,才會再付高通一筆晶片錢。
AI answering a question after it has learned — a step called inference — burns electricity every single time, and it happens far more often than "training," the earlier step where the AI first learns. So cloud operators care most about the electricity cost of each answer. Qualcomm wants to sell power-efficient cards for that job to cloud data centers; it already has a contract, but shipments are just getting started.
AI 學會之後回答問題的這個階段叫「推論」,每回答一次都要耗電,而且次數遠多於「訓練」(AI 學會之前的那個階段)。所以雲端業者最在意每回答一次要花多少電費。高通想賣比較省電的卡給雲端機房做這件事;合約已經有了,出貨才剛要開始。
Data-center revenue is not zero today, but it is small. After the Alphawave purchase, its connection chips count as data-center revenue: in the first nine months of FY2026 that added about $182M compared with a year earlier ($88M in the third quarter alone). Custom-chip revenue has not started yet. ✓ 10-Q · FQ3 FY26
資料中心營收現在不是零,只是很小。併入 Alphawave 之後,它的連線晶片算進資料中心營收:2026 財年前九個月比去年多約 1.8 億美元,其中第三季多 8,800 萬美元。客製晶片的營收還沒開始。 ✓ 10-Q · FQ3 FY26
Why Alphawave matters: it is a UK company that makes the technology chips use to pass data to each other at very high speed, and it also designs custom chips for clients. Qualcomm bought it for an enterprise value of about $2.4 billion, and the deal closed on December 18, 2025, about a quarter ahead of plan. The logic is simple. In an AI data center, thousands of chips must constantly send data to one another. If that link is slow, fast chips sit idle. The high-speed optical links in the Amazon contract use this kind of technology. ✓ Qualcomm · 2025-12-18
為什麼要買 Alphawave:它是一家英國公司,專做讓晶片之間高速傳資料的技術,也替客戶設計客製晶片。高通用約 24 億美元的企業價值(連同對方負債一起算的收購總價)買下它,2025 年 12 月 18 日完成,比原訂時間早約一季。道理很簡單:AI 機房裡成千上萬顆晶片要不停互傳資料,傳得慢,算得再快的晶片也只能等。亞馬遜合約裡的高速光連接,用的就是這類技術。 ✓ Qualcomm · 2025-12-18
Qualcomm's strategy is to cut into the inference market using the power-efficiency skills it built for phone chips:
高通的策略是用它做手機晶片練出來的省電能力,切進推論市場:
Cars are increasingly "computers on wheels" — the industry calls this the software-defined vehicle. The chips a car needs now stretch from the dashboard and navigation all the way to driver-assistance systems. Qualcomm bundles all of this as the Snapdragon Digital Chassis.
汽車越來越像「裝了輪子的電腦」,這叫軟體定義汽車。一台車需要的晶片從儀表板、導航,一路擴到駕駛輔助。高通把這整套叫 Snapdragon Digital Chassis。
Auto chips have one quirk: an automaker picks its chip years before the car actually ships — usually a two-to-four-year gap. So the "design-win pipeline" (the total value of chip orders an automaker has already committed to, for future cars) is a preview of future revenue, not money booked this year. Qualcomm's pipeline grew from $30 billion in September 2022 to $65 billion in June 2026 — orders already won, not yet all shipped.
車用晶片有一個特性:車廠先選定晶片,兩到四年後新車上市才開始出貨。所以「設計訂單」(design-win pipeline,車廠已選定、未來會出貨的訂單總額)是未來營收的預告,不是今年進帳的錢。高通的設計訂單從 2022 年 9 月的 300 億美元,到 2026 年 6 月的 650 億美元,也就是已經接下的訂單,還沒全部出貨。
Three jobs for Qualcomm chips in a car
高通晶片在一台車裡做的三件事
From order to revenue
從接單到營收
The $65B design-win pipeline means orders won, not yet all shipped.
650 億美元設計訂單,等於已接單、還沒全部出貨。
Qualcomm's deepest moat is the patent toll booth. Its shallowest is data center, where it is still the new arrival.
高通最深的護城河是專利收費站;最淺的是資料中心,那裡它還是新來的。
Mechanism: decades of accumulated standard-essential patents, plus long-term license agreements already signed with every major phone brand.
機制:數十年累積的通訊標準必要專利,加上和各大手機品牌簽好的長約。
What it would take to break it: a mass expiration of patents combined with Qualcomm losing its position in the next standard (6G), or courts worldwide sharply cutting the fair rate.
要打破它,世界必須發生什麼:大量專利到期,而且在下一代標準(6G)裡高通失去地位;或各國法院大幅壓低合理費率。
Time to replicate: about one communications-standard generation, roughly ten years.
Who's already taking share: Huawei's license expired without renewal; licensing-segment revenue fell 3% year over year in the third quarter.
複製時間:大約一個通訊標準世代,約十年。
誰已經在搶這門生意:華為的授權到期未續約;授權部門第三季年減 3%。
Where to check: licensing-segment quarterly revenue; renewal news from Apple and Samsung; LexisNexis's annual 5G patent ranking (the January 2026 report still puts Qualcomm in the top tier).
去哪裡檢查:授權部門季營收;蘋果與三星的續約消息;LexisNexis 每年的 5G 專利排名(2026 年 1 月報告仍把高通列在最前段)。
The key point: this moat protects the fact that the whole industry pays, not Qualcomm's own chip market share. The Apple case proves the two can be completely separated.
重點:這條護城河保護的是「整個產業都要付費」,不是高通的晶片市占。蘋果案證明兩者可以完全分開。
Mechanism: years of accumulated global frequency-band and carrier certification work.
機制:全球頻段與電信商認證的長期累積。
Who's taking share: Apple's C-series modem; the integrated chips from MediaTek and Samsung.
誰在搶這門生意:蘋果的 C 系列數據機;聯發科與三星的整合晶片。
Where to check: teardown reports on new iPhones; Samsung's flagship chip lineup.
去哪裡檢查:新 iPhone 拆解報告;三星旗艦手機的晶片配置。
Current state: by shipment volume, MediaTek held 31% share and Qualcomm 23% in Q2 2026. Qualcomm's edge is in high-end phones.
現況:以出貨量計,聯發科 2026 年第二季市占 31%、高通 23%。高通的優勢在高階機。
Who's taking share: Samsung's own Exynos chip returning to flagship phones; MediaTek pushing upmarket; Chinese brands designing their own chips.
誰在搶這門生意:三星自家 Exynos 晶片回流;聯發科往高階進攻;中國品牌自己設計晶片。
Qualcomm is a new entrant here, competing against Nvidia, AMD, Broadcom and Marvell. Its current weapons are a power-efficient design and the customer contracts it has already signed — not a moat.
高通在這裡是新進者,對手是 Nvidia、AMD、Broadcom、Marvell。它目前的武器是省電設計和已簽下的客戶合約,不是護城河。
| Indicator指標 | Where it's published在哪裡公布 | Current reading現在的讀數 | Threshold and meaning門檻與意義 |
|---|---|---|---|
| Amazon warrant shares vested亞馬遜認股權證已解鎖股數 | Qualcomm's quarterly 10-Q and annual 10-K filings高通每季的 10-Q 與年報 10-K | 3.75M shares vested at signing簽約時先解鎖 375 萬股 | Growing means real purchases; flat for four straight quarters means discount the data-center assumption股數增加代表真的有採購;連續四季不動,資料中心假設要打折 |
| DRAM contract priceDRAM 合約價 | TrendForce's monthly price reportTrendForce 每月報價 | still rising through 20262026 年仍在上漲 | Continued increases mean Android brands keep cutting specs, pressuring Qualcomm's handset chips記憶體續漲,安卓手機砍規格,高通手機晶片承壓 |
| Samsung Galaxy flagship chip split三星 Galaxy 旗艦晶片配置 | The launch event and spec pages each February每年 2 月發表會與規格頁 | S26 over 70% Qualcomm; the S27 Ultra's Korea/Europe switch to Samsung's own chip is still a rumorS26 超過七成用高通;S27 Ultra 韓歐版改用自家晶片仍是傳聞 | Below 50% is a clear signal of share loss低於五成就是明確的份額流失 |
| Phone processor market share手機處理器市占 | Counterpoint quarterly report每季報告 | 23% (Q2 2026) | Below 20% is a warning sign低於 20% 是警訊 |
| Automotive revenue growth車用營收年增率 | Qualcomm's quarterly earnings release高通每季財報 | +61% in the third quarter第三季 +61% | Below 20% means the design-win pipeline is converting to revenue more slowly低於 20% 代表設計訂單轉營收的速度變慢 |
Over the next two years, automotive and data center will grow; Apple's share will keep shrinking; handsets depend on when memory prices cool off.
接下來兩年,會長大的是車用和資料中心;會縮的是蘋果;手機要看記憶體什麼時候降溫。
Without the picture:
不看圖也能懂:
Amazon (SEC filing), ByteDance (Bloomberg), a 200-megawatt deployment with Saudi Arabia's Humain, and Meta's server CPU — four named customers. Part of this is already reflected in the stock price.
亞馬遜(證管會文件)、字節跳動(Bloomberg)、沙烏地 Humain 的 200 百萬瓦部署、Meta 的伺服器 CPU。四個具名客戶。其中一部分已經反映在股價上。
From $1.87B in FY2023, to $3.96B in FY2025, to $1.59B in the single third quarter of FY2026 — up 61%.
從 2023 財年的 18.7 億美元,到 2025 財年的 39.6 億,2026 年第三季單季就有 15.9 億。
Apple renewed its license in September 2026, effective April 2027, removing licensing's biggest open question.
蘋果在 2026 年 9 月續簽授權,2027 年 4 月生效,移除了授權部門最大的懸念。
Returned $12.6B to shareholders in FY2025; added a new $20B buyback authorization in March 2026 with no expiration date. The quarterly dividend is $0.92, starting with the June 2026 payment (it was $0.89 before).
2025 財年回饋 126 億美元;2026 年 3 月新增 200 億美元買回授權,沒有到期日。季配息從 2026 年 6 月那次起為 0.92 美元,之前是 0.89 美元。
Once Apple's share falls close to zero, that gap stops widening. If memory prices ever roll over, Android revenue could recover more than the $1.50-per-share hit it took.
蘋果份額降到接近零之後,這個缺口不會再擴大;記憶體價格一旦回落,安卓營收有機會拿回超過 1.5 美元的每股盈餘。
The renewal is good news, but the financial terms weren't disclosed. If the new rate is lower than the old one, licensing revenue shrinks too. This cannot be judged either way yet — it is a watch item, not a positive.
續約是好消息,但財務條件沒有揭露。如果新費率比舊約低,授權收入也會縮。這一點目前無法判斷,只能觀察,不能當利多。
Nvidia, Broadcom and Marvell have worked with large cloud customers for years already; this is Qualcomm's first time breaking in. Amazon taking warrants instead of cash also shows the buyer holds the pricing power.
Nvidia、Broadcom、Marvell 已經和大型雲端客戶合作多年,高通是第一次打進去。亞馬遜拿認股權證換訂單,也代表議價力在買方。
Handset-chip revenue fell 20% year over year in the third quarter. Nobody can accurately predict how long the memory cycle runs.
第三季手機晶片年減 20%。記憶體循環沒有人能準確預測。
Cash fell from $7.85B at the end of FY2024 to $4.53B in June 2026; total debt $15.27B. The cash went to acquisitions (Alphawave, Modular) and $7-9B a year in buybacks.
現金從 2024 財年底的 78.5 億美元,降到 2026 年 6 月的 45.3 億;總負債 152.7 億。錢流向收購(Alphawave、Modular)和每年 70 到 90 億的股票買回。
Reports say the S27 Ultra's Korea and Europe versions will switch to Samsung's own Exynos 2700 — still a rumor, unconfirmed.
有報導稱 S27 Ultra 的韓國與歐洲版改用三星自家 Exynos 2700,目前仍是傳聞。
China's State Administration for Market Regulation (SAMR, the agency that reviews mergers for antitrust concerns) has investigated Qualcomm's Autotalks acquisition since October 2025, still unresolved; ByteDance as a customer also carries US export-control risk.
中國市場監管總局(SAMR,負責反壟斷審查)2025 年 10 月起調查高通收購 Autotalks 一案,至今未結;字節跳動這個客戶也有美國出口管制的風險。
If data-center revenue disappoints in the December quarter, the market could push the multiple back to 14x. 14 times $10.40 is about $146 — roughly a fifth below today's price.
如果 12 月那一季資料中心營收不如預期,市場可能把倍數打回 14 倍,14 乘以 10.4 約 146 美元,比現價低約兩成。
The sell-side story is "a phone-chip maker that lost Apple, plus an unproven AI story." This analysis thinks that framing mixes two different things together.
賣方說「失去蘋果的手機晶片商,加一個還沒證實的 AI 故事」;本研究認為這個說法把兩件不同的事混在一起了。
Without the picture: the left side lists four things the market believes; the right side gives our answer to each. The same points are written out in full just below.
不看圖也能懂:左邊是市場的四個看法,右邊是我們逐條的回答。同樣的內容,下面有完整文字版。
First, the multiple problem is smaller than it looks — but it is not nothing. Qualcomm trades near 18 times today, more expensive than any of the past three years. The finance chief said pricier memory cost more than $1.50 per share of this year's profit. Even adding all of it back, today's price is only about 16 times normal profit — the top of the historical range. In other words, the market is paying a little extra for the data-center business, but far less than the headline 18x suggests.
第一,倍數的問題比看起來小,但不是沒有。高通今天約 18 倍本益比,比過去三年都貴。財務長說,記憶體漲價讓今年每股盈餘少了超過 1.5 美元。就算全部加回,現價也約是正常獲利的 16 倍,落在歷史區間頂端。換言之,市場替資料中心付了一點溢價,但遠少於表面的 18 倍所暗示的程度。
Second, "Apple risk" is really two separate risks. The chip supply contract only covers iPhones launched between 2024 and 2026 — that part is confirmed to disappear. The patent license is a separate contract, and it was just renewed. The market often talks about these two as one thing.
第二,「蘋果風險」其實是兩個風險。晶片供應合約只涵蓋 2024 到 2026 年發表的 iPhone,這部分確定會消失。專利授權是另一份合約,剛剛續約。市場常把兩件事混在一起講。
Third, this analysis does not claim the data-center target will definitely be hit. The $15 billion FY2029 figure and the $5 billion FY2027 figure are both management targets, not guidance. This analysis's own base case counts only 60% of that.
第三,本研究不主張資料中心目標一定會達成。2029 年 150 億美元、2027 年 50 億美元都是管理層的目標,不是財測。本研究的基準情境只算了六成。
So the conclusion: the sell-side consensus is broadly right, and this analysis's own profit estimate is almost identical to it. The real difference is timing — if data-center revenue really shows up in the December quarter, the market will start believing the 2027 target. If it doesn't, today's multiple won't hold.
所以結論是:賣方的共識大致正確,本研究的獲利估計和賣方幾乎一樣。真正的差別是時間點:12 月那一季如果真的出現資料中心營收,市場會開始相信 2027 年的目標;如果沒有,現在的倍數就撐不住。
Qualcomm has been the subject of many market fears over the past decade. Three of the first four times, the patent toll booth held up — Huawei is the only licensing customer that was genuinely lost. The fifth fear is now happening — to the chip division.
高通過去十年被市場擔心過很多次。前四次裡有三次,專利收費站都撐住了;華為是唯一真的流失的授權客戶。第五次正在晶片部門身上發生。
| Fear恐懼 | First appeared第一次出現 | What actually happened後來發生什麼 |
|---|---|---|
| US FTC sues Qualcomm for monopoly美國聯邦貿易委員會告高通壟斷 | 2017 | The Ninth Circuit Court of Appeals fully reversed the ruling in August 20202020 年 8 月,第九巡迴上訴法院全數推翻原判決 |
| Apple refuses to pay patent fees and sues蘋果拒付專利費並提告 | 2017 | Settled in April 2019, a six-year license plus a two-year extension option2019 年 4 月和解,簽下六年授權加兩年延長選擇權 |
| Huawei sanctioned by the US華為被美國制裁 | 2019 | Export license revoked in May 2024; Huawei's license has not been renewed since2024 年 5 月出口許可被撤銷;華為的授權至今未續約 |
| Arm sues Qualcomm for license breachArm 告高通違反授權 | 2022 | Qualcomm won outright at trial in September 2025; Arm has appealed2025 年 9 月高通一審全勝;Arm 已上訴 |
| Apple builds its own modem蘋果自己做數據機 | 2019 | Actually happened starting in 2025; most new iPhones in 2026 switched to Apple's own chip2025 年起真的發生,2026 年新 iPhone 大多改用自家晶片 |
Management has been selling shares, but the amounts are small and most sales follow a pre-scheduled plan. The company's cash is shifting from buybacks toward the data-center business.
管理層在賣股,但金額都小,多數是事先排好的計畫性賣出;公司的錢正從買回股票轉向資料中心。
In phones, Qualcomm ranks second by volume and stays strong at the high end; in data center, it is the challenger.
在手機,高通以量計排第二、以高階計仍強;在資料中心,它是挑戰者。
Sixteen terms to read the rest of this page.
看懂本文其餘章節需要的十六個術語。
| Claim主張 | Verdict判定 | Value · source · as-of數值 · 來源 · 日期 |
|---|---|---|
| Price & valuation價格與估值 | ||
| 1. 09-25 close09-25 收盤 | ✓ IBKR | $201.97 · daily bar日K |
| 2. 09-28 close $187.48, -7.17%09-28 收盤 $187.48,-7.17% | ✓ IBKR daily bar日K | $187.48 · 2026-09-28 |
| 3. 52-week low to high過去一年最低到最高價 | ✓ IBKR | $121.99–$259.92 |
| 4. 09-28 sector-wide selloff, no company news09-28 半導體類股普跌,無公司消息 | ✓ 24/7 Wall St. | 09-28 |
| 5. Shares outstanding流通股 | ✓ compiled彙整 | ~1.07B · 09-28 |
| 6. FQ3 FY26 diluted sharesFQ3 FY26 稀釋股數 | ✓ SEC 8-K | 1,069M |
| Financials & guidance財報與財測 | ||
| 7. FY23/24/25 revenue營收 | ✓ SEC 8-K | $35.82B / $38.96B / $44.28B |
| 8. FY25 QCT and three segments與三段 | ✓ SEC 8-K FY25 | $38.37B; $27.79/$3.96/$6.62B |
| 9. FY25 QTL | ✓ SEC 8-K FY25 | $5.58B, flat持平 |
| 10. QCT/QTL EBT margin FY25稅前利潤率 | ✓ SEC 8-K FY25 | 30% / 72% |
| 11. Non-GAAP EPS FY23-FY25非 GAAP 每股盈餘 | ✓ SEC 8-K | 8.43 / 10.22 / 12.03 |
| 12. Why FY25 GAAP EPS was only $5.01FY25 GAAP EPS 5.01 的原因 | ✓ SEC 8-K FY25 | $5.7B deferred-tax valuation allowance57 億美元遞延所得稅評價備抵 |
| 13. FQ1-FQ3 FY26 revenue營收 | ✓ SEC 8-K | $12.25B / $10.60B / $9.95B |
| 14. FQ1-FQ3 non-GAAP EPS非 GAAP 每股盈餘 | ✓ SEC 8-K | 3.50 / 2.65 / 2.21 |
| 15. Handset YoY by quarter, FY26手機各季年增 | ✓ SEC 8-K | +3% / -13% / -20% |
| 16. Auto YoY by quarter, FY26車用各季年增 | ✓ SEC 8-K | +15% / +38% / +61% |
| 17. QTL FY26 by quarter各季 | ✓ SEC 8-K | $1.59B / $1.38B / $1.28B |
| 18. FQ4 FY26 guidance財測 | ✓ SEC 8-K FQ3 | rev營收 $9.7-10.5B; EPS 2.05-2.25 |
| Earnings-call transcript電話會逐字稿 | ||
| 19. Apple revenue roughly halves from the Sept to Dec quarter蘋果營收 9 月季到 12 月季約減半 | ✓ CFO, call transcriptCFO,逐字稿 | 07-29 |
| 20. Apple share "materially lower" than the prior ~20% estimate; FY27 Apple product revenue below the prior ~$2B guide蘋果份額「遠低於」先前約 20% 估計;FY27 蘋果產品營收低於先前約 20 億的指引 | ✓ CFO, call transcriptCFO,逐字稿 | 07-29 |
| 21. Qualcomm loses $5.7-5.9B a year of Apple revenue年失去蘋果營收 57 至 59 億 | ✗ dropped已刪除 | secondary summary, no primary source二手摘要,無一手來源 |
| 22. FY27 data-center target $5B; non-handset over 50% of QCT and growing over 60% YoYFY27 資料中心 50 億目標;非手機占 QCT 超過 50%、年增超過 60% | ✓ CFO, call transcriptCFO,逐字稿 | 07-29 |
| 53. Memory hit cut QCT Android revenue 20% YoY, EPS impact over $1.50, called a potential tailwind記憶體衝擊使 QCT 安卓營收年減 20%,EPS 影響超過 1.5 美元,稱為潛在順風 | ✓ CFO, call transcriptCFO,逐字稿 | 07-29 |
| 54. Dec-quarter QCT revenue "small sequential growth"; old seasonality no longer applies; March quarter grows further12 月季 QCT 營收較 9 月季小幅成長;舊季節性不適用;3 月季再成長 | ✓ CFO, call transcriptCFO,逐字稿 | 07-29 |
| 55. FQ4 guidance detail: handsets ~$5.2B, auto +~60% YoY, IoT flat, QCT EBT margin 23-25%, opex ~$2.7BFQ4 手機約 52 億、車用年增約 60%、IoT 持平、QCT 稅前利潤率 23-25%、非 GAAP 營業費用約 27 億 | ✓ CFO, call transcriptCFO,逐字稿 | 07-29 |
| 56. Two custom-chip customers are global-scale hyperscalers, purchase orders in hand, wafers already started兩個客製晶片客戶皆為全球級超大型雲端,已有採購單、已開始投片 | ✓ CFO, call transcriptCFO,逐字稿 | 07-29 |
| 57. Data-center margin well below core business, 1.5-2pp drag on QCT margin; core gross margin 48-50%資料中心毛利率遠低於本業,拖累 QCT 毛利率 1.5 至 2 個百分點;本業毛利率 48 至 50% | ✓ CFO, call transcriptCFO,逐字稿 | 07-29 |
| 58. Prior FY29 non-handset target was $22B先前 FY29 非手機目標 220 億 | ✓ CEO, call transcriptCEO,逐字稿 | 07-29 |
| 59. 2026 handset market down 10-some percent from 20252026 手機市場較 2025 年減十幾個百分點 | ✓ CFO, call transcriptCFO,逐字稿 | 07-29 |
| 60. Fabless model: relies on a limited number of third-party manufacturers無晶圓廠模式:依賴少數外部代工廠 | ✓ 10-K FY25 | 2025-11 |
| 61. 8 Elite Gen 6 and Extreme Gen 6 made on TSMC 2nm8 Elite Gen 6 與 Extreme Gen 6 採台積電 2 奈米 | ✓ ETtoday · TechTimes | 2026-09-23 |
| Company targets公司目標 | ||
| 23. FY29 targets: non-handset $40B, data center over $15B, auto $10B, IoT over $14B, EPS over $18目標:非手機 400 億、資料中心逾 150 億、車用 100 億、IoT 逾 140 億、EPS 逾 18 | ✓ Qualcomm IR | 06-24 |
| 24. Handsets about 1/3 of QCT by FY29手機占 QCT 約三分之一(FY29) | ✓ Qualcomm IR | 06-24 |
| 25. Auto design-win pipeline車用設計訂單 | ✓ Qualcomm IR | $65B · 06-24 |
| 26. Auto FY26 exit run-rate: raised in July to about $7B (from $6B)車用 FY26 年化出場:7 月上修為約 70 億(先前 60 億) | ✓ call transcript, corrected逐字稿,已更正 | 07-29 |
| 27. FY2026 data-center revenue is already about $300MFY26 資料中心營收約 3 億 | ✗ dropped已刪除 | no source found無來源 |
| Customers & contracts客戶與合約 | ||
| 28. AWS warrant: 25M shares, $161.26 strike, expires 2036-09-03, first 3.75M vested at signing, $60B purchase cap認股權證:2,500 萬股、$161.26、2036-09-03 到期、首批 375 萬股解鎖、上限 600 億 | ✓ SEC 8-K | 09-08 |
| 29. ByteDance ASIC contract字節跳動客製晶片合約 | ✓ Bloomberg | 05-26 |
| 30. Humain 200MW deploymentHumain 200MW 部署 | ✓ PR Newswire | 2025-10-28 |
| 31. AI200 (2026), AI250 (2027), 768GB LPDDR per card每卡 | ✓ CNBC | 2025-10-27 |
| 32. Dragonfly C1000, Meta customer, 2H28 productionDragonfly C1000,Meta 客戶,2028 下半年量產 | ✓ CNBC | 06-24 |
| 33. Alphawave close date and EVAlphawave 完成日與企業價值 | ✓ Qualcomm press release新聞稿 | 2025-12-18 · ~$2.4B |
| 34. Modular acquisitionModular 收購 | ✓ Yahoo Finance | ~$3.9B · 2026-06 |
| 35. Apple license renewal, effective 2027-04-01, terms undisclosed蘋果授權續約,2027-04-01 生效,條款未揭露 | ✓ Qualcomm press release新聞稿 | 2026-09-24 |
| 36. Modem supply contract covers 2024-2026 iPhones數據機供應合約涵蓋 2024 至 2026 iPhone | ✓ CNBC/MacRumors | 2023-09 · 2026-09-24 |
| 37. 2019 settlement: six-year license plus a two-year option2019 和解:六年授權加兩年選擇權 | ✓ Apple Newsroom | 2019-04-16 |
| 38. Apple bought Intel's modem business for $1B, ~2,200 employees蘋果收購 Intel 數據機部門,10 億美元,約 2,200 人 | ✓ Apple Newsroom | 2019-07-25 |
| 39. C1/C1X don't support mmWaveC1/C1X 不支援毫米波 | ✓ compiled press reports彙整報導 | 2026 |
| Legal & regulatory法律與監管 | ||
| 40. 5G rate 2.275%/3.25%, $400 wholesale cap費率 2.275%/3.25%,上限 $400 | ✓ Qualcomm 5G licensing terms授權條款頁 | |
| 41. FTC case reversed by the Ninth Circuit案第九巡迴上訴法院推翻 | ✓ compiled彙整 | 2020-08-11 |
| 42. Arm case: Qualcomm won at trial 2025-09-30, Arm appealed 10-01案:高通一審勝 2025-09-30,Arm 10-01 上訴 | ✓ Qualcomm IR/Futurum | |
| 43. Huawei export license revoked華為出口許可撤銷 | ✓ Business Standard | 2024-05-08 |
| 44. SAMR investigates the Autotalks acquisition, unresolvedSAMR 調查 Autotalks 收購,未結 | ✓ CNBC | 2025-10-10 |
| Market share & competition市占與競爭 | ||
| 45. Samsung S26 over 70% Snapdragon三星 S26 逾 70% Snapdragon | ✓ compiled press reports彙整報導 | |
| 46. S27 Ultra Korea/Europe switching to Exynos 2700S27 Ultra 韓歐版改用 Exynos 2700 | ⚠ unconfirmed rumor未經確認的傳聞 | Digitimes et al. |
| 47. Counterpoint Q2 2026 AP share市占 | ✓ compiled彙整 | MediaTek 31%, Qualcomm 23%聯發科 31%、高通 23% |
| 48. Apple 65% of phones over $600, H1 2026蘋果占高階手機 65%(2026 上半年) | ✓ AppleInsider/Counterpoint | 08 |
| Insiders & ownership內部人與持股 | ||
| 49. Institutional/insider ownership機構/內部人持股 | ⚠ data providers disagree口徑不一 | 74–78% / 1–2.6% |
| 50. Sell-side consensus: 37 analysts, avg. PT $194.13, Hold; FY26 EPS 10.48, FY27 EPS 10.18賣方共識:37 位、平均目標價 194.13、持有;FY26 EPS 10.48、FY27 EPS 10.18 | ✓ Yahoo/stockanalysis | 09-28 |
| 51. Insider sales (Amon x3, Palkhiwala x3), all small or 10b5-1內部人賣出(Amon 三筆、Palkhiwala 三筆),皆小額或 10b5-1 | ✓ SEC Form 4/MarketBeat | |
| 52. Dividend $0.92, $20B buyback authorization, FY25 shareholder return $12.6B, cash $4.53B, debt $15.27B股息 $0.92、200 億買回授權、FY25 回饋 126 億、現金 45.3 億、負債 152.7 億 | ✓ Qualcomm IR/SEC 8-K | 2026-03-17 |
| This analysis's own judgment (not the 59 sourced claims)本研究判斷(不計入 59 筆查證) | ||
| Target price ($187 = FY27E EPS x 18x)目標價(187=2027財年每股盈餘×18倍) | ◆ | |
| Scenario prices and probabilities (25/50/25)情境價位與機率(25/50/25) | ◆ | weighted加權 ~189.5 |
| FY26E EPS build (3 quarters actual + FQ4 guidance midpoint)推算(前三季實績+第四季財測中值) | ◆ | 10.51 |
| Normalized EPS (FY27E + the memory-cost add-back)正常化每股盈餘(2027財年估+記憶體衝擊加回) | ◆ | ~11.9 |
| P/E band (annual-average calc, FY23-FY25, the three completed fiscal years)本益比帶(年均計算,FY23-FY25 三個完整財年) | ◆ | 13.1–15.9× |
| Market cap and dividend yield (computed at the live close)市值與殖利率(以即時收盤計算) | ◆ | ~$200B · ~2.0% |
Rows 21 and 27 above are the 2 dropped claims — kept in the ledger, marked as dropped, so the page shows what didn't make the cut and why.上表第 21、27 筆即為已刪除的 2 筆查證 — 留在表裡並標示已刪除,讓讀者看到哪些數字被拿掉、為什麼。

