6,660
10-08 close (-2.70% on the day; 09-02: 7,810)10-08 收盤(當日 -2.70%;09-02 是 7,810)
Suggested path: the conclusion, the four-line chain block, numbers, catalysts, playbook and the update log, about 8 minutes. The full argument, the glossary and the source ledger stay collapsed until you open them.建議讀法:先看結論,再看卡點四行、數字、催化劑、操作框架和更新紀錄,約 8 分鐘。完整論證、名詞解碼和逐項來源表都收合,點開才會展開。
Largan makes high-end phone lenses for Apple. It now wants to use the same precision manufacturing for fiber parts inside AI data centers. That new business is called CPO (co-packaged optics).大立光(Largan)替蘋果做高階手機鏡頭,現在想把同一套精密功夫,用在 AI 資料中心的光纖零件上(這門生意叫 CPO,共同封裝光學)。
Conclusion: still avoid. The target price falls from NT$5,850 to NT$4,500.結論:維持迴避,目標價從 5,850 元下修到 4,500 元。
一句話:第 3 季毛利率只有 42.21%,跌破我們事先設定的 48% 下檔門檻,所以目標價從 5,850 元下修到 4,500 元,觀點維持迴避。10-08 收盤 6,660 元,到目標價還要跌 32.4%。
One line: Q3 gross margin was only 42.21%, below the 48% downside bar we set in advance. So the target price falls from NT$5,850 to NT$4,500 and the view stays avoid.
The 10-08 close of NT$6,660 is still 32.4% above the target.
已持有:維持預設,分批減碼。原本讓核心倉可以續抱的兩個條件都沒有達成,所以這個例外取消。新資金:不買。進場區改為 3,300–3,800 元,現價比上緣高 75.3%。「迴避」是不買,不是放空。
Holding: keep the default and scale out in tranches. Both conditions that would have let the core position stay failed, so that exception is gone. New money: do not buy.
The entry zone is now NT$3,300–3,800; the close is 75.3% above its top. "Avoid" means do not buy, not short.
Personal research, not investment advice個人研究,非投資建議
(1) The variable-aperture upgrade in the iPhone 18 Pro and Pro Max (both launched 2026-09-10) is real revenue, already in guidance. It is the biggest camera spec jump in a decade and lifts flagship lens ASP (average selling price) by roughly 50%, with Largan as one of the primary high-end suppliers (exact share unverified) — but this is a cyclical spec bonus that recurs every one to two upgrade cycles, not a reason to permanently re-rate the multiple.
這一段在做的事:把大立光真正的優勢與盲目的樂觀炒作劃清界線。公司的實力是真的,但拆開數據會發現 — 現在的股價已經把未來的利多全數「預支完畢」了。
1 · 可變光圈是真的,但這只是常態性的「換代紅利」
2 · 2026 年看似驚人的成長,其實是「匯率魔術」
3 · 市場把「AI CPO 的夢想」畫得太滿
4 · 連董事長自己都說了實話
TP:目標價: NT$4,500 (previous NT$5,850), 6-month horizon — the derivation is broken out below. 4,500 元(前次 5,850 元),期間 6 個月 — 推導拆在下面四格。
2026/2027 EPS modelled at NT$159 / NT$173.
Target price = 2027E EPS 173 × 26× PER = 4,498, rounded to NT$4,500.
本研究預估 2026/2027 年 EPS 為 159/173 元。
目標價 = 2027E EPS 173 × 26 倍 PER = 4,498,取整 4,500 元。
Largan's own 2023–25 PER band is roughly 12–20× ◆ estimated概算. That band is a cyclical mid-point, not a ceiling — in the 2015–17 upgrade boom the stock traded well above 20× for long stretches. 26× is "top of the band plus about 30%": a judgment call, not a derivation.
大立光自己 2023–25 年的 PER 區間概算約 12–20 倍 ◆ 概算。這個帶是循環股的中樞,不是天花板 — 2015–17 規格升級大年,它曾長期在 20 倍以上交易。26 倍是「循環帶上緣再加約三成」:這是判斷,不是數學推導。
The premium is real: CPO optionality plus Largan's position as one of Apple's primary high-end lens suppliers. But 38× means booking an unverified 2028 bull case as today's cash flow. This analysis will not.
溢價是真的:CPO 的選擇權,加上大立光身為蘋果高階鏡頭主力供應商之一的地位。但 38 倍等於把還沒驗證的 2028 藍天,當成今天的現金流入帳。本研究不跟。
TP 4,500 implies a PBR of about 3.0×, against the close's 4.5×.
目標價 4,500 對應 PBR 約 3.0 倍,收盤則是 4.5 倍。
Method premise, stated plainly. The target price is 2027E EPS × 26×, and it holds only if, over the next six months, the market moves its pricing benchmark back from "the 2028 blue sky" to "2027 earnings you can verify." If the market keeps pricing off 2028, time is not on this view's side.
這一段在做的事:最誠實的自我批判 — 主動列出這個判斷可能在什麼情況下被打臉,以及為什麼即便風險很高,本頁選擇「迴避」而不是「放空」。
1 · 時間不站在這個判斷這邊(市場還在作夢)
目標價(26 倍)建立在一個前提上:未來 6 個月內,市場會從熱炒 2028 年的遠大夢想,冷靜下來看 2027 年的真實獲利。萬一未來半年市場依然盲目相信 2028 年的 AI 夢,這個預測就會落空。
2 · 最誠實的弱點:就算獲利完全命中,股價也不一定會跌
3 · 有哪三件事會讓股價繼續居高不下?
4 · 為什麼只選擇「迴避」,而不是「放空」?
Risk factors: a repeat of the 2025 Q2-style FX shock (NT$4.22bn quarterly loss precedent) · CPO timeline slipping into 2028 · Apple's dual-sourcing policy structurally capping ASP · Sunny Optical catching up in Android high-end.
風險因子:台幣急升重演2025Q2式匯損衝擊(單季42.2億前科) · CPO時程滑動至2028年 · 蘋果雙供應商政策結構性壓抑ASP · 舜宇光學(2382.HK)在安卓高階急起直追。
Sources for this section (consolidated here instead of inline): price & valuation = Yahoo股市/鉅亨網 (2026-09-02) + computed · Q2/H1 2026 actuals & monthly revenue = 鉅亨網 earnings coverage (2026-07/08) · variable-aperture & iPhone 18 = TechNews (2026-06) + 時報/豐雲學堂 (2026-08) · CPO/FAU disclosures & chairman quotes = 2026-07 earnings call transcript via simpletechtrend + 工商時報/經濟日報 (2026-07/08) · consensus = FactSet via 鉅亨網 (2026-08) · buyback = 中央社 (2026-02) · estimates, TP and view = this analysis ◆. Per-number ledger: see the Sources section.本節出處(統一註記於此,不逐句插標):價格與估值=Yahoo股市/鉅亨網(2026-09-02)+本研究計算 · Q2/H1 2026實績與月營收=鉅亨網財報報導(2026-07/08)· 可變光圈與iPhone 18=TechNews(2026-06)+時報/豐雲學堂(2026-08)· CPO/FAU揭露與董事長發言=2026-07法說會轉述(simpletechtrend)+工商時報/經濟日報(2026-07/08)· 共識=FactSet經鉅亨網轉載(2026-08)· 庫藏股=中央社(2026-02)· 預估、目標價與觀點=本研究判斷◆。逐數字查證表見〈資料來源〉章。
一句話:大立光是蘋果高階鏡頭的主力供應商之一,想再進 AI 光纖零件。它不是卡點,毛利仍高於同業,但第 3 季明顯變薄;這次股價買的是新角色。
One line: Largan is one of Apple's main high-end lens suppliers and wants into AI fiber parts.
It is not a choke point, its margin is still above peers but clearly thinner in Q3. The share price is paying for the new role.
1. 角色:做手機鏡頭,想做 AI 資料中心的光纖接頭。手機鏡頭佔今天營收的 95% 以上,蘋果是最大客戶(比例公司沒有公布)(未驗證)。光纖接頭還在試產,第一張訂單是最小規格的單排光纖。
1. Role: it makes phone lenses and wants to make fiber connectors for AI data centers. Phone lenses are over 95% of revenue today, and Apple is the largest customer (the share is undisclosed) (unverified). The fiber connector is still in trial production, and the first order is the smallest configuration, a single row of fibers.
2. 卡點類型:不是卡點。蘋果還有第二家鏡頭供應商,玉晶光,所以大立光不是唯一出路。光纖接頭這邊,董事長說從試產到小量產約需 6 個月到 1 年,還沒有重複下單,也查不到客戶認證要幾季。所以不給「認證卡點」這個標籤。(公司說法,未驗證)
2. Choke type: not a choke point. Apple has a second lens supplier, Genius Electronic Optical, so Largan is not the only way out. On the fiber side, the chairman says trial production to small volume takes 6 months to 1 year. There is no repeat order yet, and no source gives the customer qualification length in quarters, so the page does not use the "qualification choke" label. (company statement, unverified)
3. 利潤守不守得住:大部分還留在大立光,但這一季明顯變薄。2025 年每賣 100 元,扣掉直接成本剩 50.4 元;2026 年第 3 季只剩 42.2 元,最近四季約剩 47.1 元(本研究推算)。同業通常只剩 20 到 30 元。
3. Rent: most of it still stays with Largan, but it got clearly thinner this quarter.
In 2025, of every NT$100 of sales, NT$50.4 was left after direct costs. In Q3 2026 only NT$42.2 was left. The last four quarters left about NT$47.1 (this analysis's calculation).
Peers typically keep NT$20 to 30.
4. 已經反映:角色改變。12 個月內,股價相當於近四季每股獲利(EPS)172.38 元的倍數,從約 11 倍漲到 38.6 倍。法說前的共識 2026 年 EPS 是 187.88 元,本研究降到 159 元。兩個數字都撐不起 38.6 倍。市場付的是「大立光也能做 AI 光纖零件」,不是鏡頭獲利變多;鏡頭獲利這一季是變少。
4. Already priced in: the new role. Within 12 months the price went from about 11 times to 38.6 times trailing earnings per share (EPS) of 172.38. Consensus 2026 EPS before the call was 187.88, and this analysis now says 159. Neither supports 38.6 times. The market is paying for "Largan can also make AI fiber parts", not for higher lens profit; lens profit fell this quarter.
一句話:目標價從 5,850 元下修到 4,500 元。2027 年 EPS 從 225 元降到 173 元,倍數 26 倍沒有動;現價到目標價的距離,從 -14.5% 拉大到 -32.4%。
One line: the target falls from NT$5,850 to NT$4,500. 2027E EPS drops from 225 to 173, and the 26x multiple holds. The distance from the close to the target widens from -14.5% to -32.4%.
| NT$100M; EPS in NT$億元,EPS 為元 | 2025A | 2026E ◆ | 2027E ◆ |
|---|---|---|---|
| Revenue營業收入 | 611.48 | 602 | 660 |
| Gross margin毛利率 | 50.37% | 45.9% | 47.0% |
| EPS | 159.46 | 159 | 173 |
| Consensus EPS (FactSet, 10-05)共識 EPS(FactSet,10-05) | — | 187.88 | 207.04 |
2026E = January to September actual plus a Q4 estimate (revenue NT$15.3bn, EPS 37). Q3 actuals are from the company call deck (unaudited).2026E 欄=1 至 9 月實績,加上第 4 季估計(營收 153 億元、EPS 37 元)。第 3 季實績取自公司法說簡報(未經會計師查核)。
| NT$100M; EPS and TP in NT$億元;EPS、目標價為元 | After調整後 | Before調整前 | Change差異 | Consensus (FactSet 10-05, before the call)市場共識(FactSet 10-05,法說前) | After vs consensus調整後對共識 |
|---|---|---|---|---|---|
| 2026E revenue2026E 營收 | 602 | 637 | -5.5% | 672.6 | -10.5% |
| 2026E gross margin2026E 毛利率 | 45.9% | 50.1% | -4.2pp | — | — |
| 2026E EPS2026E EPS | 159 | 195 | -18.5% | 187.88 | -15.4% |
| 2027E revenue2027E 營收 | 660 | 695 | -5.0% | 732.1 | -9.8% |
| 2027E gross margin2027E 毛利率 | 47.0% | 51.0% | -4.0pp | — | — |
| 2027E EPS2027E EPS | 173 | 225 | -23.1% | 207.04 | -16.4% |
| Target price目標價 | 4,500 | 5,850 | -23.1% | 5,300 (median) | -15.1% |
| 3Q262026 第 3 季 | Actual (company deck)實際數(公司簡報) | This analysis's estimate本研究前估 | Gap差異 |
|---|---|---|---|
| Revenue (NT$100M)營收(億元) | 156.51 | 168 | -6.8% |
| Gross margin毛利率 | 42.21% | 50% | -7.8pp |
| EPS (NT$) | 39.62 | 55 | -28.0% |
All three lines missed. Operating margin was 30.25% (operating income NT$4.735bn). Non-operating income was NT$1.357bn, and the company deck does not break it down.
No citable Q3 consensus was obtained, so there is no consensus column. The deck is unaudited.
三項全部低於前估。營業利益率 30.25%(營業利益 47.35 億元)。業外收入 13.57 億元,公司簡報沒有拆分組成。
第 3 季沒有取得可引用的共識,所以不列共識欄。簡報未經會計師查核。
How is Q4 estimated? January to September revenue is NT$44.86bn. The company said October is about the same as September (NT$5.779bn), so October is about NT$5.8bn.
It also said November will decline, and this analysis assumes December stays low. That puts Q4 revenue at about NT$15.3bn and 2026E revenue at about NT$60.2bn.
Q4 gross margin is set at about 43%, close to Q3's 42.21%.
Operating expenses of about NT$1.87bn, non-operating income of about NT$1.0bn and tax of 15% give Q4 EPS of about 37 (this analysis's calculation).
第 4 季怎麼估?1 至 9 月累計營收 448.6 億元。公司說 10 月動能與 9 月(57.79 億元)相當,所以 10 月約 58 億元。公司也說 11 月會下滑,本研究假設 12 月也維持低檔。這樣第 4 季營收約 153 億元,全年約 602 億元。第 4 季毛利率估約 43%,接近第 3 季的 42.21%。費用約 18.7 億元、業外約 10 億元、稅率 15%,得出第 4 季 EPS 約 37 元(本研究計算)。
Target price = 2027E EPS 173 × 26x PER = 4,498, rounded to NT$4,500 (6 months).
The target moved because earnings moved: 2027E EPS fell from 225 to 173. The 26x multiple was held, so the multiple did not move the target.
目標價 = 2027E EPS 173 元 × 26 倍 PER = 4,498,取整 4,500 元(6 個月)。這次目標價下修,是因為獲利(EPS)這個引擎動了:2027E EPS 從 225 元降到 173 元。倍數 26 倍維持不變,所以不是倍數造成的。
| Scenario情境 | Prob.機率 ◆ | 2027E EPS × PER2027E EPS × 倍數 | Price (vs close)價格(對現價) |
|---|---|---|---|
| Bear空方 | 25% | 150 × 18 | 2,700 -59.5% |
| Base基準 | 50% | 173 × 26 | 4,500 -32.4% (TP) |
| Bull多方 | 25% | 200 × 32 | 6,400 -3.9% |
Snapshot in one sentence: the close (6,660) is 25.7% above the FactSet target-price median (5,300). It is 6.9% above the highest verified foreign-broker target (Goldman Sachs, 6,231, 07-01).
快照重點,一句話:現價(6,660)比 FactSet 目標價中位數(5,300)高 25.7%,比已驗證的最高外資目標價(高盛,6,231,07-01)高 6.9%。
| NT$100M except per-share (NT$)億元,每股例外(元) | 2023A | 2024A | 2025A | 2026E ◆ | 2027E ◆ |
|---|---|---|---|---|---|
| Revenue營業收入 | 488.42 | 594.58 | 611.48 | 602 | 660 |
| Revenue YoY營收YoY | — | +21.7% | +2.8% | -1.6% | +9.6% |
| Gross margin毛利率 | 48.53% | 52.41% | 50.37% | 45.9% | 47.0% |
| Net income稅後純益 | 179.08 | 259.15 | 212.82 | 208 | 226 |
| EPS (NT$)EPS(元) | 134.18 | 194.17 | 159.46 | 159 | 173 |
| This analysis vs consensus (EPS)本研究 vs 共識(EPS) | — | — | — | -15.4% | -16.4% |
Share count: about 130.8M shares (net income NT$5.182bn divided by EPS 39.62 in the company deck). 2026E: January to September actual EPS 121.98 plus Q4E 37 gives 159.
2027E: revenue 660, gross margin 47.0%, operating expenses 12% of revenue, operating income 231. Non-operating income is 45, tax 18%, net income 226, and EPS 173.
Consensus (FactSet, 18 analysts via 鉅亨, 2026-10-05, before the call): 2026E EPS 187.88, 2027E EPS 207.04, 2028E EPS 239.29 (high 341.95). The target-price median is NT$5,300.
This analysis's 2026E EPS of 159 is 15.4% below the consensus, and 2027E EPS of 173 is 16.4% below. The consensus predates the call, so it should move.
The target of NT$4,500 is 15.1% below the consensus median and 32.4% below the close.
Revenue consensus (FactSet, before the call): 2026E median NT$67.26bn (mean 66.77, range 62.21 to 73.21); 2027E median NT$73.21bn (range 67.80 to 95.01).
This analysis's 2026E revenue of NT$60.2bn and 2027E revenue of NT$66.0bn are 10.5% and 9.8% below those medians.
股本基礎:約 1.308 億股(公司簡報淨利 51.82 億元除以 EPS 39.62)。2026E:1 至 9 月實績 EPS 121.98,加第 4 季估 37,得 159。
2027E:營收 660、毛利率 47.0%、費用占營收 12%、營業利益 231、業外 45、稅率 18%、淨利 226、EPS 173。
共識(FactSet,18 位分析師經鉅亨網轉載,2026-10-05,法說前):2026E EPS 187.88、2027E EPS 207.04、2028E EPS 239.29(最高 341.95)。目標價中位數 5,300 元。
本研究 2026E EPS 159 元比共識低 15.4%,2027E EPS 173 元比共識低 16.4%。這份共識在法說前取得,之後應該會下調。目標價 4,500 元比共識中位數低 15.1%,比現價低 32.4%。
營收共識(FactSet,法說前):2026E 中位數 672.6 億元(平均 667.7,範圍 622.1 至 732.1);2027E 中位數 732.1 億元(範圍 678.0 至 950.1)。
本研究的 2026E 營收 602 億元與 2027E 營收 660 億元,分別比各自的共識中位數低 10.5% 與 9.8%。
2027E EPS of NT$173 times a 26x PER gives 4,498, rounded to NT$4,500 (previous NT$5,850). The EPS engine moved; the 26x multiple was held. Cross-check: TP 4,500 implies a PBR of about 3.0x, against the close's 4.5x.
2027E EPS 173元 × 26倍PER = 4,498,取整 4,500元(前次 5,850元)。移動的是獲利(EPS)引擎,倍數 26 倍維持不變。交叉檢核:目標價4,500對應PBR約3.0倍(收盤4.5倍)。
◆ Anchor reconciliation: the probability-weighted scenario value is NT$4,525 — within 0.6% of the target price. The canonical anchor stays the base-case formula (173×26=4,498, rounded to 4,500); the weighted figure agrees closely enough that there is no need to argue for one over the other.
◆ 錨定調節:機率加權情境值為4,525元 — 與目標價差距在0.6%以內。正式錨點仍以基準情境公式(173×26=4,498,取整4,500)為準;加權值與其高度一致,無需擇一辯護。
The company does not disclose CPO segment revenue. The table below is this analysis's assumption set, laid open so NT$173 can be audited — not a disclosed figure.
公司不揭露 CPO 分部營收。下表是本研究的假設組,攤開來讓 173 元可以被稽核 — 不是揭露數字。
| Where the revenue comes from (NT$100M)營收來自哪裡(億元) | 2026E | 2027E | Δ | Assumption假設依據 |
|---|---|---|---|---|
| Phone lens core (incl. variable-aperture mix)手機鏡頭本業(含可變光圈mix) | ≈602 | ≈646 | +44 | Units flat, ASP/mix +7% (variable aperture goes full-year + coverage widens) — not unit growth出貨量持平、ASP/mix +7%(可變光圈進入全年+覆蓋擴大)— 非量成長 |
| CPO / optical interconnect (FA→FAU)CPO/光通訊(FA→FAU) | ≈0 | ≈14 | +14 | Mass production mid-2027, half a year of ramp only; 2.1% of revenue = midpoint of the base case's 1–3%2027年中量產、只認半年爬坡;占營收2.1%=基準情境1–3%的中點 |
| Total合計 | 602 | 660 | +58 |
On core-business economics, roughly every NT$460M of revenue adds about NT$1 of EPS.
The inputs are an operating margin of 35%, tax of 18% and 130.8M shares. Non-operating income is excluded, because interest on the NT$118.5bn cash pile and FX do not scale with CPO revenue.
Three consequences follow. They are arithmetic, not opinion.
換算基準:大立光每多賣多少錢,EPS 才會增加 1 元?
扣掉營業成本與稅(營益率 35%、稅率 18%、股數 1.308 億股;業外不計 — 因為 1,184 億現金的利息與匯兌不會隨 CPO 營收成長):大約每多賣 4.6 億元,EPS 才多 1 元。這是純粹的數學,不是意見。
算式結果一 · 2027 年 CPO 根本賺不到什麼錢
預估 CPO 只能貢獻 14 億元營收,換算下來 EPS 只增加約 3 元。相較於整年預估賺 173 元,這 3 元只占 1.7%,對獲利幾乎沒有影響。這就是本研究跟市場樂觀派最大的分歧點。
算式結果二 · 要讓 CPO 顯著貢獻獲利,需要多大的營收?
如果要讓 CPO 貢獻 10% 的 EPS(增加 17.3 元),CPO 營收必須衝到 79 億元,相當於占全公司總營收的 12%。但保守派認為到 2028 年 CPO 也才占 1–2% — 要達到 12% 幾乎是天方夜譚。
算式結果三 · 從現價 6,660 元反推,市場的要求還算誇張嗎?
現價 6,660 元要合理(沿用 09-02 的 28.4 倍本益比),2028 年 EPS 約要 235 元。從 2027 年的 173 元到 235 元(+62 元),營收約要多出 280 億元、年增約 +42%。大立光過去三年最好的一年是 +21.7%,所以這個要求約是歷史最佳的兩倍。10-07 估計下修前,同樣的算式只要約 241 元、年增約 +10%;2027E 降到 173 元後,這個論點重新成立。
Nomura's ruler (10-06): Nomura's 10-06 report puts CPO and FAU (the small part that aligns optical fibre to the chip) into an earnings model for the first time, and it gives a ruler: each extra million FAU units is worth about NT$10 of EPS. At this page's rule of about NT$0.46bn of revenue per NT$1 of EPS, NT$10 of EPS is about NT$4.6bn of revenue, so each million units is worth about NT$4.6bn (this analysis's calculation). The company gave no unit count or order value on the 10-08 call, so the ruler has nothing to test yet; use it when one arrives. Nomura puts CPO and FAU at about 18% of 2028 EPS, and that share is already priced into its NT$8,300 target. Until the company gives an order value or a unit count, the 18% is an assumption, not a fact.
野村的尺(10-06):野村 10-06 的報告第一次把 CPO 和 FAU(把光纖對準晶片的小零件)放進獲利模型,並給了一把尺:每多賣 100 萬個 FAU,EPS 約多 10 元。用本研究的換算(每約 4.6 億元營收約等於 1 元 EPS),10 元 EPS 約等於 46 億元營收,也就是每 100 萬個約 46 億元(本研究計算)。10-08 法說會公司沒有講出單位數或訂單金額,所以這把尺暫時派不上用場;等數字出現再用。野村估計 CPO 與 FAU 約占 2028 年 EPS 的 18%,這個比例已經算進它的 8,300 元目標價。公司沒有給出訂單金額或單位數之前,這 18% 是假設,不是事實。
2026E at 45.9%: January to September gross profit is NT$21.04bn on revenue NT$44.86bn (46.90%).
Q4E revenue of NT$15.3bn at 43% adds NT$6.58bn, so the full year is NT$27.62bn on NT$60.16bn, or 45.9%. Q3 was 42.21%, the low so far.
If Q4 falls to 41%, the full year is 45.4% and 2026E EPS is about 157.
2027E at 47.0%: gross profit of NT$31.02bn is NT$3.39bn more than 2026E on NT$5.8bn more revenue.
The added revenue must earn a 58% gross margin. This is the most optimistic assumption in the model.
If the added revenue earns only the 2026E average of 45.9%, the full-year margin is 45.9% and EPS falls from 173 to about 168. If the margin stays at Q3's 42.2% all year, EPS is about 153.
The 47.0% assumes yield partly recovers; the green-power cost is treated as structural, so margin does not return to 50%.
這一段是在做財務模型的壓力測試 — 拆解預測的毛利率合不合理,以及如果沒達標,EPS 會少掉多少。
1 · 2026 年預估 45.9%:第 3 季已是低點
2 · 2027 年預估 47.0%:這仍是整個模型最樂觀的假設
3 · 怎麼驗證?2027 年 1 月的第 4 季法說會。毛利率回到 45% 以上,代表良率真的回升;低於 42%,基準情境再下修。這兩條是本研究自己設的門檻,不是公司的數字。
The bear case in the scenario table (NT$2,700) stacks three bad things together. These tests do not. Each moves one variable, so the reader can see which one actually matters.
情境表的空方情境(2,700)是三件壞事疊加。以下三個測試不是。每個只動一個變數,讓讀者看清楚哪一個才真的有份量。
2027 CPO revenue goes from NT$1.4bn to zero, so EPS falls by 3 to 170. Times 26x gives NT$4,420, just 1.8% below the TP.
A CPO delay on its own barely touches this analysis's target price. CPO is only about NT$3 of the 2027 EPS.
What it does hit is the multiple: a delay removes the narrative holding up 38x.
If the multiple compresses to 20x at the same time, the answer is NT$3,400. A CPO delay is a multiple event, not an earnings event. This is the most important sentence in this box.
2027 年 CPO 貢獻從 14 億歸零,EPS 少 3 元,變成 170。乘上 26 倍是 4,420 元,只比 TP 低 1.8%。
單獨的 CPO 延誤幾乎不影響本研究的目標價,因為 CPO 在 2027 年 EPS 裡只有約 3 元。真正被打到的是倍數:延誤會拿掉支撐 38 倍的敘事。
若倍數同時壓到 20 倍,答案是 3,400 元。CPO 延誤是倍數事件,不是盈餘事件。這是本框裡最重要的一句。
The single-quarter FX loss of NT$4.22bn in 2025 Q2 ate 80% of that quarter's profit and left EPS at 7.73 ✓.
A repeat of the same size would cut 2027 after-tax profit by NT$4.2bn, or EPS by 32, to 141. Times 26x gives NT$3,670.
Watch the signal shape: an FX loss hits after-tax profit, not gross margin. The market will comfort itself with "the core business is fine".
That comfort does not hold. About 16% of the pre-tax profit in the NT$173 estimate is non-operating income.
What to watch: the slope of USDTWD's monthly line. Also watch the central bank's language after each board meeting.
2025 Q2 單季匯損 42.2 億,吃掉單季獲利八成,EPS 只剩 7.73 ✓。同樣大小的匯損再來一次,2027 年稅後少 42 億,也就是 EPS 少 32 元,變成 141。乘上 26 倍是 3,670 元。
注意訊號的形態:匯損打的是稅後,不是毛利。市場會用「本業沒事」安慰自己,但這個安慰不成立。因為 173 元的估計裡,約 16% 的稅前獲利來自業外。
要看的指標:USDTWD 月線斜率、央行理監事會後的措辭。
The ASP/mix gain halves from +7% to +3.5%. 2027 core revenue falls from 646 to 623, and total revenue to 637 (NT$2.3bn lower).
Revenue is NT$2.3bn lower. The lost revenue carries a 58% incremental gross margin, the same basis as the check above.
With tax of 18% and 130.8M shares, after-tax profit falls NT$1.09bn. That is EPS −8.3, to about 165.
Times 26x gives NT$4,290.
This test assumed variable aperture on the Pro Max only. On 09-10 both the Pro and the Pro Max got it, so this bad case did not happen. The test stays as a downside reference if the 2027 spec bonus disappoints.
ASP/mix 增益從 +7% 砍半到 +3.5%。2027 年本業營收從 646 降到 623,合計 637(少 23 億)。
以增量毛利率 58%(與上方毛利率驗算同一口徑)、稅率 18%、1.308 億股推算,稅後少 10.9 億,也就是 EPS 少 8.3 元,約 165 元。乘上 26 倍是 4,290 元。
這個測試的前提是可變光圈只上 Pro Max。09-10 的結果是 Pro 與 Pro Max 都有,這個壞情境沒有發生。測試留在這裡,當作 2027 年規格紅利落空時的下檔參考。
Each single-variable test lands the target price at NT$4,420, NT$3,670 and NT$4,290. If the CPO delay also compresses the multiple, it is NT$3,400.
All of them are still below the NT$6,660 close, by 33.6% to 44.9% (3,400 is 48.9% below). So this analysis's "avoid" conclusion does not depend on any one bad thing happening.
That is where the negative asymmetry comes from. The good news is already in the price, and the bad news is not.
三個單變數測試各自把目標價打到 4,420、3,670 和 4,290。CPO 延誤若同時壓縮倍數,則到 3,400。
全部仍低於收盤 6,660,低 33.6% 到 44.9%(3,400 低 48.9%)。也就是說:本研究的「迴避」結論不依賴任何一個壞消息發生。
這就是負不對稱的來源:好消息已經在價內,壞消息還沒有。
| What to watch觀察 | Healthy健康 | Overdrawn透支 | Now現況 |
|---|---|---|---|
| Monthly revenue vs the stock月營收 vs 股價 | Monthly revenue YoY turns positive and accelerates, stock moves with it月營收YoY轉正且加速、股價同向 | Stock keeps making highs while monthly revenue YoY is still negative股價續創高但月營收YoY仍負 | watch觀察 Revenue YoY still negative (Jul −10.66%, Aug −16.23%, Sep −7.31%), but the stock is 16.7% below its 7,995 high and no longer making highs月營收YoY仍為負(7月−10.66%、8月−16.23%、9月−7.31%),但股價低於7,995高點16.7%,已不再續創高 ✓ |
| Where gross margin comes from毛利率的來源 | 50%+ and the company attributes it to yield50%+且公司歸因良率改善 | Margin recovers on mix or FX rather than yield; or margin stays below 50% and the company points to a structural cost毛利率回升但靠mix/匯率而非良率;或毛利率低於50%,且公司歸因為結構性成本 | OVERDRAWN透支 Q3 margin fell to 42.21%, the fourth straight quarter below 50%. The company named two causes: green-power purchases, which are a structural cost, and yield. Green-power prices for 2027 are set, so they can pass into prices in 2028 at the earliest.第 3 季毛利率降到 42.21%,連四季低於 50%。公司點名兩個原因:綠電購買(結構性成本)和良率。2027 年綠電價格已定,最快 2028 年才能轉進售價。 ✓ 已查證verified |
| CPO milestone languageCPO里程碑用詞 | "on schedule," "samples shipped," "line installed"「如期」「已送樣」「已架設」 | Shifts to "under evaluation," "timeline adjusted"改口為「評估中」「時程調整」 | healthy健康 the company said FA certification passed in September, the price is agreed, the pilot line is finished and capacity will be built by mid-2027. Several outlets reported it. Certification and price are not an order value.公司說 FA 認證 9 月已通過、價格已談定、試產線已完工、產能 2027 年中建立。多家媒體都有報導。認證與價格不是訂單金額。 ✓ 已查證verified |
| Shareholder base籌碼結構 | Foreign investors buying back, local funds still buying外資回補、投信續買 | Foreign investors keep selling, retail and margin buyers take the other side外資續賣、由散戶/融資接手 | OVERDRAWN透支 34.15% (2025-05) → 27.30% (08-28) → 24.63% (10-06); foreign investors net bought on only 2 of the 14 sessions from 09-15 to 10-06, net selling about 2,583 board-lots. Who took the other side was not checked.外資持股 34.15%(2025-05)→27.30%(08-28)→24.63%(10-06);09-15 到 10-06 十四個交易日中外資只有 2 天買超,合計賣超約 2,583 張。誰在接手沒有查。 ✓ Yahoo 籌碼頁 |
| Sell-side models vs the price賣方模型 vs 價格 | A broker's target catches up to the price with an auditable model behind it有券商TP追上現價並附可審模型 | Median target stays far below the price; upgrades follow the price, not a modelTP中位仍遠低於現價、上調只跟價不跟模型 | watch觀察 median 5,300 (10-05) vs close 6,660; highest verified 6,231 (07-01)中位5,300(10-05) vs 收盤6,660;已驗證最高6,231(07-01) |
The rule, mechanized rather than felt: any two cells sitting in the "Overdrawn" column counts as a tripwire, even in a month when revenue looks good. Two cells are red now (where gross margin comes from, and shareholder base), so the tripwire is triggered again; on 10-07 only one was red and it was not. The close is 48.0% above the target price, and the probability-weighted value (4,525) is 32.1% below the close. The rule runs in reverse too: two cells turning back to "Healthy" means this view is due for re-examination.規則,機制化而非憑感覺:任何兩格落在「透支」欄=視同絆線,即使當月營收好看。目前有兩格(毛利率的來源、籌碼)在「透支」欄,所以絆線重新觸發;10-07 只有一格,當時沒有觸發。現價比目標價高 48.0%,機率加權值 4,525 比現價低 32.1%。反向也成立:兩格同時轉回「健康」=本觀點必須重審。
| Scenario情境 | Prob.機率 ◆ | Key assumptions關鍵假設 | 2027E EPS | PER | Scenario price情境價 |
|---|---|---|---|---|---|
| Bear空方 | 25% | Yield does not recover, gross margin 44%; revenue 630; CPO slips to 2028良率沒有回升、毛利率44%;營收630;CPO滑至2028 | 150 | 18× | 2,700 |
| Base基準 | 50% | Yield partly recovers, gross margin 47% (the green-power cost stays); revenue 660; CPO small-volume mid-2027 (about 2% of revenue); FX stable良率部分回升、毛利率47%(綠電成本屬結構性,不回到50%以上);營收660;CPO 2027年中小量產(約占營收2%);匯率平穩 | 173 | 26× | 4,500 =TP |
| Bull多方 | 25% | Yield fixed, gross margin back to 50%; CPO ahead of schedule with a disclosed order magnitude (Rubin Ultra-tier customer confirmed); 2028 visibility supports a story multiple良率修好、毛利率回到50%;CPO提前且訂單量級公告(Rubin Ultra級客戶確認);2028能見度支撐本夢比 | 200 | 32× | 6,400 |
From the close (NT$6,660), the base TP is -32.4% away, the bear scenario -59.5% and the bull scenario -3.9%.
Even the bull scenario (6,400) is below today's close. So the downside is larger than the upside in every scenario. The probability-weighted value, 4,525, is 32.1% below the close.
On 10-07 the bull case was 19.2% above the price. The estimate cut moved it below.
For the stock to double (to about 13,320), 2028 EPS would need to reach roughly NT$440 at 30x.
That means CPO contributing beyond even Citi's bull case. The market would also have to award an optical-interconnect multiple for good.
This is beyond management's own cautious wording ("at the earliest mid-2027"). It is also beyond every published sell-side model.
現價 6,660 元。到基準目標價是 -32.4%,到空方情境是 -59.5%,到多方情境是 -3.9%。
連多方情境(6,400)都比現價低,三個情境都在現價之下。機率加權值 4,525 元比現價低 32.1%。10-07 時多方情境比價格高 19.2%,估計下修後,它落到現價之下。
股價要從現價翻倍(約 13,320),需要 2028 EPS 達約 440 元,再乘 30 倍。這代表 CPO 貢獻超越 Citi 的藍天,且市場永久給光通訊倍數。這超出管理層自己的說法(「最快 2027 年中放量」的謹慎措辭),也超出所有已公布的賣方模型。
| 2027E EPS \ PER | 18× (band floor)18×(歷史帶下緣) | 20× (band ceiling)20×(歷史帶上緣) | 26× (TP multiple)26×(TP倍數) | 32× (story multiple)32×(本夢比) |
|---|---|---|---|---|
| 150 (bear)(空方) | 2,700 | 3,000 | 3,900 | 4,800 |
| 173 (base)(基準) | 3,114 | 3,460 | 4,500 = TP | 5,536 |
| 200 (bull)(多方) | 3,600 | 4,000 | 5,200 | 6,400 |
Solid highlight: the TP cell (173 times 26 is 4,498, shown as 4,500). Dashed outline: the cell the close most closely implies.
At NT$6,660, the close divided by 26x is an EPS of about 256, above the bull EPS of 200. The close divided by 200 is about 33.3x, above even the story multiple of 32x.
The close sits 4.1% above the bull-EPS cell at the story multiple (6,400). On 10-07 it sat next to the bull-EPS cell at the TP multiple. The market now needs more than the bull case on EPS and the multiple together.
實心標色:TP 所在格(173 乘 26 是 4,498,取整 4,500)。虛線框:現價最接近的格。
現價 6,660 元除以 26 倍,約等於 EPS 256,高於多方的 200。現價除以 200,約是 33.3 倍,連本夢比 32 倍都高。
現價比「多方 EPS 乘本夢比」(6,400)那一格高 4.1%。10-07 時現價靠近「多方 EPS 乘 TP 倍數」那一格。市場現在要的,比 EPS 與倍數同時達到多方情境還多。
一句話:第 3 季法說會已經開完,毛利率 42.21% 觸發了下檔門檻,所以基準情境重建。下一個關鍵日是 11 月 10 日前後公布的 10 月營收。
One line: the Q3 earnings call is done, and a gross margin of 42.21% triggered the downside bar, so the base case was rebuilt. The next key day is the October revenue release around 11-10.
法說回答了什麼:原本要聽的六件事
What the call answered: the six things we listened for
| Timing時間 | Event事件 | Threshold → reaction門檻 → 反應 ◆ | Status狀態 |
|---|---|---|---|
| 2026-09-10 (Taipei time)(台北時間) | Apple fall event: iPhone 18 Pro + foldable iPhone蘋果秋季發表會:iPhone 18 Pro+摺疊iPhone | Variable aperture across the full Pro lineup = matches expectation (already priced in); explicit rollout to the 2027 standard lineup → review upgrading 2027E; confined to Pro Max only → mix contribution shrinks, review downgrading 2027E可變光圈覆蓋全Pro系列=符合預期(已定價);明示下放2027標準版→2027E上修檢討;僅Pro Max獨占→mix貢獻縮水、2027E下修 | resolved: Pro and Pro Max both have it = as expected. Apple did not name suppliers; Largan's share stays unverified.已揭曉:Pro 與 Pro Max 都有=符合預期。蘋果沒有公布供應商,大立光份額仍未證實。 |
| 2026-09-05 / 10-05 | August and September monthly revenue8月、9月營收公告 | August ≥NT$5.5bn (this analysis's own threshold, not company guidance) → seasonal track confirmed; <NT$5.0bn → review downgrading 3Q26E8月≥55億(本研究門檻,非公司數字)→旺季軌道確認;<50億→3Q26E下修 | resolved: Aug 50.12 (missed 55, 0.12 above the 50 line); Sep 57.79 (cleared 55); Q3 total 156.51, 6.8% below the 168 Q3E已揭曉:8月 50.12 億(未達 55 億,只比 50 億線高 0.12 億);9月 57.79 億(達 55 億);第 3 季合計 156.51 億,比 3Q26E 的 168 億低 6.8% |
| ~2026-09-30 | CPO pilot line completes (company-guided)CPO試產線完成架設(公司預告) | On schedule = neutral (already priced in); delayed → narrative damaged如期=中性(已定價);延誤→敘事受創 | resolved: on schedule已結案:如期 On 10-08 the company said the FA pilot line is finished and equipment is installed. FA certification passed in September and the price is agreed. This is neutral and already priced in. Certification and price are not an order value, and the failure condition (annualised orders above NT$5bn) is unchanged.公司 10-08 說 FA 試產線已完工、設備已裝好。FA 認證 9 月通過,價格已談定。這屬中性,股價已反映。認證與價格不是訂單金額,失效條件(年化訂單超過 50 億元)不變。 |
| 2026-10-08 (online)(線上) | Q3 earnings + callQ3財報+法說 | GM ≥52% and EPS ≥58 → yield issues resolved, review upgrading; GM <48% → new-model yield drag confirmed, base case in doubt毛利率≥52%且EPS≥58→良率過關、上修檢討;毛利率<48%→新機良率拖累、基準情境存疑 | resolved: downside hit已揭曉:下檔觸發 Gross margin 42.21%, below the 48% bar; EPS 39.62, below the 58 bar. Upgrade bar not met. The pre-committed reaction ran: base case rebuilt, 2027E EPS 225 to 173, TP 5,850 to 4,500.毛利率 42.21%,低於 48% 門檻;EPS 39.62,低於 58 門檻。上修門檻未達。事先寫好的反應已執行:基準情境重建,2027E EPS 225 降到 173,目標價 5,850 降到 4,500。 |
| 2026-11-10 (around)前後 | October monthly revenue10月營收公告 | About NT$5.8bn = matches the company's statement (this analysis's own bar, not company guidance); clearly below NT$5.5bn → review downgrading 4Q26E約58億=符合公司說法(本研究門檻,非公司數字);明顯低於55億→4Q26E下修檢討 | scheduled已排定 |
| 2026-12 (around)前後 | November monthly revenue11月營收公告 | The company said it will decline (this analysis's own bar): a clearly wider YoY drop → review downgrading 4Q26E公司說會下滑(本研究門檻):YoY 降幅明顯擴大→4Q26E 下修檢討 | scheduled已排定 |
| 2026 Q4 | CPO pilot-line yield / customer qualification progressCPO試產良率/客戶驗證進度 | Passes → 2027 mass-production probability raised; fails → timeline slips, the bull-case valuation loses its anchor通過→2027量產機率上調;未過→時程滑動、藍天派估值失錨 | speculative推測 |
| 2027-01 | Q4 earnings callQ4 法說 | Gross margin back above 45% = yield recovering (this analysis's own bar); below 42% → base case cut again毛利率回到45%以上=良率回升(本研究門檻);低於42%→基準情境再下修 | scheduled已排定 |
| 2027 mid-year年中 | CPO mass production (company's own "at the earliest" language)CPO量產(公司說法「最快」) | Actual mass production + disclosed order magnitude → the second curve begins to be real, rebuild the model實際量產+公告訂單量級→第二曲線開始兌現,重建模型 | speculative推測 |
Scored every month alongside the overdraft monitor in the numbers section.
與〈數字〉章的透支訊號監測表逐月同時打分。
這一段講的是監控與評估這個觀點的「紀律 SOP」。為了避免自己主觀硬撐,事前先把「檢驗門檻」與「作廢紅線」通通寫死。
1 · 打分門檻是「重審信號」,不是「無腦加碼」
每月針對 T8 的觀察項目打分。就算某項超乎預期、觸發了「上修檢討」門檻,也只會重新計算模型,不會直接自動買進 — 門檻是提醒你「該重新評估了」,不是進場訊號。
2 · 只要透支訊號轉紅,利多再好都沒用
如果透支訊號監測表裡任兩格亮紅燈,這是最高等級的絆線警訊,優先權高於一切。當月消息再利多,也必須保持戒備。
3 · 錯了就砍,不修修補補
一旦事前設定的「失效條件」被觸發,代表核心邏輯已經崩塌 — 直接把這份報告作廢重寫,不硬找藉口、不做部分微調來自欺欺人。
4 · 兩個門檻接近時,要分開打分
兩個門檻接近揭曉時,打分必須把兩件事分開獨立評估,不能混在一起憑「整體感覺」給分。這次的例子:09-10 蘋果發表會符合預期,09-05 的 8 月營收沒有達到門檻,兩項分開記。
| If not holding未持有 | ◆ Do not chase. Wait for the entry zone (NT$3,300–3,800), or wait for a formal CPO order-magnitude announcement before rebuilding the model.不追價。等進場區(3,300–3,800 元),或等CPO訂單量級正式公告後重建模型再評。 |
| If holding若已持有 | ◆ Default to scaling out in tranches. The rule for keeping a core position needed two things at once: variable-aperture coverage better than expected, and gross margin ≥52% at the October call. Neither happened (09-10 met expectations; Q3 gross margin was 42.21%), so the exception for a core position is gone and the default stands.預設分批減碼。原本續抱核心倉要同時達成兩項:可變光圈覆蓋優於預期,以及 10 月法說毛利率≥52%。兩項都沒有達成(09-10 只符合預期;第 3 季毛利率是 42.21%),所以核心倉續抱的例外取消,預設不變。 |
| Entry zone (one ruler)進場區(一把尺) | ◆ First tranche is priced only. NT$3,300–3,800 (≈2027E 19–22× on EPS 173, at or below 15% under the base TP of 4,500): entering that band buys the first tranche, with no evidence gate. The close, 6,660, is 75.3% above the top of the band. Second tranche is evidence only. Only a formal CPO mass-production order amount adds to the position. The other evidence, 3Q26 gross margin ≥52%, failed on 10-08 (42.21%), so there is no second tranche now. The tripwire overrides every tranche: two cells red on the overdraft monitor, or an invalidation condition firing → stop all tranches regardless of price.第一批只看價格。3,300–3,800 元(2027E EPS 173 的 19–22 倍,約在基準 TP 4,500 的 −15% 以下):進入這個區間即建第一筆,不設證據關卡。現價 6,660 元比區間上緣高 75.3%。第二批只認證據。只有 CPO 量產訂單金額正式公告,才會加碼。另一項證據,3Q26 法說毛利率 ≥52%,10-08 已落空(42.21%),所以目前沒有第二批。絆線凌駕所有批次:透支監測表任兩格轉紅、或失效條件觸發 → 不論價格,所有批次先停。 |
| Why not more aggressive (a short)為何不更激進(放空) | ◆ A four-digit-priced stock with only ~131M shares outstanding, daily traded value in the NT$10bn range, CPO news flow still in an acceleration phase, a price that fell only 2.70% on the 10-08 call despite the margin miss, and no low-cost TW borrow environment — negative asymmetry is a reason not to buy, not a reason to short.千金股在外流通僅1.31億股、日成交值百億級、CPO新聞流仍在加速期、10-08 法說毛利率不如預期、股價卻只跌 2.70%、台股無低成本借券環境 — 負不對稱是「不買」的理由,不構成「放空」的期望值。 |
| Invalidation失效條件 | ◆ (1) A formal CPO mass-production order (named customer/amount) is disclosed with annualized contribution >NT$5bn → the 2028 valuation center shifts up, this view is due for review. (2) Resolved on 10-08: the bar "3Q26 EPS ≥65 and gross margin ≥53%" was missed (EPS 39.62, gross margin 42.21%), so it did not fire.(1) CPO量產訂單客戶/金額正式公告且年化貢獻>50億元→2028中樞上移,本觀點重審;(2) 已於 10-08 結案:「3Q26 EPS≥65且毛利率≥53%」未達(EPS 39.62、毛利率 42.21%),沒有觸發。 |
Append-only, and reserved for material events — earnings, guidance changes, a catalyst resolving, or a full /thesis-update refresh. Drafting and layout work is not recorded here.附加式紀錄,且只記重大事件 — 財報、財測變動、催化劑揭曉,或一次完整的 /thesis-update 更新。撰稿與排版過程不列入。
一句話:第 3 季毛利率只有 42.21%,低於我們事先設定的 48% 下檔門檻,所以基準情境重建,目標價從 5,850 元降到 4,500 元。觀點迴避、26 倍的倍數、CPO 的失效條件都沒有變。
One line: Q3 gross margin was only 42.21%, below the 48% downside bar we set in advance.
So the base case was rebuilt and the target price falls from NT$5,850 to NT$4,500. The avoid view, the 26x multiple and the CPO failure condition did not change.
1. 現象
2. 解讀
3. 調降
4. 決策
結論:觀點迴避(不變)|目標價 4,500 元(前次 5,850 元;EPS 引擎動了,倍數 26 倍沒動)|進場區 3,300–3,800 元(前次 4,300–5,000 元)|現價 6,660 元(10-08 收盤),比目標價高 48.0%。
Bottom line: view avoid (unchanged) | target NT$4,500 (previous 5,850). The EPS engine moved; the 26x multiple did not. | entry zone NT$3,300–3,800 (previous 4,300–5,000) | close 6,660 (10-08), 48.0% above the target.
◆ estimates, target price and view = judgment估計、目標價與觀點=判斷
| 位置與日期:原文Where and when: original wording |
|---|
| 頁首結論句(10-07):結論:維持迴避,目標價 5,850 元沒有改。 |
| 頁首一句話(10-07):一句話:10-07 收盤 6,845 元,比 09-02 的 7,810 元低 12.4%。第 3 季營收 156.51 億元,比我預估的 168 億元少 6.8%。觀點與目標價都沒有改,因為決定獲利預估的毛利率,要等 10-08 的法說會才知道。 |
| 頁首持有者段(10-07):已持有:維持預設,分批減碼到核心倉位。10-08 毛利率若至少 52%,核心倉可續抱。新資金:不買。進場區是 4,300–5,000 元,現價比上緣高 36.9%。「迴避」是不買,不是放空。 |
| 卡點四行 一句話(10-07):一句話:大立光是蘋果高階鏡頭的主力供應商之一,想再進 AI 光纖零件。它不是卡點,毛利很高,這次股價買的是新角色。 |
| 卡點四行 第 3 行(10-07):3. 利潤守不守得住:留在大立光。2025 年每賣 100 元,扣掉直接成本剩 50.4 元;最近四季剩 48.3 元(本研究推算)。同業通常只剩 20 到 30 元。 |
| 卡點四行 第 4 行(10-07):4. 已經反映:角色改變。12 個月內,股價相當於近四季每股獲利(EPS)188.02 元的倍數,從約 11 倍漲到 36 倍。但共識的 2026 年 EPS 只有 187.88 元,和近四季幾乎一樣。市場付的是「大立光也能做 AI 光纖零件」,不是鏡頭獲利變多。 |
| 數字節 一句話(10-07):一句話:目標價 5,850 元沒有改,因為 2027 年 EPS 225 元與 26 倍都沒動;變的是現價,所以距離從 -25.1% 縮到 -14.5%。 |
| 數字表 2026E 欄註(10-08 上午):* 2026E 欄還沒有代入第 3 季實績(代入後營收約 626、EPS 約 193),10-08 法說後重算。 |
| 第 4 季算式段(10-08 上午):第 4 季要有多少營收,全年數字才對得上?1 至 9 月累計 448.6 億元。要達到本研究 2026E 的 637 億元,第 4 季約需 188 億元。公司說 10 月動能與 9 月相當(57.79 億元)。如果 11、12 月也停在這個水準,第 4 季約 173 至 175 億元,全年約 622 億元。這個數字比本研究的 637 億元低,也比 FactSet 營收中位數 672.6 億元低。這是今天法說會要查的矛盾,本研究的估計要等法說會之後才重算(本研究計算)。 |
| 目標價句(10-07):目標價 = 2027E EPS 225 元 × 26 倍 PER = 5,850 元(6 個月)。這次沒有改:EPS 與倍數都沒動,所以沒有任何一個引擎移動。如果第 3 季營收缺口全部帶到 2027E(約 -2.6 元 EPS),目標價約 5,780 元,低 1.2%。 |
| 單位數學 結果三(10-07):現價 6,845 元要合理(沿用 09-02 的 28.4 倍本益比),2028 年 EPS 約要 241 元。從 2027 年的 225 元到 241 元(+16 元),營收約要多出 70 億元、年增約 +10%。大立光過去三年最好的一年是 +21.7%,所以這個要求沒有超出歷史。09-02 的 7,810 元需要 275 元、年增 +32%,那是歷史上沒發生過的;股價跌 12.4% 後,這個論點不再成立。 |
| 毛利率驗算 2026 年下半年(09-02):下半年挑戰 — 要讓全年達到 50.1%,下半年必須拉到 50.68%(比上半年高 1.3 個百分點)。完全取決於 iPhone 新機鏡頭的良率能不能順利提升。 |
| 毛利率驗算 2026 年萬一沒達標(09-02):萬一沒達標 — 下半年只維持上半年的 49.41%,全年 EPS 就從 195 元降到約 192 元 |
| 毛利率驗算 2027 年 51.0%(09-02):模型內建的超樂觀假設 — 要讓 2027 年毛利率到 51.0%,等於要求「新增的那段營收」毛利率高達 61%。這需要「可變光圈」和「CPO」兩大新業務都非常賺錢才辦得到 — 這是整個模型裡最樂觀的單一假設 |
| 毛利率驗算 2027 年回歸現實(09-02):回歸現實 — 如果新增業務的毛利率只跟公司平均差不多(51%),2027 年全年毛利率就降到 50.2%,EPS 從 225 元掉到約 222 元 |
| 毛利率驗算 怎麼驗證(09-02):3 · 怎麼驗證?T8 設定的「10 月法說會毛利率是否 ≥52%」就是在驗這一格 — 檢查這個超高毛利率的預測到底有沒有吹牛。 |
| 壓力測試 1(10-07):單獨的 CPO 延誤幾乎不影響本研究的目標價 — 因為本研究本來就沒把 CPO 放進 2027 年的 EPS。真正被打到的是倍數:延誤會拿掉支撐 36 倍的敘事。若倍數同時壓到 20 倍 = 4,440 元。CPO 延誤是倍數事件,不是盈餘事件 |
| 壓力測試 結論(10-07):三個單變數測試各自把目標價打到 5,018/5,642/5,772(CPO 延誤若同時壓縮倍數則到 4,440),區間 4,400–5,800 — 全部仍低於收盤 6,845(低 15.7%–26.7%;4,440 低 35.1%)。也就是說:本研究的「迴避」結論不依賴任何一個壞消息發生。這就是負不對稱的來源 — 好消息已經在價內,壞消息還沒有。 |
| 情境假設(空方)(10-07):iPhone 18銷售平淡/可變光圈2027年不下放標準版;台幣急升重演;CPO滑至2028 |
| 情境假設(基準)(10-07):新機規格紅利兌現、毛利率50–51%;CPO 2027年中小量產(占營收1–3%);匯率平穩 |
| 情境假設(多方)(10-07):可變光圈2027下放全系列;CPO提前且訂單量級公告(Rubin Ultra級客戶確認);2028能見度支撐本夢比 |
| 不對稱性檢查(10-07):現價 6,845 元。到基準目標價是 -14.5%,到空方情境是 -51.4%,到多方情境是 +19.2%。多方情境(8,160)比現價高 19.2%,空方情境比現價低 51.4%:往下的空間仍大於往上。 |
| 敏感度矩陣註(10-07):實心標色=TP所在格(225×26=5,850)。虛線框=現價最接近的格:現價6,845元÷26×≈EPS263(高於多方255),6,845÷255≈26.8×(略高於TP倍數26×)— 現價現在落在「多方EPS×TP倍數」(6,630)那一格附近 |
| 透支監測 毛利率的來源 現況(10-07):連三季<50%,10-08 法說驗 |
| 透支監測 毛利率的來源 透支欄定義(10-07):毛利率回升但靠mix/匯率而非良率 |
| 透支監測 CPO 里程碑 現況(10-07):公司說「第3季底試產」,尚無完成確認,10-08 法說驗 |
| 透支規則(10-07):規則,機制化而非憑感覺:任何兩格落在「透支」欄=視同絆線,即使當月營收好看。目前只有一格(籌碼)在「透支」欄,所以絆線沒有觸發;09-02 是兩格,當時已觸發。迴避現在靠的是價格與目標價的距離:現價比目標價高 17.0%,機率加權值 5,797.5 比現價低 15.3%。反向也成立:兩格同時轉回「健康」=本觀點必須重審。 |
| 催化劑區 一句話(10-08 上午):一句話:下一個關鍵日是 10-08 的第 3 季法說會;毛利率與每股盈餘兩個數字,會決定要不要重算模型。 |
| 催化劑區 下一個(10-08 上午):下一個:10-08 線上法說會,毛利率至少 52% 且 EPS 至少 58,才會讓我檢討上修;毛利率低於 48%,基準情境就存疑。 |
| 催化劑區 還沒確認(10-08 上午):還沒確認:CPO 試產線是否如期完成,10-05 的報導仍引述公司先前的說法。 |
| 催化劑區 小標(10-08 上午):今天法說要聽的六件事 |
| 催化劑區 第 1 件的結尾(10-08 上午):本研究自己對第 3 季 EPS 的估計是 55,所以結果約 55 代表符合本研究的估計,但不會啟動上修檢討。 |
| 操作框架 若已持有(10-07):預設分批減碼(將暴利了結至核心倉位)。續抱核心倉要同時達成兩項:可變光圈覆蓋優於預期,以及 10 月法說毛利率≥52%。第一項沒有達成(09-10 是符合預期,不是優於預期),所以預設不變。10-08 毛利率若 ≥52%,核心倉仍有續抱的理由。 |
| 操作框架 進場區(10-07):第一批只看價格。4,300–5,000 元(≈2027E 19–22 倍、基準 TP −15% 以下):進入這個區間即建第一筆,不設證據關卡。現價 6,845 元比區間上緣高 36.9%。第二批只認證據。CPO 量產訂單金額正式公告,或 3Q26 法說毛利率 ≥52% — 一項達標即加、兩項皆反不加。絆線凌駕所有批次:透支監測表任兩格轉紅、或失效條件觸發 → 不論價格,所有批次先停。 |
| 操作框架 為何不更激進(10-07):千金股在外流通僅1.31億股、日成交值百億級、CPO新聞流仍在加速期、10-08 法說會事件風險雙向、台股無低成本借券環境 — 負不對稱是「不買」的理由,不構成「放空」的期望值。 |
| 操作框架 失效條件(10-07):(1) CPO量產訂單客戶/金額正式公告且年化貢獻>50億元→2028中樞上移,本觀點重審;(2) 3Q26 EPS≥65且毛利率≥53%→本研究低估規格紅利,上修。 |
| 完整論證 姿態(10-07):姿態:跟盤面吵,不跟賣方吵。18 位分析師的 FactSet 目標價中位數 5,300 元(10-05)比收盤低 23%,連已驗證的最高外資目標價(高盛 6,231,07-01)也低 9%。本研究與賣方站在同一邊。這決定了這份報告的舉證責任:不需要證明賣方錯了,只需要說明盤面在為什麼付錢。 |
| 摘要 風險段(10-07):估值(倍數)與獲利(EPS)是兩回事 — 就算 2027 年真的賺了 225 元、EPS 一毛沒估錯,只要市場給的本益比沒有壓縮、繼續維持在約 30 倍(現價對 2027E 的倍數):225 × 30 = 6,750 元,仍幾乎等於現在的收盤價 |
| 完整論證「毛利率結構性下移」卡片(09-02):市場恐懼:毛利率連續三季跌破50%:4Q25 47.75% → 1Q26 49.4% → 2Q26 49.41% ✓。公司說法:良率是關鍵,逐步改善。獨立證據:H1毛利率年減4.77pp,本研究自行推算的近四季毛利率約48.3% ✓◆ 推算。本研究判斷:2026–27毛利率50–51%,回不到2024年52.4%之上。 |
| 論點全文 核心問題(09-02):核心問題 — 不管你信哪一派,現在的股價都已經按最高標準把夢算進去了:現價對應 2028 年預估獲利是 28–32 倍本益比,連最看好的報告算出來的目標價,也只比現價高一點點。 |
The superseded sentences are kept verbatim in Chinese, with markup removed; the English view carries no copy of them.
一句話:法說會前,這份報告補上七度購地的合計、野村 8,300 元目標價、營收共識與第 4 季算式,並新增六件要聽的事。觀點迴避、目標價 5,850 元與所有估計都沒有改,股價仍是 10-07 收盤 6,845 元,完整重算要等法說會之後。
One line: before the call, this report adds the seven-purchase land total, Nomura's NT$8,300 target, the revenue consensus and the Q4 arithmetic, plus six things to listen for. The avoid view, the NT$5,850 target and every estimate are unchanged, the price is still the 10-07 close of NT$6,845, and the full re-estimate follows the call.
結論:觀點迴避(不變)|目標價 5,850 元(不變)|現價 6,845 元(10-07 收盤,未更新)。
Bottom line: view avoid (unchanged) | target NT$5,850 (unchanged) | close 6,845 (10-07, not refreshed).
一句話:10-07 收盤 6,845 元,第 3 季營收 156.51 億元,比預估少 6.8%。觀點迴避與目標價 5,850 元都沒有改,毛利率要等 10-08 法說會。
One line: the 10-07 close was NT$6,845 and Q3 revenue NT$15.651bn, 6.8% below the estimate. The avoid view and the NT$5,850 target are unchanged; gross margin waits for the 10-08 call.
結論:觀點迴避(不變)|目標價 5,850 元(不變;EPS 與倍數都沒動)|進場區 4,300–5,000 元(不變)|現價 6,845 元,比目標價高 17.0%。
Bottom line: view avoid (unchanged) | target NT$5,850 (unchanged; neither EPS nor multiple moved) | entry zone NT$4,300–5,000 (unchanged) | close 6,845, 17.0% above the target.
| 位置與日期:原文Where and when: original wording |
|---|
| 摘要第 3 點(09-02):股價已經站上樂觀頂峰 — 現價對應 2028 年預估獲利高達 32.6 倍本益比;即便用最極端的 275 元 EPS 來算,依然 28.4 倍。代表股價已經把「CPO 必定大成功」的超高機率提前算進去了。 |
| 摘要風險段(09-02):只要市場給的本益比沒有壓縮、繼續維持在現在昂貴的 35 倍:225 × 35 = 7,875 元,依然高於現在的收盤價。 |
| 變異認知圖結論框(09-02):現價 = 2028 共識中位EPS的32.6倍/最高EPS的28.4倍 |
| 變異認知圖結論框第二行(09-02):不論哪個口徑,價格隱含的都是偏高的CPO成功機率 |
| 變異認知圖(09-02,數字有誤):7個月後市場為同一批股票多付69%(69% 是庫藏股均價低於當時股價的幅度,不是多付的幅度;6,845÷2,424.82 才是 +182%) |
| 姿態段(09-02):19 位分析師的 FactSet 目標價中位數 5,150 元比收盤<em>低</em> 34%,連已驗證的最高外資目標價(高盛 6,231)也低 20%。 |
| 變異認知第 2 點(09-02):現價是2028共識<em>中位</em>EPS的32.6倍,對照共識<em>最高</em>EPS(275元)仍是28.4倍 — 即便2028藍天全部兌現,三年報酬也已被今天的買家預支。 |
| 分歧 3 卡片(09-02):Divergence 3 / class="lang-zh">分歧 3 The price needs a year that never happened / class="lang-zh">現價要求一個沒發生過的年份 +32% vs +21.7% Revenue growth 2027→2028 implied by today's price, against the best year of 2023–25. / class="lang-zh">今天的價格隱含的 2027→2028 營收成長,對照 2023–25 最好的一年。 |
| 競爭位置段(09-02):地理集中:生產基地集中台中(2026年五度購地共約63億元擴產,多在南屯/西屯) |
| 競爭位置第 3 點(09-02):大立光 41.5 倍,對比玉晶光 27–28 倍高出約 50%,對比舜宇光學 14 倍更是貴了約 3 倍。 |
| 競爭位置結論(09-02):41.5 倍的股價,已經遠遠超越它該有的合理價值 |
| 對照組估值表(09-02 收盤):大立光 7,810/41.5×/1.02兆;玉晶光 1,050/27.2–28.4×/約1,184億;舜宇 HK$71.50/約14×/HK$77.4B;上詮 780/無(EPS −1.22)/886億;天孚 ¥250.00/≈118×/NT$1.29兆(大立光的 1.26 倍) |
| CPO 選擇權定價段(09-02):一句話摘要:拆解大立光 7,810 元的股價會發現:有 5,171 元是靠手機鏡頭撐起來的,剩下的 2,639 元(相當於 3,458 億市值)完全是市場買「AI CPO 夢想」疊上去的溢價。結論:市場付給大立光「CPO 選擇權」的金額,都是台積電 COUPE 平台獨供商整家公司市值的 3.9 到 7.7 倍。 |
| 數字節說明(09-02):共識:FactSet,19位分析師經鉅亨網轉載(2026-08):2026E EPS 187.55/2027E EPS 208.75/2028E EPS 239.29(最高275.07);TP中位數5,150元。本研究EPS高於共識(旺季+可變光圈mix),目標價高於共識中位數、但低於現價25.1% — 分歧不在基本面樂觀度,在「付多少倍」。 |
| 單位數學結果三(09-02):現價 7,810 元要合理(給 28.4 倍本益比),2028 年 EPS 必須飆到 <b>275 元</b>。要從 2027 年的 225 元衝到 275 元(+50 元),營收必須額外爆發 <b>220 億元</b>、年增 <b>+32%</b>。<b>但大立光過去三年表現最好的一年,營收成長也才 +21.7% — 現在的股價,等於要求它交出歷史上從未發生過的成長。</b> |
| 壓力測試結論(09-02):全部仍遠低於收盤 7,810 |
| 壓力測試 3(09-02):這是三個測試裡唯一在 <b>9/10 當天</b>就會揭曉的,也是唯一雙向的 — 覆蓋範圍優於預期即觸發 2027E 上修檢討。 |
| 透支監測表第 1 列現況(09-02):透支 — 7月−10.66%,同期股價21天+96% |
| 透支監測表第 4 列現況(09-02):透支 — 34.15%→27.30%;8月十個交易日僅2天買超 |
| 透支監測表規則(09-02):<b>規則,機制化而非憑感覺:</b>任何<b>兩格</b>落在「透支」欄=視同絆線,即使當月營收好看。<b>目前已有兩格轉紅</b> → 絆線已經觸發。<b>這就是本研究給「迴避」的機制化理由</b>,不是主觀情緒。反向也成立:兩格同時轉回「健康」=本觀點必須重審。 |
| 情境圖說(09-02):現價離多方情境比離基準情境更近。 |
| 空方情境假設(09-02):iPhone 18銷售平淡/可變光圈僅Pro Max;台幣急升重演;CPO滑至2028 |
| 不對稱性檢查(09-02):現價7,810元 → 基準TP:-25.1%;→ 空方情境:-57.4%;→ 多方情境:+4.5%。本研究的多方情境(8,160)只比現價高4.5% — 你今天付的價格幾乎已經是本研究的bull case。 |
| 敏感度矩陣註(09-02):虛線框=現價最接近的格:現價7,810元÷32×≈EPS244……現價落在「多方EPS×本夢比」(8,160)那一格附近,只比它低4.3%。市場同時押了EPS的bull case和倍數的bull case。 |
| 催化劑表第 1–4 列(09-02):9/10 發表會「已排定」;8月營收 ≥55億(本研究門檻)「已排定」;~9/30 CPO 試產線完成架設「公司預告」;~10月(日期未定)Q3 財報+法說「已排定」 |
| T8 規則 4(09-02):9/10 是唯一一天同時揭曉兩個門檻(蘋果發表會與 8 月營收)。要分開打分,不要讓它們混成一個印象。 |
| 操作框架「若已持有」(09-02):預設分批減碼(將暴利了結至核心倉位);若9/10發表會後可變光圈覆蓋優於預期且10月法說毛利率≥52%,核心倉可續抱觀察。 |
| 操作框架「為何不更激進(放空)」(09-02):千金股在外流通僅1.31億股、日成交值百億級、CPO新聞流仍在加速期、9/10發表會事件風險雙向、台股無低成本借券環境 — 負不對稱是「不買」的理由,不構成「放空」的期望值。 |
| 頁首一句話(09-02):觀點「迴避」· 目標價 5,850 元(2027E EPS 225×26倍)· 收盤 7,810 元(隱含 -25.1%)— 公司不錯,是價格問題,非基本面看空。 |
| 頁首開場句(09-02):CPO(共同封裝光學)背後的製造護城河是真的、也能遷移 — 但第一批光纖陣列單元都還沒量產出貨,未來三年的故事就已經全部反映在現在的股價裡了。 |
| 頁面描述(09-02):現價是2028共識中位EPS的32.6倍、最高EPS的28.4倍。研究觀點迴避,目標價5,850元(2027E EPS 225×26倍PER),隱含空間約-25%。 |
| 快照格「外資持股」(09-02):外資持股2025-05→2026-08-28 34.15%→27.30%;8月外資淨賣、投信自8/26起連5買 —「這波上漲外資在減持,不在加持」 |
The superseded sentences are kept verbatim in Chinese; the English view carries no copy of them.
✗→ 2026-09-02 Entry preserved as written; the close price in it was later corrected. This entry used NT$7,850 (a last-quote-before-close estimate, taken while the settled print was not yet retrievable) and an implied return of -25.5%. The verified settled close is NT$7,810 and the implied return is -25.1% — see the entry above and claim #1 in the Sources ledger.條目照原樣保留;其中收盤價事後經修正。本條目使用的7,850元是建置期間(尚未能取得結算價時)的最後報價估計,隱含報酬-25.5%。已驗證結算收盤為7,810元,隱含報酬-25.1% — 詳上方條目與資料來源查證表#1。
First build of this page. Research view: Avoid. Target price NT$5,850 (6-month horizon, 2027E EPS 225 × 26x PER), implied return -25.5% vs the NT$7,850 close. No prior model exists to revise against. Close price note: repeated live pulls during this build returned the same last-available intraday quote (13:03 TPE, 25 minutes before the 13:30 bell); the settled official close could not be retrieved — see the ⚠ note under the masthead.
本頁首次建置。研究觀點:迴避。目標價 5,850元(6個月,2027E EPS 225×26倍PER),對收盤7,850元隱含報酬-25.5%。無前一版模型可供對照。收盤價說明:本次建置多次即時拉取皆回傳同一筆最後可得盤中報價(台北時間13:03,距13:30收盤25分鐘);未能取得交易所正式結算收盤價 — 詳頁首下方⚠說明。
| Date日期 | Action動作 | View觀點 | TP | Close收盤 |
|---|---|---|---|---|
| 2026-10-08 | Q3 call: base case rebuilt, TP cut第 3 季法說:基準情境重建、下修目標價 | Avoid迴避 | 4,500 (prev. 5,850) | 6,660 |
| 2026-09-02 | Initial coverage初次報告 | Avoid迴避 | 5,850 | 7,850 ✗→ |
Append-only ledger. Entries and rows are never deleted, only corrected in place (✗→✓) or superseded by a new row.附加式(append-only)紀錄。條目與列永不刪除,僅原位修正(✗→✓)或以新列取代。
1 · What Largan actually sells
Start with what Largan actually sells: precision, not design. A flagship phone's main camera stacks seven or eight plastic aspheric lens elements, each injection-molded and assembled to sub-micron tolerance. Largan's own reported edge is tolerance control around 0.3μm versus roughly 0.5–0.8μm for peers — a gap that shows up as a 5x-handle gross margin versus rivals' 2–3x handle. That precision culture is now being pointed at a new target: fiber array units (FAU) for co-packaged optics, the plumbing that couples light into and out of silicon-photonics chips inside AI data-center switches. The mechanism transfer — active-alignment assembly skill learned on phone lenses, applied to optical coupling — is real and is the entire basis for a lens company plausibly becoming an optics-interconnect supplier.
一句話總結:大立光靠手機鏡頭的「超高精密技術」跨足 AI 光通訊是事實,但市場現在把「未來的 AI 夢」捧得太高,忽略了它眼前的股價已經偏貴。
1 · 大立光真正厲害的是什麼?(技術本質)
大立光的強項不只是「會設計鏡頭」,而是製造精度高到離譜。
2 · 外星人級別的估值分歧(市場在畫大餅)
對於這個 AI 新故事到 2028 年能賺多少,賣方給出的推估差了整整 10 倍:
3 · 真正在賺錢的引擎 vs. 被炒作的故事
大立光目前真正的業績支撐,根本不是 AI,而是舊有的手機業務:
結論:一家靠著「老本行手機升級」加上「一個還沒實現的 AI 夢想」的公司,股價卻已經衝到 38.6 倍本益比 — 代表市場已經提前把還沒發生的美好未來,先在股價上收繳了。
Finding: Largan's moat is manufacturing precision, not optical design. Optical design — how many lens elements, what curvature, what materials — is broadly known industry knowledge. What separates Largan is the ability to injection-mold plastic aspheric lenses and assemble seven-to-eight-element stacks with decenter and tilt tolerances controlled to roughly 0.3μm, versus an estimated 0.5–0.8μm for competitors ✓ 2026-07 earnings call, via simpletechtrend transcription2026-07法說會,simpletechtrend整理. That precision gap is the entire explanation for Largan's mid-40%s-to-50%s gross margin against peers running 20–30%.
核心摘要:大立光的競爭優勢不是「設計鏡頭」,而是極致的製造工藝。光學設計是公開祕密,但把微小鏡片完美堆疊且不偏心的硬實力,才是它能賺取高毛利的真正護城河。
白話拆解:大立光憑什麼賺大錢?
One unit = one lens, not the full VCM module.
一個單位=一顆鏡頭,不含 VCM 模組。
Full July mix: 10MP+ 60–70% · 20MP+ 10–20% · 8MP 0–10% · sub-5MP 10–20%. Ranges, not exact figures — the company does not disclose finer splits. Both margin calibers sit below 50%: "the 50%+ era ended three quarters ago."
7 月完整結構:1,000萬畫素以上 60–70%・2,000萬畫素以上 10–20%・800萬畫素 0–10%・500萬畫素以下 10–20%。皆為區間、非精確數字 — 公司未揭露更細分項。兩個毛利率口徑都在 5 字頭之下:「5 字頭時代已在三季前結束」。
The problem today
A conventional phone lens has a fixed opening. The light it lets in never changes, so software has to compensate in dim or bright scenes.
What a variable aperture does
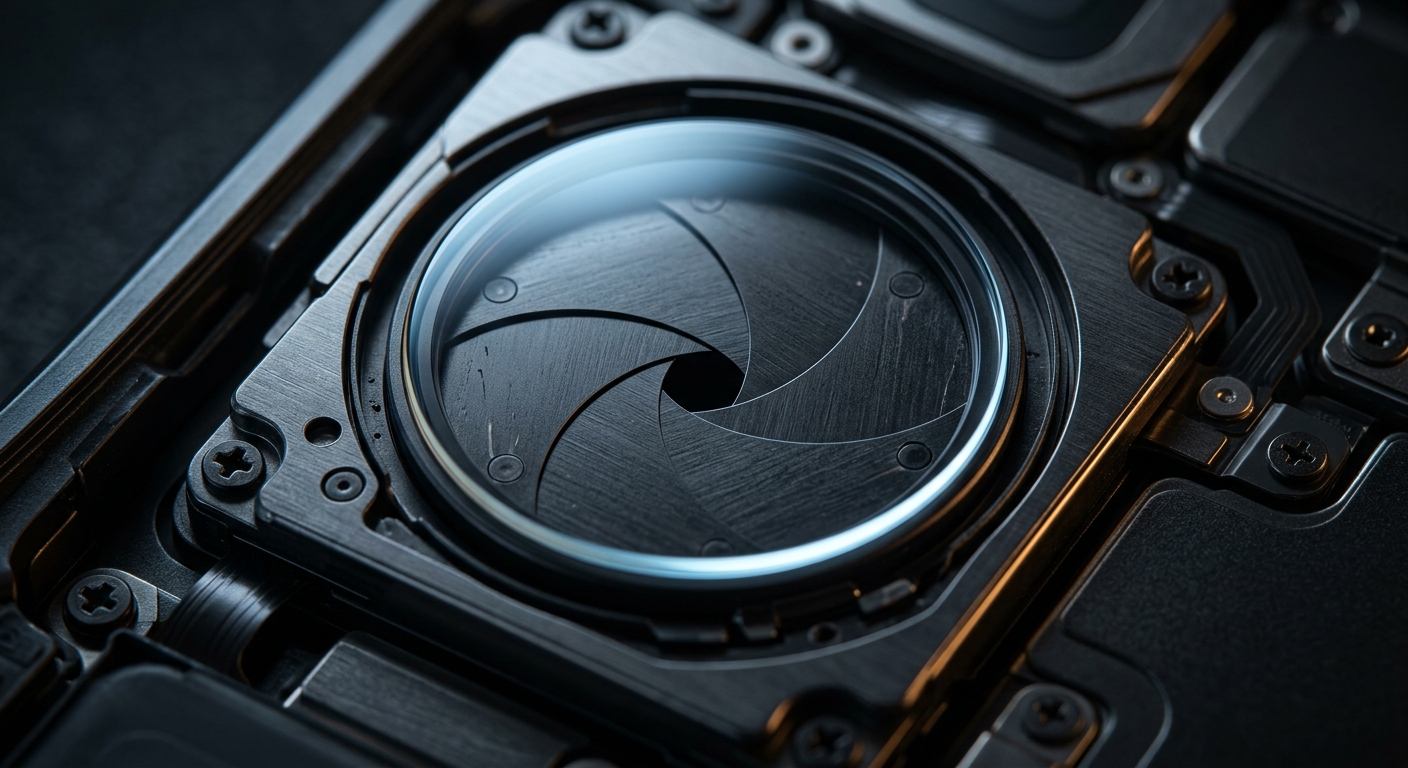
It adds several thin overlapping metal blades that physically rotate to widen or narrow the opening — exactly the iris in a full-size camera lens, shrunk to a few millimeters across and driven by a micro-actuator.
Why this favors Largan specifically
Fitting moving mechanical blades with sub-micron clearances into a phone-thin module is a precision-manufacturing problem before it is an optics problem — which is why the upgrade favors a lens maker with Largan's tolerance-control record over a generic module assembler.
一秒白話比喻:就像人的瞳孔。光線暗時瞳孔放大(多進光)、光線強時瞳孔縮小(避免過曝)。以前手機鏡頭的瞳孔是「死」的,現在要把它做成「活」的。
為什麼利好大立光?這本質上不是光學問題,而是極致的精密微型機械製造問題 — 要讓金屬葉片在幾毫米的空間裡精準轉動、間隙控制在微米等級才不會卡住或漏光。全天下沒幾家做得到,正好是大立光的獨家強項。
現在的問題
一般手機鏡頭的光圈是固定的。進光量永遠不變,所以暗處或亮處都得靠軟體去硬補。
可變光圈做了什麼
它在鏡頭裡加了幾片薄金屬葉片,能物理性地轉動、把開口變大或變小 — 原理跟大台相機的機械光圈一模一樣,只是縮小到幾毫米見方,用微型致動器驅動。
為什麼這件事特別有利於大立光
要在手機厚度的模組裡,塞進會動、而且間隙控制在次微米級的機械葉片,這先是一個精密製造問題,才是光學問題 — 這正是為什麼這個升級偏好大立光這種有公差控制紀錄的鏡頭廠,而不是一般模組組裝廠。
What CPO changes
Co-packaged optics moves the light-to-electricity conversion — the optical engine — from a pluggable module at the edge of a switch box onto the same package as the switch or accelerator chip. Shorter electrical path, less power burned just moving bits between chips.
So how does light get in and out?
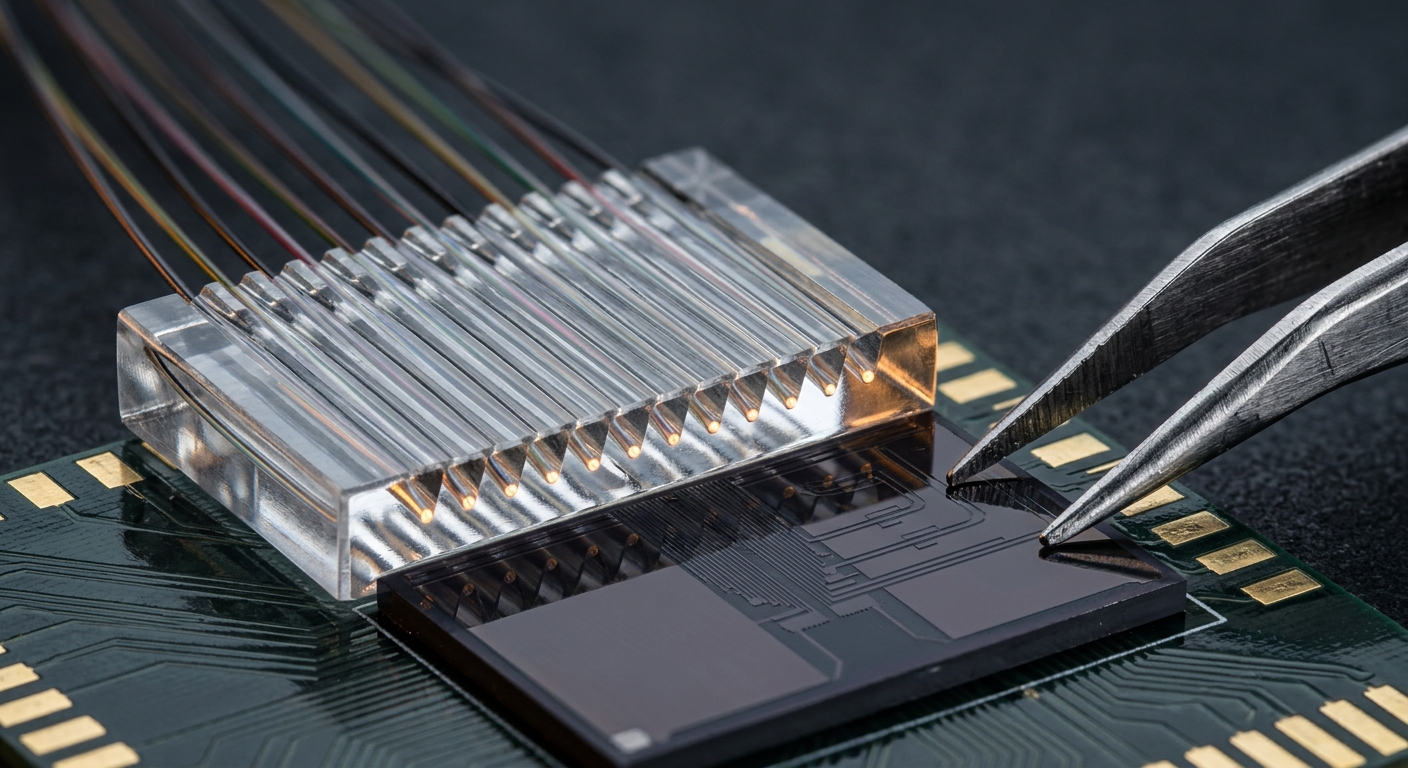
Through the FAU (fiber array unit) — a precision part that holds a row of hair-thin optical fibers in exact alignment and couples their light into a silicon-photonics chip. This is the part Largan is selling.
What Largan's version is made of
一秒白話比喻:AI 晶片專用的光纖插頭。以前 AI 資料中心的傳輸線是銅線,現在資料量太大、傳輸太熱,必須改用光纖。FAU 就是把幾十根比頭髮還細的光纖,精準插進 AI 晶片內部的那個「微型光纖轉接頭」。
大立光賣什麼?在基板上雕出微型 V 形溝槽,把幾十根頭髮細的光纖像排排站一樣卡死,再裝上微型鏡片讓光 90 度轉彎射進晶片。
為什麼利好大立光?要把幾十根光纖精準對齊到晶片上的極小一點,用的對位組裝技術,跟它做手機鏡頭堆疊的技術是完全通用的。
CPO 改變了什麼
共同封裝光學把「光轉電」的工作 —— 也就是光引擎 —— 從交換器機箱邊緣的可插拔模組,直接搬進跟交換器或加速器晶片同一個封裝裡。電訊號路徑變短,資料中心光是把資料在晶片之間搬來搬去所燒掉的電也跟著變少。
那光要怎麼進出?
靠 FAU(光纖陣列單元) —— 一個精密零件,把一整排髮絲般細的光纖固定在精確位置,再把光耦合進矽光子晶片。這就是大立光要賣的東西。
大立光的版本由什麼組成
One line: the switch to optics in AI (CPO) is a long swell, but Largan holds only a very small ticket to it; the phone-lens upgrade is a passing ripple — and the market is valuing the ripple as if it were the swell.
一句話摘要:AI 換光纖(CPO)是長久的大浪,但大立光目前只拿到一張很小的入場券;手機鏡頭升級只是短暫的浪花 — 而市場正把浪花當成大浪在給估值。
The core problem: the market is valuing the ripple as the swell. Of the three chains below, only the second is a swell — and on that chain Largan currently holds a single smallest-configuration order.核心問題:市場錯把「浪花」當「大浪」在給估值。下面三條鏈裡,只有第二條是大浪 — 而大立光在那條鏈上,目前只拿到一張最小規格的訂單。
The AI buildout's scale-up bandwidth demand is running into an electrical-interconnect power wall — moving bits between chips over copper burns power and heat that does not scale the way AI clusters need it to. CPO switches and accelerators are one response, and every CPO package needs an FAU to get light in and out, which is Largan's entry point via FA + PMLA. Read top to bottom, this chain is structural. Read bottom to right, the box it lands on today is a single named order at the smallest configuration — the gap between "the industry needs this" and "Largan has captured meaningful share of it" is exactly where this analysis's skepticism lives.
AI建設的scale-up頻寬需求,正撞上電互連的功耗牆 — 用銅線在晶片之間搬資料所燒的電與熱,跟不上AI叢集需要的規模。CPO交換器與加速器是其中一個解方,而每一個CPO封裝都需要FAU把光送進送出,這正是大立光透過FA+PMLA切入的入口。由左讀到右,這條鏈是結構性的。但讀到最右邊,它今天落在的那個方框,是一張具名的最小規格訂單 — 「產業需要這個」跟「大立光已經拿到這個裡有意義的份額」之間的落差,正是本研究保持懷疑的地方。
Block-level only. This is the standard way the industry draws the shift — pluggable optics at the faceplate versus optics moved onto the ASIC's own substrate. It shows where the parts sit, not the internal optical geometry of any one of them, which Largan has not published.
只到方塊層級。這是業界描述這個轉變的標準畫法 — 光模組掛在面板上,對比光學元件被搬到 ASIC 自己的基板上。它畫的是零件的相對位置,不是任何一顆零件的內部光學幾何(大立光並未公開,本頁不畫)。
Sourced: Largan's FAU comprises a four-layer FA (V-grooves hold each fiber) plus a dual-row 80-channel PMLA that turns the light path 90°, coupling into the chip by grating (GC) rather than the edge-coupling (EC) route Corning's Glass Bridge uses ✓ 工商時報 2026-07-16 · 經濟日報 2026-08-24 · 2026-07 法說. Management says GC and EC will coexist long-term with GC currently larger — a management claim, not independently verified ⚠.
有來源的部分:大立光的 FAU 由四層堆疊的 FA(V 形溝槽固定每根光纖)加上雙排 80 通道的 PMLA 組成,把光路轉 90 度,以光柵耦合(GC)進晶片,而非康寧 Glass Bridge 走的邊緣耦合(EC)✓ 工商時報 2026-07-16・經濟日報 2026-08-24・2026-07 法說。管理層說 GC 與 EC 長期並存、目前 GC 較大 — 此為管理層說法,未經獨立驗證 ⚠。
Mechanism: ~0.3μm decenter/tilt tolerance versus an estimated 0.5–0.8μm for peers, built on 30 years of mold-tool machining know-how and accumulated process parameters ✓ 2026-07法說會.
機制:約0.3μm的偏心/傾斜公差控制,vs同業估計0.5–0.8μm,建立在30年模仁加工know-how與累積製程參數庫上 ✓ 2026-07法說會。
Erosion tripwire: Sunny Optical(2382.HK) closing the yield gap in Android high-end — and a risk the chairman himself named: if AI makes phones need lens-spec upgrades less often, this precision edge has nowhere left to monetize, regardless of how wide it stays.
侵蝕觸發點:舜宇光學(2382.HK)在安卓高階的良率追趕;以及董事長自己點名的風險 — 若AI讓手機愈來愈不需要升級鏡頭規格,這個精密度優勢就算再寬,也沒有地方可以變現。
Mechanism: no off-the-shelf equipment exists for CPO/FAU assembly at volume — Largan built its own automation, so the equipment itself is the barrier, not just the process know-how ✓ 2026-07法說會,simpletechtrend整理.
機制:CPO/FAU組裝目前市面上買不到現成量產設備 — 大立光靠自建自動化做到,設備本身就是門檻,不只是製程know-how ✓ 2026-07法說會,simpletechtrend整理。
Erosion tripwire: a third-party equipment vendor shipping a standardized FAU-assembly line — the moment the tooling becomes purchasable, this barrier democratizes.
侵蝕觸發點:設備商推出標準化的FAU組裝方案 — 一旦設備可以買到,這道門檻就民主化了。
Mechanism: the active-alignment technique used to focus-align phone lenses transfers directly to optical coupling alignment — this is the entire basis for "a lens maker doing FAU" making sense. Citi's read is that Largan can hold yield without needing high-spec V-grooves or ultra-precision fiber, which it frames as differentiation ⚠ reported, management/analyst claim報導轉述,管理層/分析師說法.
機制:手機鏡頭組裝的主動對焦/對位技術,直接遷移到光耦合對位上 — 這是「鏡頭廠做FAU」這件事合理的全部立論基礎。Citi的看法是大立光不依賴高規格V-groove與高精度光纖也能維持良率,並將此定位為差異化 ⚠ 報導轉述,管理層/分析師說法。
Erosion tripwire: this claim has not been independently verified against a rival's yield data — treat it as a hypothesis this analysis has not stress-tested, not a confirmed edge.
侵蝕觸發點:此說法尚未經對手良率數據獨立交叉驗證 — 應視為一個尚未被本研究壓力測試過的假說,不是已確認的優勢。
Mechanism: Corning runs edge coupling (EC) via its Glass Bridge; Largan runs grating coupling (GC). Management says the two routes coexist long-term and GC currently holds larger share ⚠ management claim, share % not independently verified管理層說法,市占數字未獨立驗證. The distinction that matters: CPO's structural growth is close to sell-side consensus — but at the FAU node specifically, Largan is a late entrant. Foxsemicon(3363.TT) is TSMC's sole COUPE-platform supplier, Tainbow Photonics(300394.SZ) is China's NVIDIA-ecosystem leader, and Point Optics(3163.TT) sits in the Spectrum-X ecosystem. A strong industry moat does not guarantee Largan's share of it.
機制:康寧走邊緣耦合(EC)路線,靠Glass Bridge產品;大立光走光柵耦合(GC)路線。管理層說法是兩條路線長期並存,目前GC市占較大 ⚠ 管理層說法,市占數字未獨立驗證。真正重要的區分:CPO產業結構性成長幾乎是賣方共識 — 但在FAU這個節點上,大立光是後進者。上詮(3363.TT)是台積電COUPE平台獨供、天孚通信(300394.SZ)是輝達生態的中國龍頭、波若威(3163.TT)在Spectrum-X生態系裡。產業護城河強,不代表大立光在其中的份額有保障。
| Indicator指標 | Where to check去哪裡查 | Threshold門檻 |
|---|---|---|
| Largan's own monthly revenue + self-reported monthly profit大立光月營收+自結單月純益 | MOPS (公開資訊觀測站), ~10th of each month公開資訊觀測站,每月~10日 | Aug revenue ≥NT$5.5bn (this analysis's own threshold) = seasonal ramp confirmed8月營收≥55億(本研究門檻)=旺季軌道確認 |
| TSMC(2330.TT) COUPE platform progress平台進度 | TSMC technology symposium / earnings call台積電技術論壇/法說會 | upstream-most CPO signal; Foxsemicon is its sole FAU supplierCPO生態最上游訊號;上詮為其FAU獨供 |
| NVIDIA(NVDA.O) CPO switch shipments & Rubin/Rubin Ultra timeline交換器出貨與時程 | GTC / earnings calls法說會 | Largan supplying Rubin Ultra is currently market speculation — any official confirm/deny is a re-rating event大立光供貨Rubin Ultra目前是市場臆測,任何官方確認/否認都是重定價事件 |
| Foxsemicon(3363.TT) / Point Optics(3163.TT) monthly revenue月營收 | MOPS | FAU-peer volume ramp, corroborating or contradicting the chainFAU同業放量旁證 |
| Tainbow Photonics(300394.SZ) quarterly report季報 | SZSE filings深交所公告 | China's FAU-leader CPO revenue magnitude, as a scale reference中國FAU龍頭的CPO收入量級對照 |
| Genius Electronic Optical(3406.TT) monthly revenue月營收 | MOPS | Apple high-end lens dual-source share shift蘋果高階鏡頭雙供份額變化 |
| USD/TWD | Central bank / Bank of Taiwan posting央行/台銀牌告 | 2025 Q2's NT$4.22bn FX-loss precedent — a sharp TWD rally hits EPS directly2025Q2單季匯損42.2億前科 — 台幣急升=EPS直接侵蝕 |
AI-camera demand, then Apple's biggest camera upgrade in a decade (variable aperture, iPhone 18 Pro, launched 2026-09-10), then high-end lens ASP +~50%, then Largan as one of the primary suppliers (share unverified) ✓ 豐雲學堂 2026-08 → revenue grows through mix, not unit volume. Level: ASP/mix. Nature: cyclical (spec bonus recurs every 1–2 years). Deceleration risk: variable aperture confined to Pro Max only, yield issues, Apple reallocating share to a second source.
AI手機影像需求 → 蘋果十年最大相機升級(可變光圈,iPhone 18 Pro,2026/9/10發表)→ 高階鏡頭ASP+約50% → 大立光為高階主力供應商之一(份額未證實)✓ 豐雲學堂 2026-08 → 營收靠mix而非量成長。層級:ASP/mix。屬性:循環性(規格紅利1–2年一波)。減速條件:可變光圈僅Pro Max獨占、良率不順、蘋果分單。
AI data-center scale-up bandwidth demand → electrical-interconnect power/density wall → CPO switches/accelerators → FAU demand → Largan enters via FA + dual-row 80-channel PMLA, extending toward a full FAU module ✓ 工商時報 2026-07-16/經濟日報 2026-08-24. Level: new TAM. Nature: structural but not yet realized — a mass-production-tier customer's formal spec document received, samples shipped July, pilot line launching September, mass production "at the earliest" mid-2027. Deceleration risk: customer qualification fails, timeline slips to 2028, Foxsemicon/Tainbow lock in the position first.
AI資料中心scale-up頻寬需求 → 電互連功耗/密度撞牆 → 光引擎進封裝(CPO)→ 每顆CPO交換器/加速器需要FAU把光耦合進出矽光子晶片 → 大立光以FA元件+雙排80通道PMLA切入,並延伸到FAU模組一條龍 ✓ 工商時報 2026-07-16/經濟日報 2026-08-24。層級:新TAM。屬性:結構性但未兌現 — 已收到量產型客戶正式規格文件、7月送樣、試產線9月啟動、最快2027年中放量。減速條件:客戶驗證不過、時程滑到2028、上詮/天孚通信先卡位。
A foldable iPhone (expected to debut 2026-09-10; whether it launched was not checked line by line) adds lens positions; humanoid-robot vision-lens orders are already in hand ✓ 今周刊 2025-01; AR glasses remain a further-out option. Level: unit volume. Nature: optionality, all currently small in magnitude. Chairman Lin En-ping told the earnings call foldable-phone lenses are "not comparatively difficult" — i.e. for Largan, foldables are a volume add-on, not an ASP step-up.
摺疊iPhone(原預期2026/9/10亮相;本次未逐項查證是否已發表)增加鏡頭位;人型機器人視覺鏡頭訂單已到手 ✓ 今周刊 2025-01;AR眼鏡是更遠的選擇權。層級:量。屬性:選擇權,目前量級都小。林恩平在法說會親口說摺疊機鏡頭「困難度沒有相對比較高」— 即摺疊機對大立光是量的加項、不是ASP跳升項。
Variable aperture is "the biggest camera upgrade in a decade"; high-end lens ASP +~50%; Largan is one of the primary suppliers (share unverified); Q4 "will be busier than usual years" per the 2026-06-09 shareholder meeting ✓. All of this is already inside guidance.
可變光圈是「十年最大相機升級」、高階鏡頭單價+50%、大立光為高階主力供應商之一(份額未證實);Q4「將比往年忙」(股東會6/9)✓。已在guidance內。
In April the company said it was "evaluating". By July it had a spec document and had shipped samples. A pilot line followed in September, and mass production comes in mid-2027 at the earliest. Seven land purchases since late June total NT$8.078bn, which is the company voting with capital spending. Self-built equipment, 0.3μm tolerance and the transfer of active-alignment know-how are real differentiation. Still an unproven option, but the milestones are landing densely.
4 月公司還說「評估中」。7 月已拿到規格書並送樣。9 月架設試產線,最快 2027 年中放量。自 6 月底起七度購地,合計 80.78 億元,這是公司用資本支出投票。自建設備、0.3μm 精度與主動對位(AA)技術的遷移,是真正的差異化。屬未證實的選擇權,但里程碑在密集兌現。
Net profit margin can return to 40%+ without FX noise (43.6% in 2024); operating margin 37%+; net cash + book value NT$1,478/share provides a downside cushion (relatively speaking — with PBR at 4.5x, that cushion is thin).
無匯損干擾下NPM可回40%+(2024年43.6%);營益率37%+;淨現金+每股淨值1,478元提供下檔緩衝(相對而言 — PBR4.5倍下緩衝有限)。
Semi-annual dividends plus treasury-share cancellation, and robotics/foldable/AR optionality not yet in any model.
資本配置轉向股東(半年配+庫藏股註銷)+機器人/摺疊/AR選擇權未計價。
Structured as fear → company claim → independent evidence → this analysis's judgment.
結構:市場恐懼 → 公司說法 → 獨立證據 → 本研究判斷。
Q2 2026 after-tax profit +352% YoY versus operating profit +5.5% YoY is the headline mismatch; July revenue also fell -10.66% YoY ✓. Full argument (the three H1 growth rates side by side, and why the gap matters) is argued once under Variant perception — not repeated here. This analysis's judgment: the core business is a mid-single-digit-growth mature franchise, not a re-accelerating one.
Q2 2026稅後+352% YoY對比營業利益僅+5.5% YoY,是頭條數字的落差;7月營收也年減10.66% ✓。完整論證(H1三個成長率並列,以及落差為何重要)僅在變異認知一次講完,此處不重複。本研究判斷:本業是中個位數成長的成熟事業,不是重加速。
Fear: gross margin has fallen below 50% for four consecutive quarters: 4Q25 47.75%、1Q26 49.4%、2Q26 49.41%、3Q26 42.21% ✓.
Company claim: yield is the key variable (July call). On 10-08 the company named two causes for the Q3 drop. One is green-power purchases, a structural cost. The other is yield.
Independent evidence: Q3 gross margin fell 7.2pp from Q2, and this analysis's own trailing-4Q derivation lands at 約 47.1% ◆ derived推算.
This analysis's judgment: 2026E gross margin is 45.9% and 2027E 47.0%, well below 2024's 52.4%.
市場恐懼:毛利率連續四季跌破50%:4Q25 47.75%、1Q26 49.4%、2Q26 49.41%、3Q26 42.21% ✓。公司說法:7 月說良率是關鍵;10-08 又說第 3 季下滑有兩個原因:綠電購買(結構性成本)和良率。獨立證據:第 3 季毛利率比第 2 季少 7.2 個百分點,本研究自行推算的近四季毛利率約47.1% ◆ 推算。
本研究判斷:2026E毛利率45.9%、2027E 47.0%,遠低於2024年的52.4%。
The first order is a single-row FA (the smallest configuration); mass production is "at the earliest" mid-2027; the traditional sell-side camp estimates CPO at just 1–2% of 2028 revenue. Even a meaningful 2027 win adds only a low single-digit percentage to EPS that year — yet the price has already discounted Citi's 2028 bull case (20% of revenue).
首張訂單是單排FA(最小規格);量產「最快」2027年中;傳統賣方估2028僅占營收1–2%。以2027年貢獻推估:即使拿下可觀份額,對EPS的增量在2027年是個位數百分比。價格卻已按Citi 2028藍天(20%營收占比)折現。
Foxsemicon/Tainbow Photonics have already staked out the FAU node; Apple's dual-sourcing policy permanently caps ASP; the CEO himself admits AI is eroding lens-upgrade demand.
FAU節點上詮(3363.TT)/天孚通信(300394.SZ)已先卡位;蘋果雙供政策長期壓ASP;CEO自己承認AI侵蝕鏡頭升級需求。
A single quarter (Q2 2025) FX loss of NT$4.22bn ate 80% of that quarter's profit, dropping EPS to NT$7.73, a 13-year low ✓. A sharp TWD rally would force a full recalc of the 2026H2/2027 model.
2025Q2一季匯損42.2億(吃掉單季獲利八成、EPS剩7.73,13年低點)✓。台幣若再現急升,2026H2/2027模型全部重算。
38.6x trailing, versus a three-year (2023–25) cyclical mid-point of roughly 12–20x ◆ estimated概算. That is a mid-point, not a ceiling. In the 2015–17 upgrade boom Largan traded well above 20x.
Margin, day-trading and passive ETF buyers piled in during the 21-day doubling. That amplifies any drawdown if the narrative cools.
38.6倍trailing vs自身近三年(2023–25)循環中樞約12–20倍 ◆ 概算 — 是中樞不是天花板:2015–17規格升級大年曾長期高於20倍(與TP區塊同一口徑);21天翻倍後的籌碼結構(融資/當沖/被動ETF追買)任何敘事降溫都放大回撤。
AI making phone camera specs less necessary to upgrade is eating our future.AI 讓手機鏡頭規格「愈不需要升級」,等於是在吃掉我們的未來。
Stance — this page argues with the tape, not with the sell-side. The FactSet target-price median across 18 analysts (NT$5,300, 2026-10-05, before the call) sits 20% below the close, and even the verified highest foreign-broker target (Goldman Sachs, NT$6,231, 07-01) is 6% below it. This analysis lands lower than both, at NT$4,500. Nomura's NT$8,300 (10-06) is the exception above the close. That settles where the burden of proof lies: this page does not have to show the analysts are wrong — only what the tape is paying for.姿態:跟盤面吵,不跟賣方吵。18 位分析師的 FactSet 目標價中位數 5,300 元(10-05,法說前)比收盤低 20%,連已驗證的最高外資目標價(高盛 6,231,07-01)也低 6%。本研究的 4,500 元比這兩個數字都低。野村的 8,300 元(10-06)是高於收盤的少數例外。這決定了這份報告的舉證責任:不需要證明賣方錯了,只需要說明盤面在為什麼付錢。
Market narrative (since 2026-08): "the camera king becomes an AI optical-interconnect stock" — Largan re-rated from a phone-cycle name to a CPO-infrastructure supplier, sell-side target-price medians trailing behind the stock price, with the latest reports racing to raise (Nomura NT$4,310→6,000→8,300 on 10-06).
市場敘事(2026-08之後):「鏡頭王變AI光通訊股」— 大立光從手機循環股重定價為CPO基礎設施供應商,FactSet目標價中位數落後股價,最新報告競相上調(野村4,310→6,000→8,300,10-06)。
What this analysis agrees with (the opponent's strongest card, stated first): the manufacturing-precision moat is real and transferable — 0.3μm tolerance, self-built equipment, active-alignment transfer to optical coupling; this is not a hollow story-multiple. The milestones (spec document → samples → pilot line → land purchases) are landing densely, and a management team with a track record of blunt, honest disclosure gives "mass production mid-2027" real weight. The direction is right.
本研究同意的部分(先講對手最強的牌):製造精度護城河真實且可遷移 — 0.3μm公差、自建設備、AA對位遷移到光耦合,這不是本夢比空殼;里程碑(規格書→送樣→試產線→購地)在密集兌現;管理層誠實紀錄讓「2027年中放量」這句話有分量。方向是對的。
Where this analysis diverges — three facts the market has skimmed past:
本研究的分歧 — 三個被市場略過的事實:
One-line variant:一句話變異認知: this is a "right story, prepaid price" — this analysis does not argue against the CPO narrative; it argues against a price that has already compressed 2028's discount rate to zero. 這是一個「對的故事、透支的價格」— 本研究不與CPO敘事作對,與「把2028藍天貼現率壓到零」的價格作對。
Chairman Lin En-ping — second-generation family leadership — is known in the local press for "saying it straight" at earnings calls (media nickname: "the most honest chairman"). He discloses bad news himself: the 2025 Q2 FX loss of NT$4.22bn, and AI eroding lens-upgrade demand. That candor makes his guidance more credible, but it also means the guidance carries no padding.
林恩平(董事長,創辦家族第二代經營者)以「法說會有一說一」聞名(媒體稱「最老實董座」)。負面訊息自己講:2025Q2匯損42.2億、AI吃掉鏡頭升級需求。這種管理層的guidance可信度高,但也意味guidance沒有灌水緩衝。
30 consecutive years of dividends; switched to semi-annual payouts from 2026 (H1 paid NT$41.5, payout ratio 50.39%) ✓. In 2025-12 the board approved its second-ever treasury-share programme (statutory ceiling NT$179.66bn — the legal maximum, not the actual size); by 2026-02-02 it had bought back 2,670 board-lots at an average of NT$2,424.82, NT$6.47bn in total, for cancellation ✓ 中央社. Management bought its own stock at NT$2,425; nine months later the market pays NT$6,660 — management's entry is 64% below where the market is paying today.
一句話摘要:大立光開始注重股東權益(改半年配息、實施庫藏股),而且管理層買自家股票買在超級便宜的底部;但因為市值已經膨脹到破兆,手上的千億現金,防禦力其實相當有限。
1 · 資本配置在變好(對股東變大方了)
2 · 董監持股與籌碼
董監持股約 19%(2026-05)✓,大股東跟公司綁在一起;未見近期內部人大額申讓報導(未逐筆查證申報 ⚠)。
3 · 口袋極深,但「防守保護力」不夠大
Insider ownership is roughly 19% (board + supervisors, 2026-05) ✓; no recent large-block insider-transaction reporting was found (this page did not check individual filings line by line ⚠). Cash & equivalents were NT$115.9bn at FY2025-end (about NT$885/share) ✓ 富邦 balance-sheet timeline富邦資產負債表年表, and NT$118.482bn at Q2'26-end (about NT$905.75/share) ✓ consolidated cash-flow statement, closing cash balance合併財報現金流量表期末現金餘額. Book value NT$1,478/share (Q3 equity 除以 130.8M shares) and the treasury-programme ceiling of NT$179.66bn corroborate distribution capacity. But scale it against the market cap: at PBR 4.5x, the cash cushion is only about 13.6% of the about NT$0.87tn market cap (118.48 divided by 871.1) — "having cash" is not the same as "having downside protection."
| Comparison比較項目 | Largan 3008.TT | Genius Electronic Optical 3406.TT | Sunny Optical 2382.HK | Foxsemicon 3363.TT / Tainbow Photonics 300394.SZ上詮 3363.TT / 天孚通信 300394.SZ |
|---|---|---|---|---|
| Main battlefield主戰場 | Apple's primary high-end lens supplier蘋果高階鏡頭主供 | Apple's second source蘋果第二供應商 | Android leader, automotive lenses安卓龍頭、車載鏡頭 | CPO FAU (Foxsemicon: sole for TSMC's COUPE; Tainbow: China's NVIDIA-ecosystem leader)CPO FAU(上詮:台積電COUPE獨供;天孚:輝達生態中國龍頭) |
| iPhone 18 variable apertureiPhone 18可變光圈 | One of the primary high-end suppliers (share unverified); "near-sole source" is media inference — a counter-rumor ("declined extra orders") also circulates, neither direction confirmed高階主力供應商之一(份額未證實);「近獨供」為媒體推斷,另有「婉拒加單」等相反傳聞,兩個方向都未證實 ⚠ unverified, both directions兩方向皆未證實 | Investing NT$1.86bn to expand capacity to compete for it斥資18.6億擴產搶進 ✓ CMoney 2026-08 | Rumored to take 40–50% of module assembly傳聞分食模組端40–50% ⚠ unconfirmed rumor未經證實 | n/a不適用 |
| CPO positionCPO位置 | Late entrant, end-to-end (FA→FAU), mass-production-tier customer spec in hand後進者、一條龍(FA→FAU)、量產型客戶規格書在手 | none無 | no disclosed positioning無公開布局 | First mover, already inside the ecosystem先行者、已在生態系內 |
Geographic concentration: production is centered in Taichung (seven land purchases announced since late June, totaling over NT$8bn, to expand capacity, mostly in Nantun/Xitun districts) ✓ 中央社 2026-10-05. Customer concentration: Apple is a high share of revenue (the company has not disclosed the exact ratio ⚠).
地理集中:生產基地集中台中(2026年自6月底起已七度公告購地,合計逾80億元擴產,多在南屯/西屯)✓ 中央社 2026-10-05。客戶集中:蘋果占比高(公司未揭露精確比例 ⚠)。
| Company公司 | Close (Largan 10-08, others 10-07)收盤(大立光 10-08,其餘 10-07) | Trailing-4Q PER近四季PER | Market cap市值 | Role角色 |
|---|---|---|---|---|
| 大立光 3008.TT | 6,660 | 38.6× | NT$0.87tn0.87兆 | Apple's primary high-end lens supplier + CPO late-comer蘋果高階鏡頭主供+CPO後進者 |
| 玉晶光 3406.TT | 1,085 (+3.83%) | 28.3× | ~NT$122bn約1,223億 ⚠ 依09-02市值按股價比例推算 | Apple's second lens supplier. Yahoo PER 28.27x; price matches the IBKR daily bar.蘋果第二供應商。Yahoo 本益比 28.27 倍;股價與 IBKR 日線一致。 ✓ Yahoo+IBKR 2026-10-07 |
| 舜宇光學 2382.HKSunny Optical 2382.HK | HK$64.96 | 12.6× | HK$70.0B | Android lens leader (EPS 5.10). PER and market cap are stockanalysis intraday 10-07 (HK$65.05).安卓鏡頭龍頭(EPS 5.10)。本益比與市值取自 stockanalysis 10-07 盤中(HK$65.05)。 ✓ IBKR+stockanalysis 2026-10-07 |
| 上詮 3363.TWO | 679 (+4.46%) | 無n/a | NT$77.2bn771億 | Sole FAU supplier on TSMC's COUPE platform. Trailing EPS was −1.22 at the 09-02 pull; no new quarter since. Market cap = 679 × 113.64M shares.台積電COUPE平台FAU獨供 — 近四季EPS −1.22元(09-02取數,之後沒有新財報),算不出本益比。市值=679×1.1364億股。 ✓ Yahoo+IBKR 2026-10-07 |
| 天孚通信 300394.SZTFC 300394.SZ | ¥260.78 (09-30 收盤)(09-30 close) | ≈123× | ¥284.5bn ≈ NT$1.35tn¥2,845億 ≈ NT$1.35兆 | China's NVIDIA-ecosystem FAU leader — 1.55× Largan's market cap. PER and share count come from the 09-02 pull (EPS ≈ ¥2.12) re-priced; no new quarter since. China markets are closed for the holiday until 10-08. FX 4.741 = Bank of Taiwan spot mid, 10-01.輝達生態中國FAU龍頭 — 市值是大立光的1.55倍。本益比與股數沿用 09-02 取數(EPS 約 ¥2.12)按新股價重算,之後沒有新財報。中國市場放假到 10-08。匯率 4.741 = 台灣銀行 10-01 即期中間價。 ⚠ 推算值;最後一根日線 09-30 ✓ IBKR 2026-09-30 |
1. The bull's strongest card, and it holds. Foxsemicon is the sole FAU supplier on TSMC's COUPE platform — the most orthodox beneficiary at the CPO end of this chain — and it carries a trailing-four-quarter loss of NT$1.22 per share, which is why no PER can be computed for it at all. Pricing at the CPO end has detached from earnings entirely. Against that kind of pure story stock, Largan at least has NT$172 of trailing EPS underneath its price. The argument that "Largan is the cheapest way to own CPO exposure" is a real argument, and this analysis concedes it.
一句話摘要:大立光確實是 CPO 概念股裡最有獲利支撐的一檔,但別把「比瘋狂的泡泡股便宜」當成「真的便宜」;它 95% 的收入依然靠手機鏡頭,而 38.6 倍本益比已經嚴重偏貴。
1 · 先承認多方最強的牌:大立光確實是 CPO 概念股中最有底氣的
2 · 打破迷思:不是 CPO 市場太小,而是市場給的估值太不理性
3 · 用「鏡頭本業」這把尺來量,大立光已經太貴
4 · 本研究的最終回應
4. This analysis's answer. "Cheap relative to 123×" is not cheap — it is the same trade with less leverage. "Cheap relative to the pure story stocks" only holds while the CPO theme keeps being priced as a theme. The moment pricing reverts from story to earnings, the lens ruler (27× / 14×) is the direction gravity points — and 95%+ of Largan's revenue today is still lenses. This analysis does not dispute that Largan is the best-quality name in this basket. It disputes that 38.6× is a fair price for that quality.
4. 本研究的回應。「相對 123 倍便宜」不是便宜,是同一筆交易的低槓桿版本。「相對純故事股便宜」只在 CPO 主題持續被當成主題定價時成立。一旦定價機制從故事回到盈餘,鏡頭這把尺(28 倍/13 倍)才是重力的方向 — 而大立光今天 95% 以上的營收仍然在鏡頭。本研究不否認大立光是這個籃子裡品質最好的一檔,只否認 38.6 倍是這個品質的合理價。
If Largan's lens business deserves Yuchang's multiple (28.27× on trailing EPS of 172.38), the lens business is worth about NT$4,873 a share. Subtract that from the NT$6,660 close and the market is paying NT$1,787 a share — about NT$233.7bn — for the CPO option alone. Valuing the lens business off a different peer makes the number bigger, not smaller. On 10-07 the same sum gave NT$200.4bn; it is larger now because trailing EPS fell from 188.02 to 172.38 after the Q3 results, which lowers the lens value. Peer prices are still the 10-07 figures.
一句話摘要:拆解大立光 6,660 元的股價:有 4,873 元是靠手機鏡頭撐起來的,剩下的 1,787 元(約 2,337 億市值)是市場為「AI 光纖零件夢想」多付的錢。
第一步 · 先算「實打實的手機鏡頭本業」值多少錢?
近四季實賺 172.38 元(EPS,含第 3 季 39.62 元)。借用同業玉晶光目前的本益比 28.27 倍(10-07 價格):
172.38 × 28.27 = 4,873 元/股。
第二步 · 這個夢想被多付了多少錢?
6,660 元(現價)− 4,873 元(本業價值)= 1,787 元/股。
乘上 1.308 億股,市場為這個夢想多付了約 2,337 億元的市值。10-07 是 2,004 億,這次比較大,因為第 3 季財報讓近四季 EPS 從 188.02 元降到 172.38 元,鏡頭本業的價值跟著變小。
第三步 · 換一家同業來比,只會更大
下表是三種比法的結果 — 不論拿哪一家來比,這筆「夢想溢價」都還在。
| Which multiple the lens business is valued at鏡頭本業比照誰的倍數 | Lens value (NT$/sh)鏡頭價值(元/股) | Implied CPO option隱含CPO選擇權 | × Foxsemicon's entire market cap (NT$77.2bn)=上詮整家市值(771億)的 |
|---|---|---|---|
| Yuchang Optics, 28.27×比照玉晶光 28.27 倍 | 4,873 | 1,787 = NT$233.7bn | 3.0× |
| Largan's own 2023–25 cyclical mid-point, 16×比照自己 2023–25 的循環中樞 16 倍 | 2,758 | 3,902 = NT$510.4bn | 6.6× |
| Sunny Optical, 12.56×比照舜宇 12.56 倍 | 2,165 | 4,495 = NT$587.9bn | 7.6× |
Whichever peer the lens business is valued against, what the market pays for Largan's CPO option is 3.0 to 7.6 times the entire market capitalization of the sole FAU supplier on TSMC's COUPE platform — for a business where Largan is a late-comer, whose first disclosed order is the smallest configuration (a single-row fiber array), and which is worth about NT$3 of 2027 EPS on this analysis's own bridge. The gap is narrower than on 09-02 (3.9 to 7.7 times) and similar to 10-07 (2.6 to 7.6 times), and it is still large.
不論拿哪一家同業來替鏡頭本業定價,市場付給大立光「CPO 選擇權」的金額,都是台積電 COUPE 平台獨供商整家公司市值的 3.0 到 7.6 倍 — 而大立光在這個節點上是後進者,首張揭露的訂單是最小規格的單排光纖陣列,依本研究自己的橋只值約 3 元的 2027 年 EPS。這個倍數比 09-02(3.9 到 7.7 倍)小,與 10-07(2.6 到 7.6 倍)相近,但仍然很大。
14 terms used across this page.
本文用到的14個術語。
| Claim主張 | Verdict判定 | Value · source · as-of數值 · 來源 · 日期 |
|---|---|---|
| Price & valuation (masthead)價格與估值(頁首) | ||
| 1. Close NT$7,810 (+3.03% from NT$7,580), settled 13:30 TPE — ✗→✓ corrected from an earlier NT$7,850 last-intraday-quote estimate used mid-build收盤7,810元(較前收7,580 +3.03%),台北時間13:30已收盤 — ✗→✓ 修正自建置期間曾使用的7,850盤中估計值 | ✓ settled close已收盤 | Yahoo股市 2026-09-02 13:30 |
| 2. 52-week range 2,020–7,99552週區間2,020–7,995 | ✓ | 鉅亨網 2026-09-02 |
| 3. Market cap ≈NT$1.03tn市值約1.03兆 | ✓ | 鉅亨網 2026-09-02 |
| 4. Paid-in capital NT$1.307bn / ~131M shares outstanding股本13.07億元/流通約1.31億股 | ✓ | 鉅亨網+中央社 2026-02-02 |
| 5. PBR 6.29× / book value NT$1,240.07/sharePBR 6.29倍/每股淨值1,240.07元 | ✗→✓ was 6.35x — a ratio left over from the build-time price, not recomputed when the close was corrected; 7,810 ÷ 1,240.07 = 6.298 and 鉅亨 shows 6.29 the same day前版 6.35 倍是建置期價格對應的舊比值,收盤更正時未跟著重算;7,810÷1,240.07=6.298,鉅亨同日亦顯示 6.29 | 鉅亨網 2026-09-02+本研究計算鉅亨網 + this analysis |
| 6. Trailing 4Q EPS NT$188.02近四季EPS188.02 | ✓ | 財報狗 2026-09 |
| 7. Dividend yield ≈1.02% (80 ÷ 7,810)殖利率 約1.02%(80÷7,810) | ✗→✓ 鉅亨 shows 1.23%, but 1.23% × 7,810 = NT$96, which does not reconcile with the FY25 dividend of NT$80 stated on this page; its numerator and caliber are undisclosed, so the auditable 80 ÷ close is used instead鉅亨顯示 1.23%,但 1.23%×7,810=96 元,與本頁自列的 FY25 股利 80 元對不起來;分子與口徑未揭露,故改用可稽核的 80÷收盤 | 本研究計算(股利80元 ✓ 財報狗)this analysis (dividend ✓ 財報狗) |
| 8. Foreign ownership: 34.15% (2025-05) → 27.30% (2026-08-28); foreign investors were net sellers through August; local funds (投信) bought 5 straight sessions from 8/26 (they were still net sellers of 107 board-lots on 8/25)外資持股:2025-05為34.15% → 27.30%(2026-08-28);8月外資淨賣;投信自8/26起連5買(8/25尚賣超107張) | ✓ Yahoo chip page and ifa.ai agree at 27.30%; the reviewer's 9/1 read of 26.64% is consistent with a further ~670 board-lots of foreign selling on 8/29–9/1 (≈0.5pp)Yahoo籌碼頁與ifa.ai同為27.30%;審閱記9/1為26.64%,與8/29–9/1外資續賣約670張(≈0.5pp)方向一致 ✗→✓ "17 straight sessions" was wrong — corrected to 5原「投信連17買」為錯誤,更正為連5買 | Yahoo股市籌碼頁+ifa.ai 2026-09-02 |
| 9. Insider (board+supervisor) ownership ≈19.02% (2026-05-17)董監持股約19.02%(2026-05-17) | ✓ | ifa.ai |
| Financial actuals財務實績 | ||
| 10. Q2 2026 revenue NT$13.665bn (QoQ -12.1% / YoY +17.1%)Q2 2026營收136.65億(QoQ-12.1%/YoY+17.1%) | ✓ | 鉅亨網 2026-07-09 |
| 11. Q2 2026 EPS 35.72 / after-tax profit NT$4.67bnQ2 2026 EPS35.72/稅後46.7億 | ✓ | 鉅亨網/時報 2026-07-09 |
| 12. Q2 2026 after-tax profit +352% YoYQ2 2026稅後YoY+352% | ✓ | ETtoday 2026-07-09 |
| 13. Q2 2026 operating profit only +5.5% YoYQ2 2026營業利益YoY僅+5.5% | ✓ | simpletechtrend 2026-07 |
| 14. H1 2026 revenue NT$29.209bn / after-tax profit NT$10.793bn (+44.38%) / EPS 82.35H1 2026營收292.09億/稅後107.93億(+44.38%)/EPS82.35 | ✓ | 鉅亨網 2026-07-09 |
| 15. H1 2026 gross margin 49.41% (YoY -4.77pp); Q2 YoY -4.22ppH1 2026毛利率49.41%(YoY-4.77pp);Q2 YoY-4.22pp | ✓ | 鉅亨網 2026-07-09 |
| 16. July revenue NT$4.877bn (MoM +31.4% / YoY -10.66%)7月營收48.77億(MoM+31.4%/YoY-10.66%) | ✓ | 鉅亨網 2026-08-05 |
| 17. Jan–Jul cumulative revenue NT$34.086bn (+7.49%)1–7月營收340.86億(+7.49%) | ✓ | 鉅亨網 2026-08-05 |
| 18. July self-reported net profit NT$1.826bn / EPS 13.94; Jan–Jul EPS 96.297月自結純益18.26億/EPS13.94;1–7月EPS96.29 | ✓ | 鉅亨網 2026-08 |
| 19. July shipment mix: 10MP+ 60–70%7月出貨結構10MP+占60–70% | ✓ | 鉅亨網 2026-08-05 |
| 20. FY2025: revenue NT$61.148bn / GM 50.37% / after-tax NT$21.282bn (-17.9%) / EPS 159.46FY2025:營收611.48億/毛利率50.37%/稅後212.82億(-17.9%)/EPS159.46 | ✓ | 鉅亨網法說 2026-01-08 |
| 21. FY2024: revenue NT$59.458bn / GM 52.41% / after-tax NT$25.915bn / EPS 194.17FY2024:營收594.58億/毛利率52.41%/稅後259.15億/EPS194.17 | ✓ | 鉅亨網/ETtoday 2025-01-09 |
| 22. FY2023: revenue NT$48.842bn / GM 48.53% / after-tax NT$17.908bn / EPS 134.18FY2023:營收488.42億/毛利率48.53%/稅後179.08億/EPS134.18 | ✓ | 鉅亨網 2025-01 |
| 23. 4Q25 EPS 50.4; 3Q25 EPS ≈53 (derived)4Q25 EPS50.4;3Q25 EPS≈53(推導) | ✓◆ derived推導 | 鉅亨網法說 2026-01-08 + this analysis's derivation鉅亨網法說 2026-01-08+本研究推導 |
| 24. Q2 2025 FX loss NT$4.22bn / EPS 7.73 (13-year low)Q2 2025匯損42.2億/EPS7.73(13年低) | ✓ | 經濟日報/旺得富 2025-07 |
| 25. Q1 2025 EPS 48.28 / gross margin 54.63%Q1 2025 EPS48.28/毛利率54.63% | ✓ | Yahoo/時報 2025-04 |
| Dividends & treasury shares股利與庫藏股 | ||
| 26. FY2025 dividend NT$80 total; 2026 H1 semi-annual payout NT$41.5 (payout ratio 50.39%, ex-dividend 08-13); 30 consecutive years of dividends2025年度股利合計80元;2026H1半年配41.5(配發率50.39%,8/13除息);連30年配息 | ✓ | 財報狗+鉅亨網 2026-07-27 |
| 27. Treasury shares: 2,670 board-lots, avg. NT$2,424.82, NT$647M total, to be cancelled, statutory ceiling NT$17.966bn (a market record for the ceiling)庫藏股:2,670張、均價2,424.82、6.47億、將註銷、上限179.66億創紀錄 | ✓ | 中央社 2026-02-02+工商時報 2025-12-27 |
| iPhone 18 variable apertureiPhone 18可變光圈 | ||
| 28. Variable aperture, decade's biggest camera upgrade, lens cost +50%iPhone18 Pro可變光圈、十年最大升級、鏡頭成本+50% | ✓ | TechNews 2026-06-02 |
| 29. Largan is one of the primary high-end suppliers for the iPhone 18 variable aperture (share unverified)大立光為iPhone 18可變光圈高階主力供應商之一(份額未證實) | ✓ "one of the primary suppliers" — reported「主力供應商之一」報導轉述 ⚠ "near-sole source" = rumor, media inference, never confirmed by the company or Apple (a counter-rumor also circulates — see #54)「近獨供」=傳聞:媒體推斷,未經公司或蘋果證實(另有反向傳聞,見#54) | 時報/豐雲學堂 2026-08 |
| 30. Sunny Optical rumored to take 40–50% of module assembly舜宇分食可變光圈模組40–50% | ⚠ unconfirmed supply-chain rumor供應鏈傳聞,未經證實 | supply-chain trade press 2026供應鏈媒體 2026 |
| 31. Genius Electronic Optical investing NT$1.86bn to expand capacity, targeting variable aperture玉晶光18.6億擴產劍指可變光圈 | ✓ | CMoney 2026-08 |
| 32. Apple event Taipei time 09-10; foldable iPhone possibly debuting蘋果發表會台北時間9/10;摺疊iPhone可望亮相 | ✓ | 瘋先生/eprice 2026-08-27 |
| CPO / FAU | ||
| 33. CPO: mass-production-tier customer spec document + samples shipped July + pilot line by end-Q3 + mass production "at the earliest" mid-2027CPO:量產型客戶規格文件+7月送樣+Q3底試產+最快2027年中放量 | ✓ | 鉅亨網/ETtoday法說 2026-07-09 |
| 34. CPO pilot line launching September, 0.3μm precision (2026-06-09 shareholder meeting)CPO試產線9月啟動、精度0.3μm(股東會6/9) | ✓ | 豐雲學堂 2026-06 |
| 35. First order is a single-row FA首單為單排FA | ✓ reported轉述 | simpletechtrend 2026-07 |
| 36. FAU = FA + MLA; Largan's 4-layer stacked FA + dual-row 80-channel PMLA; extending end-to-end to the FAU moduleFAU=FA+MLA;大立光四層堆疊FA+雙排80通道PMLA;一條龍到FAU模組 | ✓ | 工商時報 2026-07-16/經濟日報 2026-08-24 |
| 37. Supplying NVIDIA's Rubin Ultra = market speculation (not officially confirmed)供貨輝達Rubin Ultra=市場臆測(非官宣) | ✓ confirmed AS speculation確認為臆測 | 經濟日報 2026-08-24 |
| 38. GC vs EC routes; Corning's Glass Bridge uses EC; GC currently has larger market share (management framing)GC vs EC路線、康寧Glass Bridge走EC、GC市占目前較大(管理層說法) | ✓ management claim (share % not independently verified)管理層說法(市占未獨立驗證) | simpletechtrend轉述法說 |
| 39. Tolerance 0.3μm vs peers' 0.5–0.8μm; self-built equipment公差0.3μm vs同業0.5–0.8μm;自建設備 | ✓ reported from earnings call轉述法說 | simpletechtrend 2026-07 |
| 40. 2026: seven land and plant purchases since late June, NT$8.078bn in total (Taichung Nantun and Xitun, existing plants); latest 9/17, NT$1.172bn. Outlets count differently (an earlier 經濟日報 tally: four purchases, NT$5.648bn); the MOPS filings are canonical2026年自6月底起七度購地,合計80.78億元(台中南屯、西屯,買既有廠房);最近一筆9/17為11.72億元。各媒體統計口徑不同(經濟日報較早日期的統計為四筆56.48億元),以公開資訊觀測站重大訊息為準 | ✓ | 工商時報 2026-09-18/旺得富;鏡週刊 2026-09-21 |
| 41. Chairman Lin: AI reducing lens-upgrade need = "eating our future"; foldable lenses "not comparatively difficult"林恩平:AI減少鏡頭升級=「吃掉我們的未來」;摺疊鏡頭難度不高 | ✓ reported from earnings call轉述法說 | simpletechtrend 2026-07 |
| 42. Humanoid-robot vision-lens orders already in hand (2025-01 earnings call)機器人視覺鏡頭訂單到手(2025-01法說) | ✓ reported報導轉述 | 今周刊 2025-01-09 |
| Consensus, sell-side targets & price action共識、賣方目標價與股價動能 | ||
| 43. FactSet consensus: 19 analysts; 2026E EPS 187.55 / 2027E EPS 208.75 / 2028E EPS 239.29 (high 275.07); TP median NT$5,150FactSet共識:19人;2026E187.55/2027E208.75/2028E239.29(高275.07);TP中位5,150 | ✓ | 鉅亨網 via LINE 2026-08 |
| 44. Goldman Sachs NT$3,423→6,231 (7/1, verified highest); Citi NT$3,060→5,325; four major foreign brokers' highest NT$6,125 (07-13); Nomura NT$4,310→6,000; a US broker NT$3,535→5,325高盛3,423→6,231(7/1,已驗證最高);Citi3,060→5,325;四大外資最高6,125(7/13);野村4,310→6,000;美系3,535→5,325 | ✓ | 工商時報 2026-07-02/TechNews 2026-07-01/udn/經濟日報 |
| 45. Nomura, 2026-10-06: Buy reiterated, target NT$6,000→8,300 (about 23.3% upside at the time); first time CPO/FAU enters its earnings model, about 18% of 2028 EPS; each extra million FAU units is about NT$10 of EPS; says the fully automated pilot line was ready by end-Q3 2026 and the first mass-production line arrives 1H27 (Nomura's statement, not a company confirmation). Nomura's revised 2026/2027 EPS were not obtained野村 2026-10-06:維持買進,目標價 6,000→8,300(當時約 23.3% 上漲空間);首次把 CPO/FAU 放進獲利模型,約占 2028 年 EPS 的 18%;每多 100 萬個 FAU 約多 10 元 EPS;稱全自動試產線 2026 Q3 底就緒、首條量產線 2027 上半年(這是野村的說法,不是公司確認)。野村修正後的 2026/2027 EPS 未取得 | ✓ | 東森財經 2026-10-06; 時報資訊 2026-10-06東森財經 2026-10-06;時報資訊 2026-10-06 |
| 46. Stock doubled in 21 trading days (NT$3,670 on 07-30 → NT$7,195 on 08-27/28, +96%); limit-up to NT$6,290 on 08-2621天股價翻倍(7/30 3,670→8/27-28 7,195,+96%);8/26漲停6,290天價 | ✓ | 今周刊 2026-08-26/工商時報 2026-08-26 |
| 47. Traditional sell-side estimates CPO at 1–2% of 2028 revenue; Citi's bull case models 10% FAU share → 20% of revenue賣方傳統派估CPO 2028占營收1–2%;Citi藍天估2028市占10%→占營收20% | ✓ reported, two camps stated side by side轉述,兩派並列 | simpletechtrend/經濟日報 2026-08-24 |
| 48. A well-known local commentator ("the NT$100M professor"): CPO could push EPS above NT$300; "NT$6,000 is Largan performing at its potential"億元教授:CPO放量EPS可逾300、6,000元=發揮實力 | ✓ opinion屬意見 | 今周刊 2026-08-26 |
| 2026-09-02 external review round2026-09-02 外部審閱修訂 | ||
| 49. 4Q25 gross margin 47.75%; 1Q26 gross margin 49.4%, EPS 46.63 (directly confirmed)4Q25毛利率47.75%;1Q26毛利率49.4%、EPS46.63(直接證實) | ✓ | Yahoo/豐雲學堂 2026-04法說 |
| 50. Trailing-4Q gross margin ≈48.3% (= (FY25 gross profit 308.0 − H1'25 142.9 + H1'26 144.32) ÷ (611.48 − 262.5 + 292.09)); H1'26 gross profit 144.32, +1% YoY近四季毛利率≈48.3%(=(FY25毛利308.0−H1'25 142.9+H1'26 144.32)÷(611.48−262.5+292.09));H1'26營業毛利144.32億,年增僅1% | ✓◆ inputs verified, ratio derived輸入均查證,比率為本研究推算 | 時報 2026-07-09+本研究推算 |
| 51. Goldman Sachs initiated/reiterated Buy 7/1, TP NT$3,423→6,231 (market's highest at the time); 2026-28 net-profit estimates raised 6%/11%/11%高盛7/1評等買進、TP 3,423→6,231(當時市場最高);2026-28淨利上調6%/11%/11% | ✓ | 工商時報 2026-07-02/TechNews 2026-07-01 |
| 52. Cash & equivalents NT$115.942bn at FY2025-end (≈NT$885/share)現金及約當現金2025年底115.942億元(每股約885元) | ✓ | 富邦資產負債表年表 |
| 53. Cash & equivalents NT$118,482,131k = NT$118.482bn at Q2 2026-end (≈NT$905.75/share)2026 Q2末現金及約當現金118,482,131千元=1,184.82億元(每股約905.75元) | ✓ closing cash balance on the consolidated cash-flow statement; note the summary pages at Yahoo / 富邦 / goodinfo do not carry this line, so no secondary source was cross-checked this round合併財報現金流量表期末現金餘額;註:Yahoo/富邦/goodinfo摘要頁皆不列此欄位,本輪未取得二次源複核 ✗→✓ ZH cell previously read 118.4億 — a 10x unit error, corrected原中文欄誤植「118.4億元」(差10倍),已更正 | 合併財報現金流量表 2026Q2+ifa.ai(每股現金)consolidated cash-flow statement 2026Q2 + ifa.ai |
| 54. A counter-rumor ("Largan declined extra orders") circulates alongside the near-sole-source rumor「大立光婉拒加單」等反向供應鏈傳聞 | ⚠ rumor, neither direction is a load-bearing argument傳聞,兩個方向都不作為論證支柱 | 外部審閱轉述 2026-09-02 |
| 55. Yuchang Optics 3406.TT close NT$1,050, trailing PER 27.19x玉晶光 3406.TT 收盤 1,050 元、近四季本益比 27.19 倍 | ✓ | Yahoo股市 2026-09-02 14:30 |
| 56. Sunny Optical 2382.HK close HK$71.50, PER 14.09x, EPS 5.10舜宇光學 2382.HK 收盤 HK$71.50、本益比 14.09 倍、EPS 5.10 | ✓ | stockanalysis 2026-09-02 |
| 57. Foxsemicon 3363.TWO close NT$780 (−6.00 / −0.76%, prev close 786), market cap NT$88.64bn; trailing-4Q EPS −1.22 (3Q25 +0.20 / 4Q25 −0.22 / 1Q26 −0.98 / 2Q26 −0.22), hence no PER上詮 3363.TWO 收盤 780 元(−6.00/−0.76%,昨收 786)、市值 886.40 億;近四季 EPS −1.22 元(2025Q3 +0.20/4Q25 −0.22/1Q26 −0.98/2Q26 −0.22),故無本益比 | ✗→✓ first draft printed NT$7,806 — Yahoo's page concatenated the price "780" with the change "6.00", and that page's own figures were self-contradictory (786 + 6.00 ≠ 7,806). Cross-verified at 鉅亨 as 780.初稿誤植 7,806 — Yahoo 頁面把股價「780」與漲跌「6.00」串接,且該頁自身數字即自相矛盾(昨收 786+6.00 ≠ 7,806)。經鉅亨交叉驗證為 780。 ✓ quarterly EPS reported; the four-quarter sum is this analysis's calculation四季EPS為公告數,加總為本研究計算 | 鉅亨 2026-09-02(價格)+Yahoo股市(季度EPS)鉅亨 2026-09-02 (price) + Yahoo (quarterly EPS) |
| 58. TFC 300394.SZ ¥250.00 (−1.77 / −0.70%, prev close 251.77); PE ≈118×; market cap ¥272.7bn ≈ NT$1.29tn (1.26× Largan's)天孚通信 300394.SZ ¥250.00(−1.77/−0.70%,昨收 251.77);本益比約118倍;市值 ¥2,727億 ≈ NT$1.29兆(=大立光的1.26倍) | ✗→✓ first draft used a stale 2026-08-17 quote of ¥275.69. The 250.00 / −1.77 / −0.70% read and investing.com's same-day 250.70 / −1.07 / −0.43% both work off the same prev close of 251.77, so they agree; PE and market cap are investing.com's, rescaled to 250.00初稿誤用2026-08-17舊報價¥275.69。250.00/−1.77/−0.70% 與 investing.com 同日 250.70/−1.07/−0.43% 同以昨收251.77起算,兩者一致;PE與市值取自investing.com並按250.00折算 | investing.com 2026-09-02 |
| 59. FX rate CNY/TWD = 4.7307 (used for TFC's market-cap conversion)匯率 CNY/TWD = 4.7307(用於天孚市值換算) | ✓ | Google Finance 2026-09-02 |
| 60. Foxsemicon shares outstanding 113,640,567; 780 × 113.64M = NT$88.6bn market cap, matching 鉅亨's display上詮在外流通股數 113,640,567 股;780 × 1.1364億股 = 市值886億元,與鉅亨顯示一致 | ✓ share count reported; the product is this analysis's reconciliation股數為公告數,乘積為本研究對帳 | Yahoo股市 profile 2026-09-02+鉅亨Yahoo profile 2026-09-02 + 鉅亨 |
| 61. Implied value of Largan's CPO option NT$345.8bn (lens business priced at Yuchang's 27.5×); NT$629.0bn / NT$678.3bn at 16× / 14× anchors大立光 CPO 選擇權隱含價值 3,458 億元(鏡頭本業以玉晶光27.5×定價);換錨16×/14× 則為 6,290/6,783 億 | ◆ this analysis's derivation; inputs (EPS 188.02, close 7,810, 131M shares) all verified本研究推導;輸入(EPS 188.02、收盤7,810、股數1.31億股)皆已✓ | 本研究計算this analysis |
| 2026-10-07 refresh (new rows; they supersede the matching 09-02 rows)2026-10-07 更新(新增列;取代 09-02 對應列) | ||
| 62. Close NT$6,845 on 2026-10-07 (prior close 6,855, -10 / -0.15%), settled 13:30 TPE. The 10-05 close of 6,730 in the bar series also matches 鉅亨's report of NT$6,730.收盤 6,845 元(2026-10-07,前收 6,855,-10/-0.15%),台北時間 13:30 已收盤。日線的 10-05 收盤 6,730 元,與鉅亨 10-05 報導的 6,730 元一致。 | ✓ IBKR 日線最後一根+快照last IBKR daily bar + snapshot | IBKR (contract 38768990, TWSE) 2026-10-07 |
| 63. 52-week range 2,020–7,995 from daily bars 2025-10-08 to 2026-10-07 (the snapshot field low_52w 1,975.72 is on a different basis and is not used)52週區間 2,020–7,995,取自 2025-10-08 至 2026-10-07 日線(快照欄位 low_52w 1,975.72 口徑不同,不採用) | ✓ | IBKR 2026-10-07 |
| 64. Market cap ≈NT$0.90tn = 6,845 × 131M; PER 36.4x = 6,845 ÷ 188.02 (EPS from the 09-02 pull, Q3 not out); PBR 5.52x = 6,845 ÷ 1,240.07; yield 1.17% = 80 ÷ 6,845市值約 0.90 兆=6,845×1.31億股;PER 36.4 倍=6,845÷188.02(EPS 為 09-02 取數,第 3 季未公布);PBR 5.52 倍=6,845÷1,240.07;殖利率 1.17%=80÷6,845 | ◆ 本研究推導this analysis's derivation | 本研究計算this analysis |
| 65. September revenue NT$5.779bn (+15.31% MoM, -7.31% YoY); Q3 NT$15.651bn (+14.53% QoQ, -11.46% YoY); Jan–Sep NT$44.86bn (+2.12%). Company figures used. Jul+Aug+Sep = 15.668 and Jan–Aug 39.093 + 5.779 = 44.872 differ by 0.017 and 0.012 from the company totals.9月營收 57.79 億(月增 15.31%、年減 7.31%);第 3 季 156.51 億(季增 14.53%、年減 11.46%);1–9 月 448.6 億(+2.12%)。採公司公布數字。7+8+9 月加總 156.68 億、1–8 月 390.93+57.79=448.72 億,與公司合計各差 0.17 億與 0.12 億。 | ✓ 公司公告,媒體轉載company release via press | 鉅亨網 + 中央社 2026-10-05 |
| 66. August revenue NT$5.012bn (+2.76% MoM, -16.23% YoY); Jan–Aug NT$39.093bn (+3.71%). Below this analysis's NT$5.5bn bar (this analysis's own threshold, not company guidance).8月營收 50.12 億(月增 2.76%、年減 16.23%);1–8 月 390.93 億(+3.71%)。低於本研究 55 億門檻(本研究自訂,非公司數字)。 | ✓ | uanalyze 2026-09-05 |
| 67. Q3 revenue vs this analysis's 3Q26E: 156.51 vs 168 = -6.8%; at the page's rule of about NT$0.44bn of revenue per NT$1 of EPS, about -NT$2.6 of EPS第 3 季營收對本研究 3Q26E:156.51 對 168=-6.8%;按本頁每約 4.4 億元營收換 1 元 EPS 的規則,約 -2.6 元 EPS | ◆ 本研究推導this analysis's derivation | 本研究計算this analysis |
| 68. Company said October momentum is similar to September; the investor call is on 2026-10-08, online. Land: seven purchases announced since late June, totaling over NT$8bn, for future capacity.公司說 10 月動能與 9 月相當;法說會 2026-10-08 線上舉行。購地:自 6 月底起七度公告,合計逾 80 億元,用於未來擴產。 | ✓ | 中央社 2026-10-05; Yahoo 2026-10-05 |
| 69. Apple event 2026-09-10: iPhone 18 Pro and Pro Max both have a mechanical variable aperture on the 48MP main camera. No supplier was named, so Largan's share remains unverified.蘋果 2026-09-10 發表會:iPhone 18 Pro 與 Pro Max 的 4800 萬畫素主相機都有機械式可變光圈。沒有點名供應商,大立光份額維持未驗證。 | ✓ / ⚠ 未核實/單源unverified / single-source | inside.com.tw 2026-09-10 |
| 70. FactSet (18 analysts, 2026-10-05): 2026E EPS median 187.88 (from 189.1); 2027E 207.04 (high 229.89, low 192.3); 2028E 239.29 (high 341.95, low 203.91); target-price median NT$5,300. The 2028 high rose from 275.07 to 341.95.FactSet(18人,2026-10-05):2026E EPS 中位 187.88(前次 189.1);2027E 207.04(高 229.89、低 192.3);2028E 239.29(高 341.95、低 203.91);目標價中位 5,300。2028 最高值從 275.07 升到 341.95。 | ✓ | 鉅亨網 2026-10-05 22:11 |
| 71. Foreign ownership 24.63% (2026-10-06). Foreign net flow over the 14 sessions 09-15 to 10-06 sums to about -2,583 board-lots (buys on only 09-15 +368 and 10-01 +116).外資持股 24.63%(2026-10-06)。2026-09-15 到 10-06 十四個交易日外資合計淨賣約 2,583 張(只有 09-15 買超 368 張、10-01 買超 116 張)。 | ✓ ◆ 本研究推導this analysis's derivation | Yahoo 籌碼頁 2026-10-06; 合計為本研究加總sum is this analysis's |
| 72. Genius Electronic Optical 3406.TT close NT$1,085 (+3.83%, prior close 1,045), Yahoo PER 28.27x; the IBKR daily bar gives the same close. Market cap about NT$122bn is scaled from the 09-02 figure by price.玉晶光 3406.TT 收盤 1,085 元(+3.83%,昨收 1,045),Yahoo 本益比 28.27 倍;IBKR 日線收盤相同。市值約 1,223 億元是依 09-02 市值按股價比例推算。 | ✓ / ⚠ 未核實/單源unverified / single-source | Yahoo + IBKR 2026-10-07 |
| 73. Sunny Optical 2382.HK close HK$64.96 (IBKR); stockanalysis intraday HK$65.05, PER 12.56x, EPS 5.10, market cap HK$69.98B舜宇光學 2382.HK 收盤 HK$64.96(IBKR);stockanalysis 盤中 HK$65.05、本益比 12.56 倍、EPS 5.10、市值 HK$69.98B | ✓ | IBKR + stockanalysis 2026-10-07 |
| 74. Foxsemicon 3363.TWO close NT$679 (+29 / +4.46%, prior close 650); market cap NT$77.2bn = 679 × 113,640,567 shares; trailing EPS −1.22 unchanged from the 09-02 pull上詮 3363.TWO 收盤 679 元(+29/+4.46%,昨收 650);市值 771 億元=679×113,640,567 股;近四季 EPS -1.22 沿用 09-02 取數 | ✓ ◆ 本研究推導this analysis's derivation | Yahoo + IBKR 2026-10-07 |
| 75. TFC 300394.SZ last bar ¥260.78 on 2026-09-30 (China markets closed for the holiday until 10-08); PER about 123x and market cap about ¥284.5bn are the 09-02 figures (EPS ≈ ¥2.12, 1.091bn shares) re-priced; FX 4.741 = Bank of Taiwan spot mid on 10-01 (4.716 / 4.766); market cap about NT$1.35tn = 1.50x Largan天孚通信 300394.SZ 最後一根日線 ¥260.78(2026-09-30,中國市場放假到 10-08);本益比約 123 倍、市值約 ¥2,845 億,是把 09-02 數字(EPS 約 ¥2.12、10.91 億股)按新股價重算;匯率 4.741=台灣銀行 10-01 即期中間價(4.716/4.766);市值約 NT$1.35 兆=大立光的 1.50 倍 | ⚠ 未核實/單源unverified / single-source ◆ 本研究推導this analysis's derivation | IBKR 2026-09-30; 台灣銀行 2026-10-01 |
| 76. Implied value of Largan's CPO option: NT$200.4bn with the lens business at Genius's 28.27x; NT$502.6bn at 16x; NT$587.3bn at Sunny's 12.56x; 2.6 / 6.5 / 7.6 times Foxsemicon's market cap大立光 CPO 選擇權隱含價值:鏡頭本業比照玉晶光 28.27 倍為 2,004 億元;比照 16 倍為 5,026 億;比照舜宇 12.56 倍為 5,873 億;分別是上詮市值的 2.6/6.5/7.6 倍 | ◆ 本研究推導this analysis's derivation | 本研究計算(輸入已 ✓/⚠)this analysis (inputs ✓/⚠ as above) |
| 77. TradingView pull for TWSE:3008 hit HTTP 429 (rate limit); only the document and news lists were saved. No Largan earnings-call transcript exists on TradingView.TradingView 對 TWSE:3008 的拉取遇到 HTTP 429(限流),只存了文件與新聞清單。TradingView 上沒有大立光的法說逐字稿。 | ⚠ 未核實/單源unverified / single-source | tv_pull 2026-10-07 |
| 78. FactSet revenue consensus (18 analysts): 2026 median NT$67.26bn (mean 66.77, range 62.21 to 73.21); 2027 median NT$73.21bn (range 67.80 to 95.01)FactSet 營收共識(18 位分析師):2026 年中位數 672.6 億元(平均 667.7,範圍 622.1 至 732.1);2027 年中位數 732.1 億元(範圍 678.0 至 950.1) | ✓ | 鉅亨 2026-10-05 |
| 79. Q4 path: January to September NT$44.86bn; 2026E of NT$63.7bn needs about NT$18.8bn in Q4; with November and December near September's NT$5.779bn, Q4 is about NT$17.3 to 17.5bn and the year about NT$62.2bn. Nomura ruler: NT$10 of EPS per million FAU units is about NT$4.4bn of revenue第 4 季路徑:1 至 9 月 448.6 億元;達到 2026E 的 637 億元,第 4 季約需 188 億元;11、12 月若接近 9 月的 57.79 億元,第 4 季約 173 至 175 億元,全年約 622 億元。野村的尺:每 100 萬個 FAU 約 10 元 EPS,約等於 44 億元營收 | ◆ 本研究推導this analysis's derivation | 本研究計算this analysis |
| 2026-10-08 refresh (after the Q3 call; new rows supersede matching earlier rows)2026-10-08 更新(第 3 季法說後;新增列取代先前對應列) | ||
| 80. Q3 2026 company call deck, NT$ thousand (unaudited): revenue 15,650,820; gross profit 6,606,834 (42.21%); operating income 4,735,036 (30.25%); non-operating 1,356,807; pretax 6,091,843; net income 5,182,451; EPS 39.62. Q2: revenue 13,664,759; gross profit 6,752,934; operating income 5,148,005; net income 4,669,978; EPS 35.73. Q1: revenue 15,544,079; gross profit 7,679,569; operating income 5,812,218; net income 6,123,204; EPS 46.63. Jan–Sep: revenue 44,859,658 (+2%); gross profit 21,039,337 (-7%); operating income 15,695,259 (-9%); non-operating 3,783,699; net income 15,975,633 (+10%); EPS 121.98 (109.06 a year earlier). Balance sheet 2026-09-30: assets 221,362,776; equity 193,350,320; liabilities 28,012,456公司法說簡報 2026-10-08(未經會計師查核),千元:第 3 季營收 15,650,820;毛利 6,606,834(42.21%);營業利益 4,735,036(30.25%);業外 1,356,807;稅前 6,091,843;淨利 5,182,451;EPS 39.62。第 2 季營收 13,664,759;毛利 6,752,934;營業利益 5,148,005;淨利 4,669,978;EPS 35.73。第 1 季營收 15,544,079;毛利 7,679,569;營業利益 5,812,218;淨利 6,123,204;EPS 46.63。1–3 季營收 44,859,658(+2%);毛利 21,039,337(-7%);營業利益 15,695,259(-9%);業外 3,783,699;淨利 15,975,633(+10%);EPS 121.98(去年同期 109.06)。2026-09-30 總資產 221,362,776;權益 193,350,320;負債 28,012,456 | ✓ | 公司法說簡報 2026-10-08 |
| 81. Q2 EPS 35.73 per the company deck; the page used 35.72 before and is aligned to the deck第 2 季 EPS 35.73(公司簡報);頁面先前寫 35.72,已對齊簡報 | ✓ | 公司法說簡報 2026-10-08 |
| 82. Close NT$6,660 on 2026-10-08 (-185, -2.70%; prior close 6,845); daily bar open 6,805, high 6,930, low 6,600收盤 6,660 元(2026-10-08,-185、-2.70%;前收 6,845);日線開 6,805、高 6,930、低 6,600 | ✓ | IBKR 日線+經濟日報 udn 2026-10-08 |
| 83. Derived: market cap NT$871.1bn = 6,660 × 130.80M shares (5,182,451 ÷ 39.62); trailing EPS 172.38 = 50.40 (159.46 − 109.06) + 46.63 + 35.73 + 39.62; PER 38.6x; book value per share 1,478 = 193,350,320 ÷ 130.80M; PBR 4.5x; trailing gross margin 47.1% = (82.22 + 210.39) ÷ (172.19 + 448.60); opex 3Q26 1,871,798 = 11.96% of revenue; effective tax 14.9%; yield 1.20% = 80 ÷ 6,660. The old book value 1,240.07 is replaced推導:市值 8,711 億元=6,660×1.3080 億股(5,182,451÷39.62);近四季 EPS 172.38=50.40(159.46−109.06)+46.63+35.73+39.62;本益比 38.6 倍;每股淨值 1,478=193,350,320÷1.3080 億股;PBR 4.5 倍;近四季毛利率 47.1%=(82.22+210.39)÷(172.19+448.60);第 3 季費用 1,871,798=營收 11.96%;有效稅率 14.9%;殖利率 1.20%=80÷6,660。舊每股淨值 1,240.07 已換掉 | ◆ 本研究推導derived | 本研究計算(輸入取自簡報) |
| 84. Company said October pull-in is about the same as September and November will decline (林恩平 at the call)公司說 10 月拉貨與 9 月相當,11 月會下滑(林恩平於法說會) | ✓ 兩個來源two sources | 自由財經 2026-10-08 14:41;台灣好新聞 taisounds 2026-10-08 14:44 |
| 85. New-phone pull-in peak has passed新機拉貨高峰已過 | ✓ 已查證(多源)verified, several sources | 知新聞 2026-10-08 16:22;ETtoday 16:10;TechNews 15:56;台灣好新聞 14:44 |
| 86. The company said Q3 gross margin fell for two reasons: green-power purchases and yield. Green power is a structural cost; 2027 green-power and product prices are set, so pass-through is 2028 at the earliest. Context: Largan recently signed renewable power purchase agreements (offshore wind and solar, 1.26 billion kWh)公司說第 3 季毛利率下滑有綠電購買與良率兩個原因。綠電是結構性成本;2027 年綠電與產品價格已定,轉進售價最快 2028 年。背景:大立光近期簽下再生能源購電合約(離岸風電加太陽能,12.6 億度) | ✓ 已查證(多源)verified, several sources | 知新聞 2026-10-08 16:22;ETtoday 16:10;TechNews 15:56;台灣好新聞 14:44;時報資訊 2026-10-08;購電合約見聯合報 udn 報導 |
| 87. The company itself named yield as one cause of the Q3 margin drop (the other is green-power purchases). Yield is improving gradually, but the new-phone peak has passed公司自己點名良率,是第 3 季毛利率下滑的原因之一(另一個是綠電購買);良率漸漸上來,但新機高峰已過 | ✓ 已查證(多源)verified, several sources | 知新聞 2026-10-08 16:22;ETtoday 16:10;TechNews 15:56;經濟日報 2026-10-08 |
| 88. CPO/FA: customer-related FA certification passed in September; capacity established in mid-2027; customer wants finished FAU shipped directly, possibly next year; all FAU equipment is made in-house; recent land purchases all have clear uses and new capacity is for FAU; FA gross margin depends on yield. FA price is agreed. The FA pilot line is finished and equipment is installed. The FAU line with carrier is targeted for the end of Q2 2027. FAU customer certification started this month. Plants on the new land start next year and finish around 2030. 2027 capex is higher than 2026. 2027 mass production is GC-based. No order value or unit count was givenCPO/FA:FA 客戶相關認證 9 月已通過;產能 2027 年中建立;客戶要直接收成品 FAU,最快明年;FAU 設備全部自製;近期購地都有明確用途、新增產能用在 FAU;FA 毛利率看良率;FA 價格已談定;FA 試產線已完工、設備已裝好;FAU 含載體產線目標 2027 年第 2 季底;FAU 客戶認證本月開始;新購土地廠房明年動工、約 2030 年完工;2027 年資本支出高於 2026 年;2027 年量產以 GC 型為主。沒有給訂單金額或數量 | ✓ 已查證(多源)verified, several sources | 台灣好新聞 2026-10-08;ETtoday 2026-10-08;TechNews 2026-10-08;abmedia 2026-10-08 |
| 89. Q3 lens shipment mix: 10MP 60–70%, 20MP+ 10–20%, 8MP 0–10%, others 20–30%; same bands as Q2 and September第 3 季鏡頭出貨組合:1,000 萬畫素 60–70%、2,000 萬畫素以上 10–20%、800 萬畫素 0–10%、其他 20–30%;與第 2 季及 9 月同區間 | ✓ 公司確認company-confirmed | 公司法說簡報 2026-10-08 |
| 90. Non-operating income NT$1.357bn is not broken down in the deck. The Taiwan dollar moved about 0.05% in Q3業外 13.57 億元,公司簡報未拆分組成。台幣第 3 季變動約 0.05% | ⚠ 單源single source | 公司法說簡報 2026-10-08;優分析 2026-09-30 |
| 91. New estimates: 2026E revenue 602, gross margin 45.9%, EPS 159; 3Q26A and 4Q26E (revenue 153, gross margin 43%, EPS 37); 2027E revenue 660, gross margin 47.0%, EPS 173; TP 173 × 26 = 4,498, rounded to 4,500; scenarios 150×18 / 173×26 / 200×32 at 25/50/25%, weighted 4,525; entry zone 3,300–3,800新估計:2026E 營收 602、毛利率 45.9%、EPS 159;3Q26A 與 4Q26E(營收 153、毛利率 43%、EPS 37);2027E 營收 660、毛利率 47.0%、EPS 173;目標價 173×26=4,498,取整 4,500;情境 150×18/173×26/200×32,機率 25/50/25,加權 4,525;進場區 3,300–3,800 | ◆ 本研究判斷this analysis | 本研究判斷 2026-10-08 |
10-07 refresh: rows 62–77 add 16 rows (verified, derived or flagged, each tagged in its own row). The count below is for the original 09-02 ledger of 61 rows. Verdict count: 55 VERIFIED / 3 UNCERTAIN (#30, #45, #54) / 3 derived calculations (#23, #50, #61). Two items were upgraded from UNCERTAIN to VERIFIED this round (#8 foreign-ownership level, #53 Q2 cash) and three were corrected in place (#1 close price, #8 the 投信 buying streak, #53 a ZH unit error). UNCERTAIN items are consistently flagged ⚠ or presented with rumor/reported-speech framing on the page — never used as an argument's load-bearing support.10-07 更新:第 62–77 列新增 16 項(各列自帶判定)。以下統計只算 09-02 的原 61 項。判定統計:VERIFIED 55/UNCERTAIN 3(#30、#45、#54)/派生計算3(#23、#50、#61)。本輪2項自UNCERTAIN升級為VERIFIED(#8外資水準值、#53 Q2現金),3項原位更正(#1收盤價、#8投信買超天數、#53中文欄位單位)。UNCERTAIN項在頁面一律標⚠或以「傳聞/報導」語氣呈現,不作為論證支柱。